
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_______________
FORM 8-K/A
(Amendment No. 1)
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (date of earliest event reported) September 4, 2026
______________
(Exact name of registrant as specified in its charter)
_______________
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of principal executive offices, including Zip Code)
Registrant's telephone number, including area code: (949 ) 418-1801
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
The Nasdaq Global Market LLC ( | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
EXPLANATORY NOTE
On September 10, 2026, Tarsus Pharmaceuticals, Inc. (the “Company”) filed a Current Report on Form 8-K (the “Original Form 8-K”) with the U.S. Securities and Exchange Commission (the “SEC”) in connection with the completion of the Company’s acquisition (the “Acquisition”) of Alkeus Pharmaceuticals, Inc. (“Alkeus”), pursuant to that certain Agreement and Plan of Merger, dated as of July 31, 2026, by and among the Company, Alkeus, Apex 2026 Merger Sub, Inc., a Delaware corporation and wholly-owned subsidiary of the Company, and Shareholder Representative Services LLC, a Colorado limited liability company solely in its capacity as the securityholders’ representative.
This Current Report on Form 8-K/A (this “Amendment No. 1”) amends the Original Form 8-K to provide the historical financial statements of Alkeus and pro forma financial information required by Items 9.01(a) and (b) of Form 8-K, which were omitted from the Original Form 8-K as permitted by paragraphs (a)(3) and (b)(2) of Item 9.01 of Form 8-K.
The pro forma financial information included in this Amendment No. 1 has been presented for informational purposes only, as required by Form 8-K. It does not purport to represent the actual results of operations that the Company and Alkeus would have achieved had the companies been combined during the periods presented in the pro forma financial information, and is not intended to project the future results of operations that the combined company may achieve following completion of the Acquisition.
Except as described above, this Amendment No. 1 does not otherwise amend, modify, or update the disclosures contained in the Original 8-K.
Item 9.01 Financial Statements and Exhibits.
(a) Financial statements of businesses or funds acquired.
The audited consolidated financial statements of Alkeus as of September 30, 2025 and 2024 and for the fiscal years ended September 30, 2025 and 2024 are filed as Exhibit 99.1 hereto and are incorporated herein by reference. The consent of PricewaterhouseCoopers LLP, Alkeus’ independent auditor, is attached as Exhibit 23.1 to this Amendment No. 1.
The unaudited consolidated financial statements of Alkeus as of June 30, 2026 and 2025 and for the nine months ended June 30, 2026 and 2025 are filed as Exhibit 99.2 hereto and are incorporated herein by reference.
(b) Pro Forma Financial Information
The unaudited pro forma consolidated balance sheet as of June 30, 2026, the unaudited pro forma consolidated statement of operations and comprehensive loss for the six months ended June 30, 2026 and the unaudited pro forma consolidated statement of operations and comprehensive loss for the year ended December 31, 2025 are filed as Exhibit 99.3 hereto and are incorporated herein by reference.
(d) Exhibits.
Exhibit No. | Description | ||||||||||||||||
| 23.1 | |||||||||||||||||
| 99.1 | |||||||||||||||||
| 99.2 | |||||||||||||||||
| 99.3 | |||||||||||||||||
| 104 | Cover Page Interactive Data File (embedded within XBRL document) | ||||||||||||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| TARSUS PHARMACEUTICALS, INC. | ||||||||||||||||||||
| Date: | October 13, 2026 | By: | /s/ Jeffrey Farrow | |||||||||||||||||
| Jeffrey Farrow | ||||||||||||||||||||
| Chief Financial Officer and Chief Strategy Officer | ||||||||||||||||||||
| (Principal Financial Officer and Principal Accounting Officer) | ||||||||||||||||||||
CONSENT OF INDEPENDENT AUDITORS We hereby consent to the incorporation by reference in the Registration Statements on Form S-3 (Nos. 333-275439 and 333-277523) and Form S-8 (Nos. 333-249571, 333-254932, 333-263537, 333-270644, 333-277400, 333-285201 and 333-293651) of Tarsus Pharmaceuticals, Inc. of our report dated July 17, 2026 relating to the financial statements of Alkeus Pharmaceuticals, Inc., which appears in this Current Report on Form 8-K/A. /s/ PricewaterhouseCoopers LLP Boston, Massachusetts October 13, 2026 Exhibit 23.1
ALKEUS PHARMACEUTICALS, INC. Consolidated Financial Statements Years ended September 30, 2025 and 2024 Exhibit 99.1
1 ALKEUS PHARMACEUTICALS, INC. Consolidated Financial Statements Years ended September 30, 2025 and 2024 Table of Contents Report of Independent Auditors ................................................................................................................................................................ 2 Consolidated Balance Sheets ..................................................................................................................................................................... 4 Consolidated Statements of Operations and Comprehensive Loss ............................................................................................................ 5 Consolidated Statements of Redeemable Convertible Preferred Stock and Stockholders’ Deficit ............................................................ 6 Consolidated Statements of Cash Flows ................................................................................................................................................... 7 Notes to Consolidated Financial Statements ....................................................................................................................................... 8-25
Report of Independent Auditors To the Management and Board of Directors of Alkeus Pharmaceuticals, Inc. Opinion We have audited the accompanying consolidated financial statements of Alkeus Pharmaceuticals, Inc. and its subsidiary (the "Company"), which comprise the consolidated balance sheets as of September 30, 2025 and 2024, and the related consolidated statements of operations and comprehensive loss, of redeemable convertible preferred stock and stockholders' deficit and of cash flows for the years then ended, including the related notes (collectively referred to as the "consolidated financial statements"). In our opinion, the accompanying consolidated financial statements present fairly, in all material respects, the financial position of the Company as of September 30, 2025 and 2024, and the results of its operations and its cash flows for the years then ended in accordance with accounting principles generally accepted in the United States of America. Basis for Opinion We conducted our audit in accordance with auditing standards generally accepted in the United States of America (US GAAS). Our responsibilities under those standards are further described in the Auditors' Responsibilities for the Audit of the Consolidated Financial Statements section of our report. We are required to be independent of the Company and to meet our other ethical responsibilities, in accordance with the relevant ethical requirements relating to our audit. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our audit opinion. Substantial Doubt about the Company's Ability to Continue as a Going Concern The accompanying consolidated financial statements have been prepared assuming that the Company will continue as a going concern. As discussed in Note 1 to the consolidated financial statements, the Company has experienced negative operating cash flows since inception and has an accumulated deficit and has stated that substantial doubt exists about the Company’s ability to continue as a going concern. Management's evaluation of the events and conditions and management’s plans regarding these matters are also described in Note 1. The consolidated financial statements do not include any adjustments that might result from the outcome of this uncertainty. Our opinion is not modified with respect to this matter. Responsibilities of Management for the Consolidated Financial Statements Management is responsible for the preparation and fair presentation of the consolidated financial statements in accordance with accounting principles generally accepted in the United States of America, and for the design, implementation, and maintenance of internal control relevant to the preparation and fair presentation of consolidated financial statements that are free from material misstatement, whether due to fraud or error. In preparing the consolidated financial statements, management is required to evaluate whether there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company's ability to
2 continue as a going concern for one year after the date the consolidated financial statements are available to be issued. Auditors' Responsibilities for the Audit of the Consolidated Financial Statements Our objectives are to obtain reasonable assurance about whether the consolidated financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditors' report that includes our opinion. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with US GAAS will always detect a material misstatement when it exists. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. Misstatements are considered material if there is a substantial likelihood that, individually or in the aggregate, they would influence the judgment made by a reasonable user based on the consolidated financial statements. In performing an audit in accordance with US GAAS, we: • Exercise professional judgment and maintain professional skepticism throughout the audit. • Identify and assess the risks of material misstatement of the consolidated financial statements, whether due to fraud or error, and design and perform audit procedures responsive to those risks. Such procedures include examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. • Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Company's internal control. Accordingly, no such opinion is expressed. • Evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management, as well as evaluate the overall presentation of the consolidated financial statements. • Conclude whether, in our judgment, there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company's ability to continue as a going concern for a reasonable period of time. We are required to communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit, significant audit findings, and certain internal control-related matters that we identified during the audit. /s/ PricewaterhouseCoopers LLP Boston, Massachusetts July 17, 2026
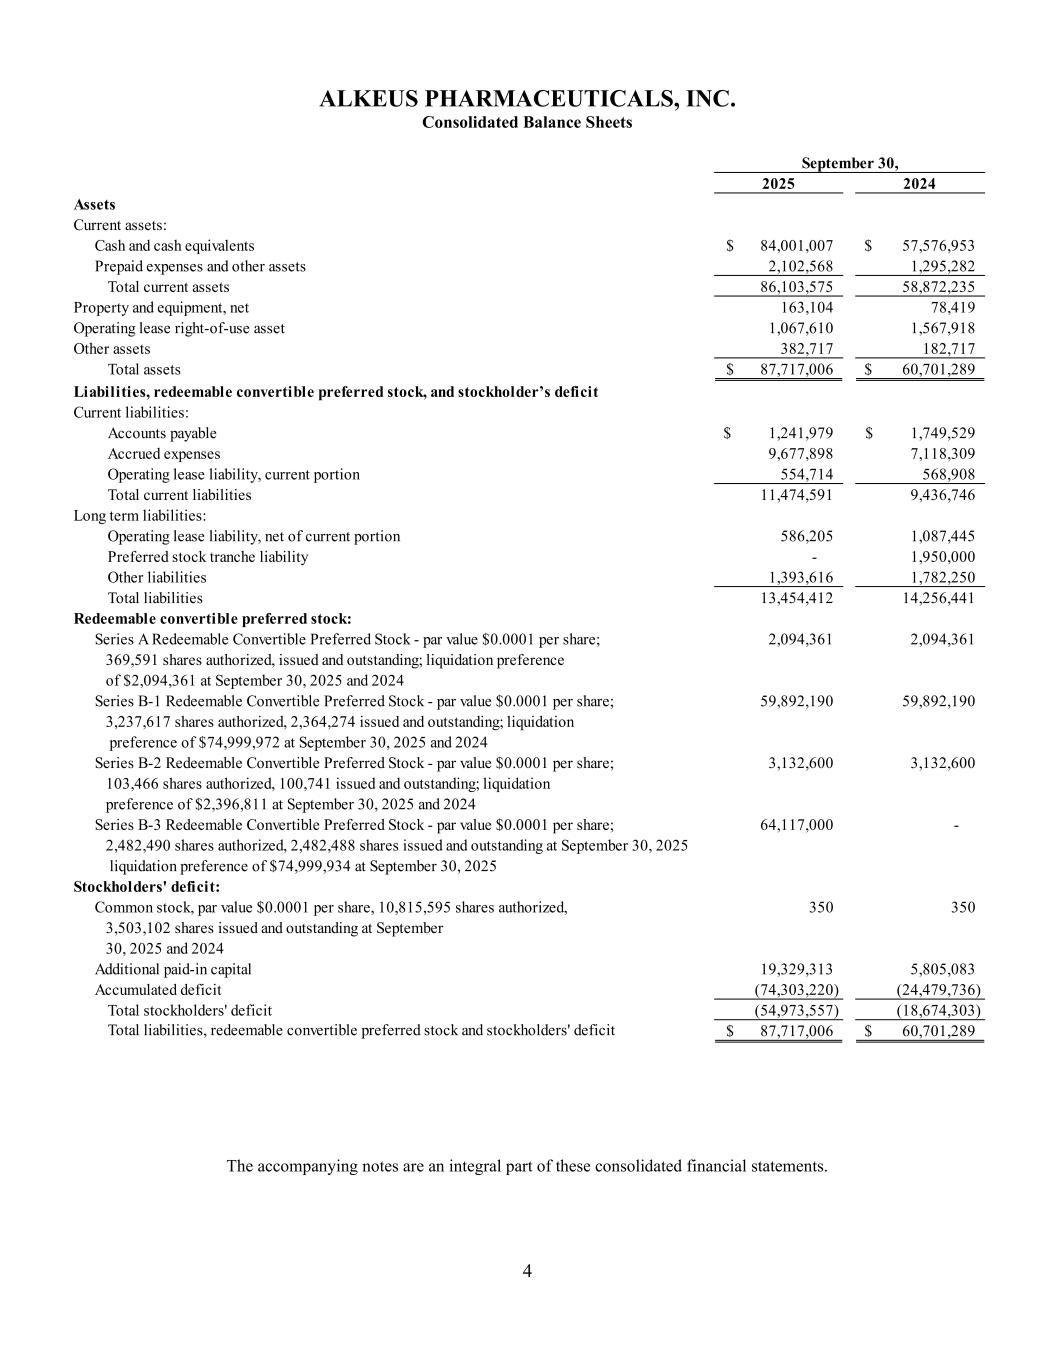
4 ALKEUS PHARMACEUTICALS, INC. Consolidated Balance Sheets 2025 2024 Assets Current assets: Cash and cash equivalents 84,001,007$ 57,576,953$ Prepaid expenses and other assets 2,102,568 1,295,282 Total current assets 86,103,575 58,872,235 Property and equipment, net 163,104 78,419 Operating lease right-of-use asset 1,067,610 1,567,918 Other assets 382,717 182,717 Total assets 87,717,006$ 60,701,289$ Liabilities, redeemable convertible preferred stock, and stockholder’s deficit Current liabilities: Accounts payable 1,241,979$ 1,749,529$ Accrued expenses 9,677,898 7,118,309 Operating lease liability, current portion 554,714 568,908 Total current liabilities 11,474,591 9,436,746 Long term liabilities: Operating lease liability, net of current portion 586,205 1,087,445 Preferred stock tranche liability - 1,950,000 Other liabilities 1,393,616 1,782,250 Total liabilities 13,454,412 14,256,441 Redeemable convertible preferred stock: Series A Redeemable Convertible Preferred Stock - par value $0.0001 per share; 2,094,361 2,094,361 369,591 shares authorized, issued and outstanding; liquidation preference of $2,094,361 at September 30, 2025 and 2024 Series B-1 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 59,892,190 59,892,190 3,237,617 shares authorized, 2,364,274 issued and outstanding; liquidation preference of $74,999,972 at September 30, 2025 and 2024 Series B-2 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 3,132,600 3,132,600 103,466 shares authorized, 100,741 issued and outstanding; liquidation preference of $2,396,811 at September 30, 2025 and 2024 Series B-3 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 64,117,000 - 2,482,490 shares authorized, 2,482,488 shares issued and outstanding at September 30, 2025 liquidation preference of $74,999,934 at September 30, 2025 Stockholders' deficit: Common stock, par value $0.0001 per share, 10,815,595 shares authorized, 350 350 3,503,102 shares issued and outstanding at September 30, 2025 and 2024 Additional paid-in capital 19,329,313 5,805,083 Accumulated deficit (74,303,220) (24,479,736) Total stockholders' deficit (54,973,557) (18,674,303) Total liabilities, redeemable convertible preferred stock and stockholders' deficit 87,717,006$ 60,701,289$ September 30, The accompanying notes are an integral part of these consolidated financial statements.
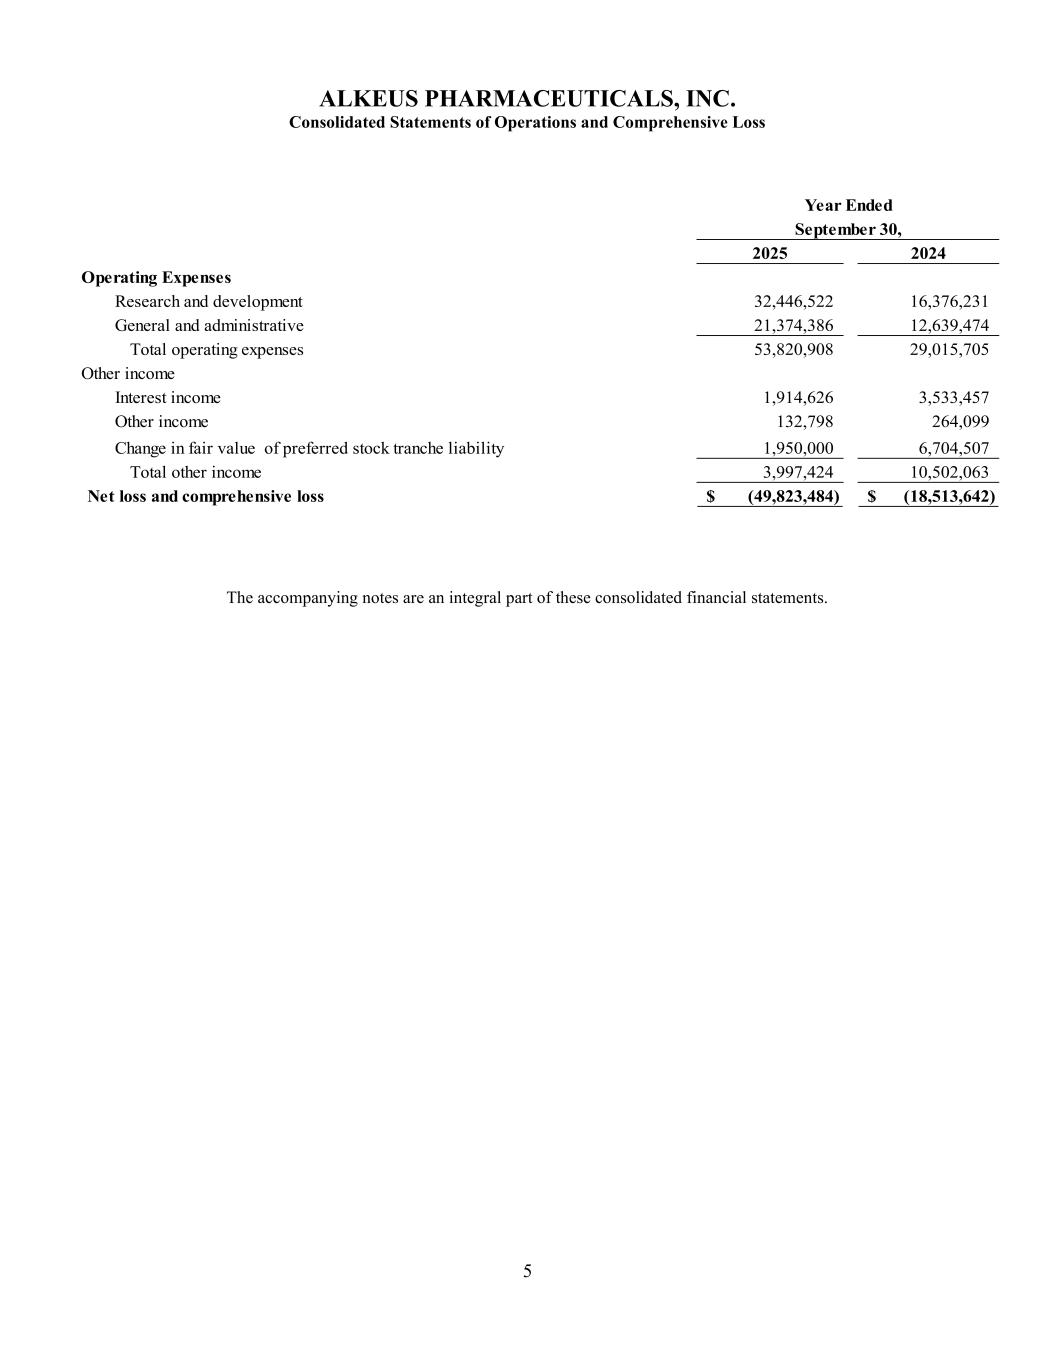
5 ALKEUS PHARMACEUTICALS, INC. Consolidated Statements of Operations and Comprehensive Loss 2025 2024 Operating Expenses Research and development 32,446,522 16,376,231 General and administrative 21,374,386 12,639,474 Total operating expenses 53,820,908 29,015,705 Other income Interest income 1,914,626 3,533,457 Other income 132,798 264,099 Change in fair value of preferred stock tranche liability 1,950,000 6,704,507 Total other income 3,997,424 10,502,063 Net loss and comprehensive loss (49,823,484)$ (18,513,642)$ Year Ended September 30, The accompanying notes are an integral part of these consolidated financial statements.
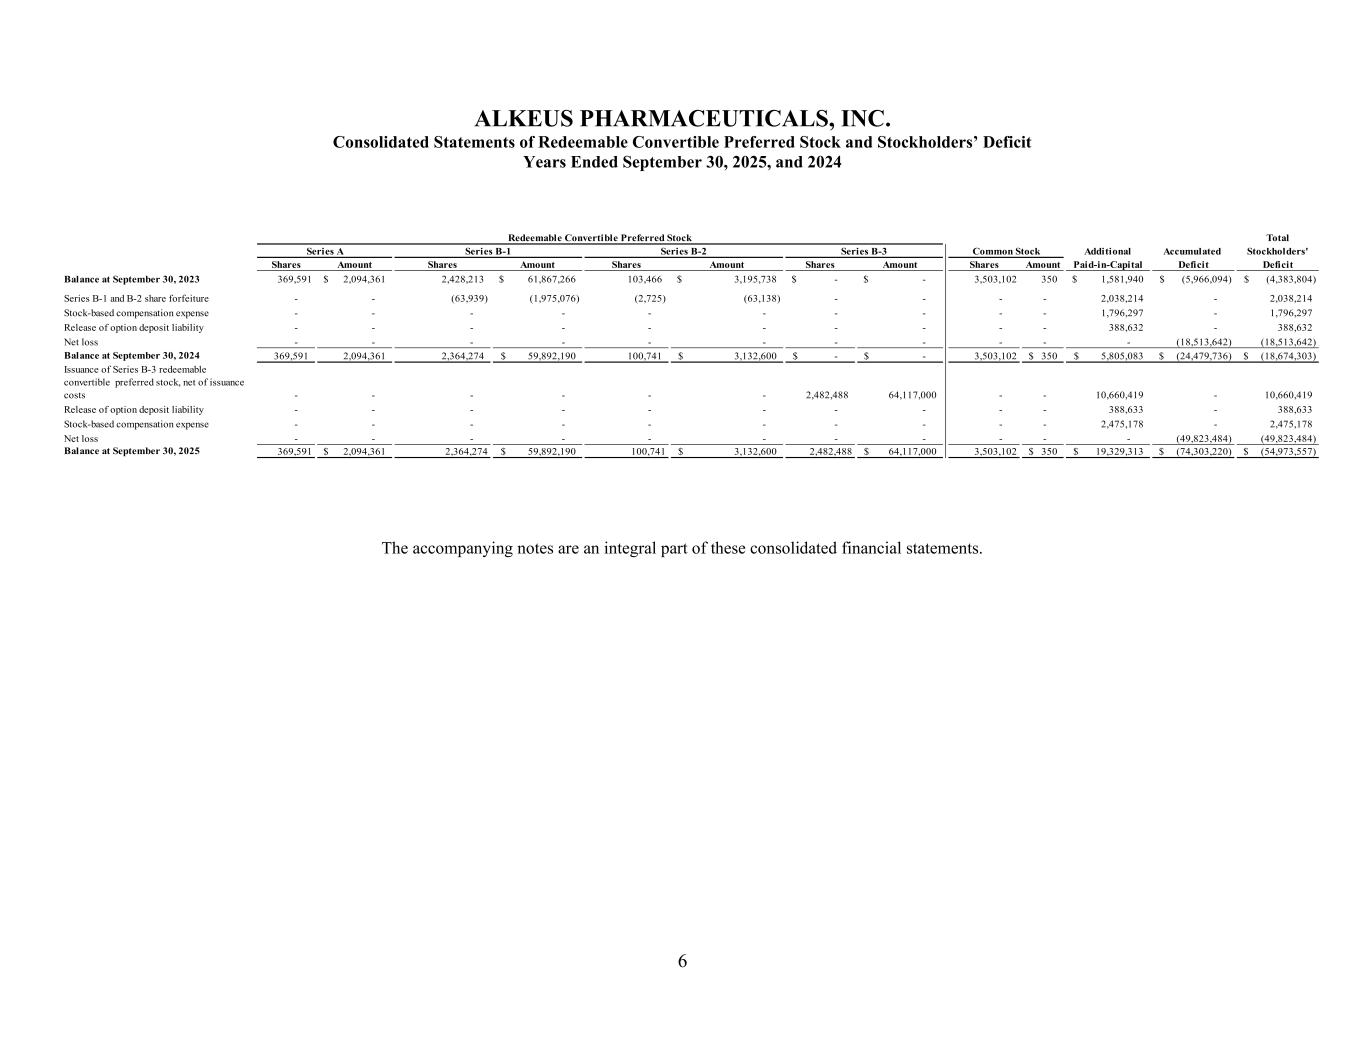
6 ALKEUS PHARMACEUTICALS, INC. Consolidated Statements of Redeemable Convertible Preferred Stock and Stockholders’ Deficit Years Ended September 30, 2025, and 2024 Total Additional Accumulated Stockholders' Shares Amount Shares Amount Shares Amount Shares Amount Shares Amount Paid-in-Capital Deficit Deficit Balance at September 30, 2023 369,591 2,094,361$ 2,428,213 61,867,266$ 103,466 3,195,738$ -$ -$ 3,503,102 350 1,581,940$ (5,966,094)$ (4,383,804)$ Series B-1 and B-2 share forfeiture - - (63,939) (1,975,076) (2,725) (63,138) - - - - 2,038,214 - 2,038,214 Stock-based compensation expense - - - - - - - - - - 1,796,297 - 1,796,297 Release of option deposit liability - - - - - - - - - - 388,632 - 388,632 Net loss - - - - - - - - - - - (18,513,642) (18,513,642) Balance at September 30, 2024 369,591 2,094,361 2,364,274 59,892,190$ 100,741 3,132,600$ -$ -$ 3,503,102 350$ 5,805,083$ (24,479,736)$ (18,674,303)$ Issuance of Series B-3 redeemable convertible preferred stock, net of issuance costs - - - - - - 2,482,488 64,117,000 - - 10,660,419 - 10,660,419 Release of option deposit liability - - - - - - - - - - 388,633 - 388,633 Stock-based compensation expense - - - - - - - - - - 2,475,178 - 2,475,178 Net loss - - - - - - - - - - - (49,823,484) (49,823,484) Balance at September 30, 2025 369,591 2,094,361$ 2,364,274 59,892,190$ 100,741 3,132,600$ 2,482,488 64,117,000$ 3,503,102 350$ 19,329,313$ (74,303,220)$ (54,973,557)$ Series A Series B-1 Series B-2 Common Stock Redeemable Convertible Preferred Stock Series B-3 The accompanying notes are an integral part of these consolidated financial statements.
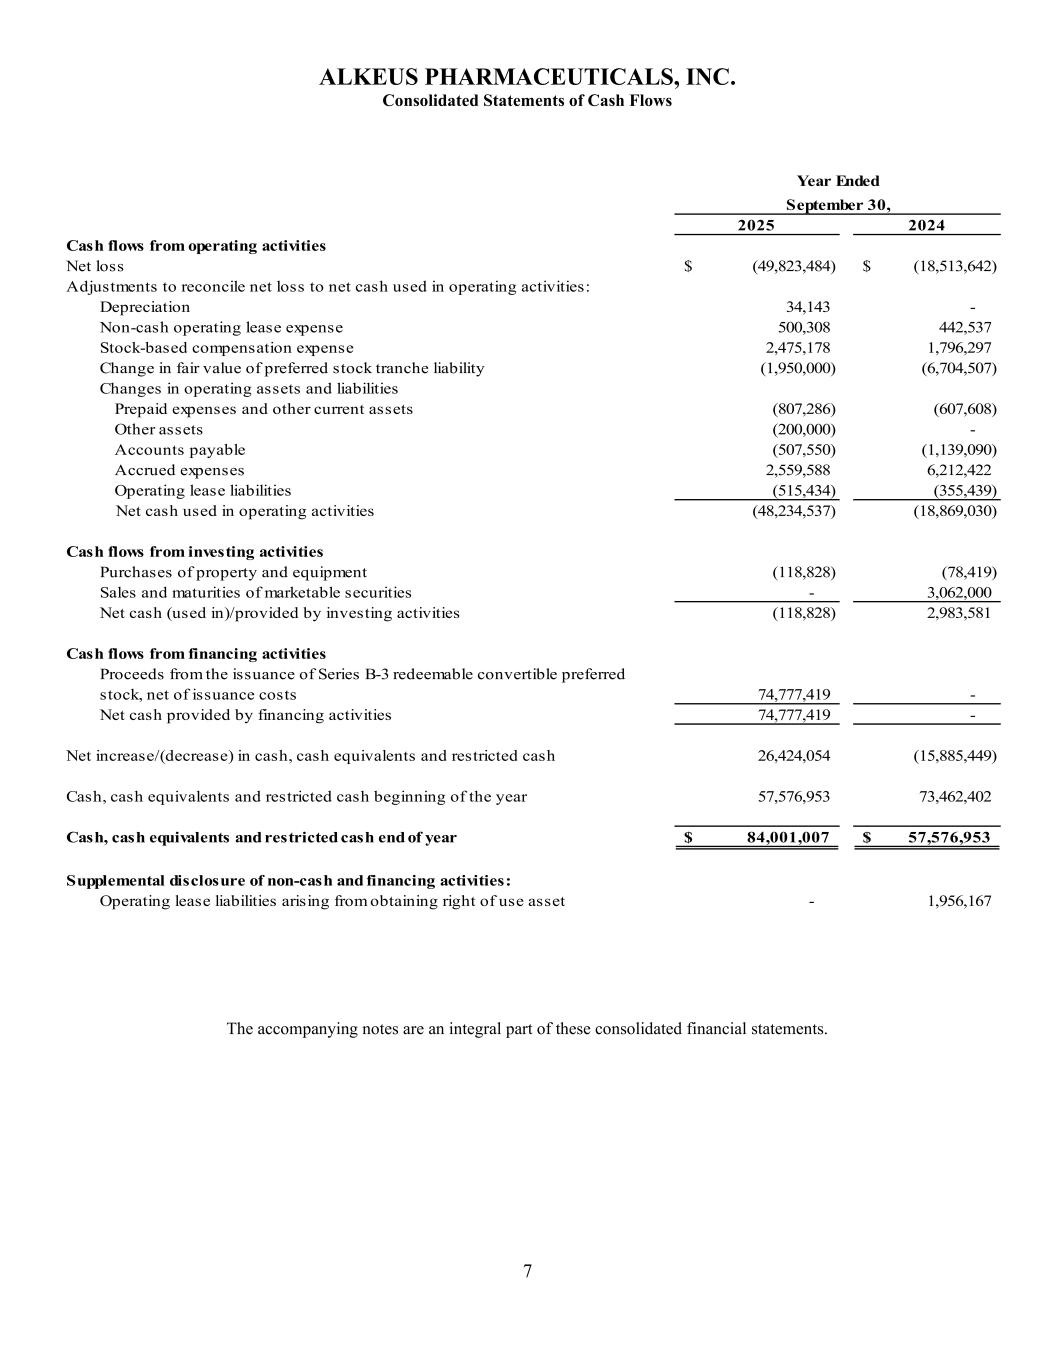
7 ALKEUS PHARMACEUTICALS, INC. Consolidated Statements of Cash Flows 2025 2024 Cash flows from operating activities Net loss (49,823,484)$ (18,513,642)$ Adjustments to reconcile net loss to net cash used in operating activities: Depreciation 34,143 - Non-cash operating lease expense 500,308 442,537 Stock-based compensation expense 2,475,178 1,796,297 Change in fair value of preferred stock tranche liability (1,950,000) (6,704,507) Changes in operating assets and liabilities Prepaid expenses and other current assets (807,286) (607,608) Other assets (200,000) - Accounts payable (507,550) (1,139,090) Accrued expenses 2,559,588 6,212,422 Operating lease liabilities (515,434) (355,439) Net cash used in operating activities (48,234,537) (18,869,030) Cash flows from investing activities Purchases of property and equipment (118,828) (78,419) Sales and maturities of marketable securities - 3,062,000 Net cash (used in)/provided by investing activities (118,828) 2,983,581 Cash flows from financing activities Proceeds from the issuance of Series B-3 redeemable convertible preferred stock, net of issuance costs 74,777,419 - Net cash provided by financing activities 74,777,419 - Net increase/(decrease) in cash, cash equivalents and restricted cash 26,424,054 (15,885,449) Cash, cash equivalents and restricted cash beginning of the year 57,576,953 73,462,402 Cash, cash equivalents and restricted cash end of year 84,001,007$ 57,576,953$ Supplemental disclosure of non-cash and financing activities: Operating lease liabilities arising from obtaining right of use asset - 1,956,167 Year Ended September 30, The accompanying notes are an integral part of these consolidated financial statements.
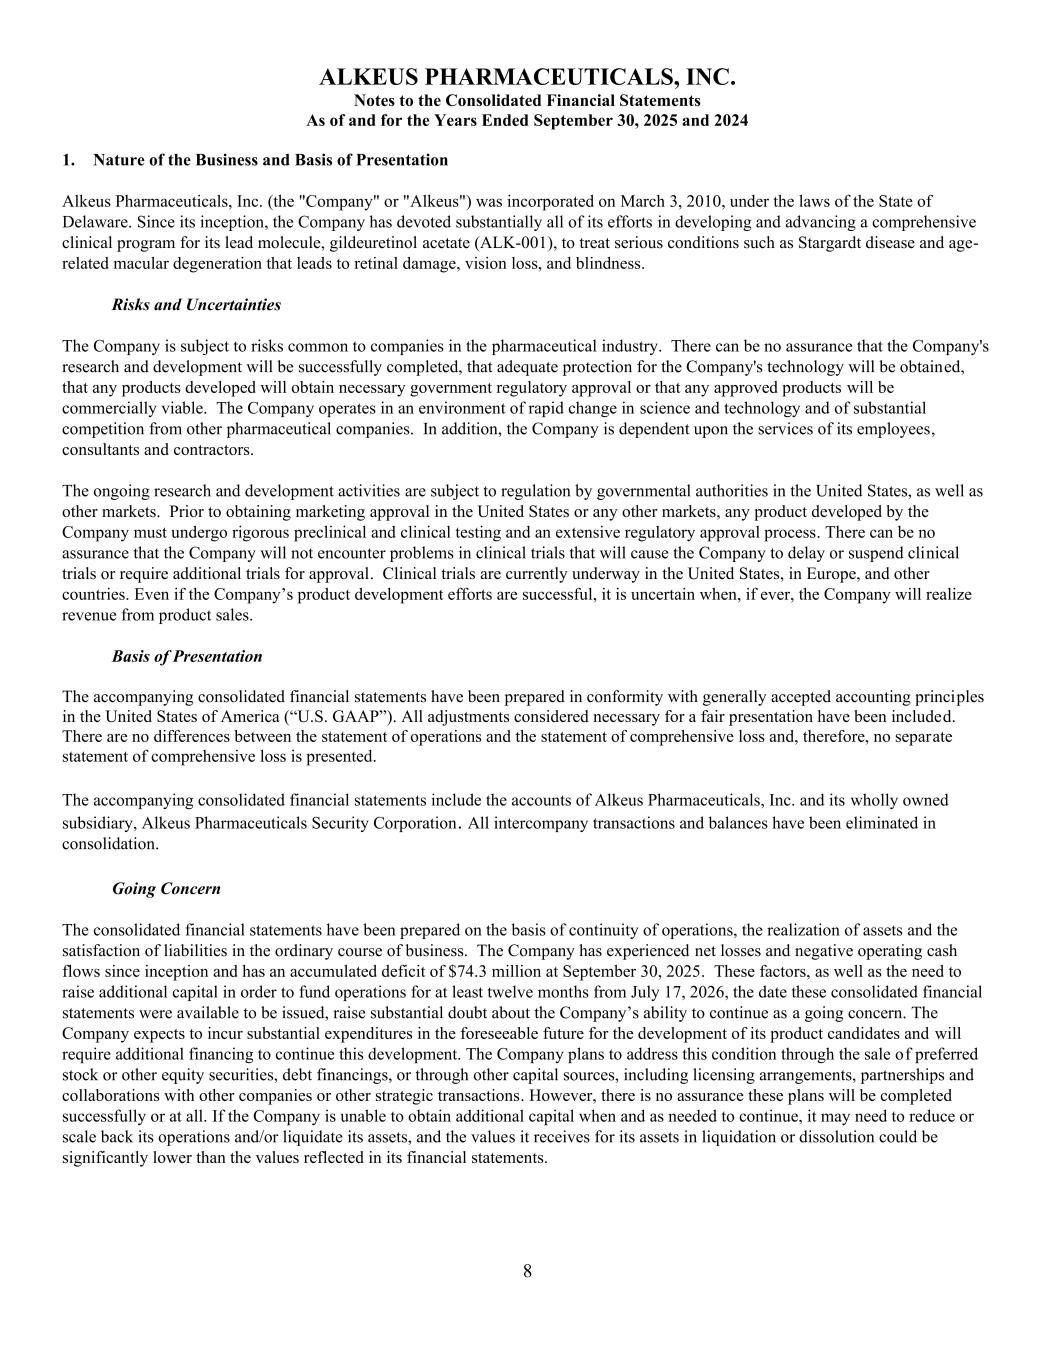
8 ALKEUS PHARMACEUTICALS, INC. Notes to the Consolidated Financial Statements As of and for the Years Ended September 30, 2025 and 2024 1. Nature of the Business and Basis of Presentation Alkeus Pharmaceuticals, Inc. (the "Company" or "Alkeus") was incorporated on March 3, 2010, under the laws of the State of Delaware. Since its inception, the Company has devoted substantially all of its efforts in developing and advancing a comprehensive clinical program for its lead molecule, gildeuretinol acetate (ALK-001), to treat serious conditions such as Stargardt disease and age- related macular degeneration that leads to retinal damage, vision loss, and blindness. Risks and Uncertainties The Company is subject to risks common to companies in the pharmaceutical industry. There can be no assurance that the Company's research and development will be successfully completed, that adequate protection for the Company's technology will be obtained, that any products developed will obtain necessary government regulatory approval or that any approved products will be commercially viable. The Company operates in an environment of rapid change in science and technology and of substantial competition from other pharmaceutical companies. In addition, the Company is dependent upon the services of its employees, consultants and contractors. The ongoing research and development activities are subject to regulation by governmental authorities in the United States, as well as other markets. Prior to obtaining marketing approval in the United States or any other markets, any product developed by the Company must undergo rigorous preclinical and clinical testing and an extensive regulatory approval process. There can be no assurance that the Company will not encounter problems in clinical trials that will cause the Company to delay or suspend clinical trials or require additional trials for approval. Clinical trials are currently underway in the United States, in Europe, and other countries. Even if the Company’s product development efforts are successful, it is uncertain when, if ever, the Company will realize revenue from product sales. Basis of Presentation The accompanying consolidated financial statements have been prepared in conformity with generally accepted accounting principles in the United States of America (“U.S. GAAP”). All adjustments considered necessary for a fair presentation have been included. There are no differences between the statement of operations and the statement of comprehensive loss and, therefore, no separate statement of comprehensive loss is presented. The accompanying consolidated financial statements include the accounts of Alkeus Pharmaceuticals, Inc. and its wholly owned subsidiary, Alkeus Pharmaceuticals Security Corporation. All intercompany transactions and balances have been eliminated in consolidation. Going Concern The consolidated financial statements have been prepared on the basis of continuity of operations, the realization of assets and the satisfaction of liabilities in the ordinary course of business. The Company has experienced net losses and negative operating cash flows since inception and has an accumulated deficit of $74.3 million at September 30, 2025. These factors, as well as the need to raise additional capital in order to fund operations for at least twelve months from July 17, 2026, the date these consolidated financial statements were available to be issued, raise substantial doubt about the Company’s ability to continue as a going concern. The Company expects to incur substantial expenditures in the foreseeable future for the development of its product candidates and will require additional financing to continue this development. The Company plans to address this condition through the sale of preferred stock or other equity securities, debt financings, or through other capital sources, including licensing arrangements, partnerships and collaborations with other companies or other strategic transactions. However, there is no assurance these plans will be completed successfully or at all. If the Company is unable to obtain additional capital when and as needed to continue, it may need to reduce or scale back its operations and/or liquidate its assets, and the values it receives for its assets in liquidation or dissolution could be significantly lower than the values reflected in its financial statements.
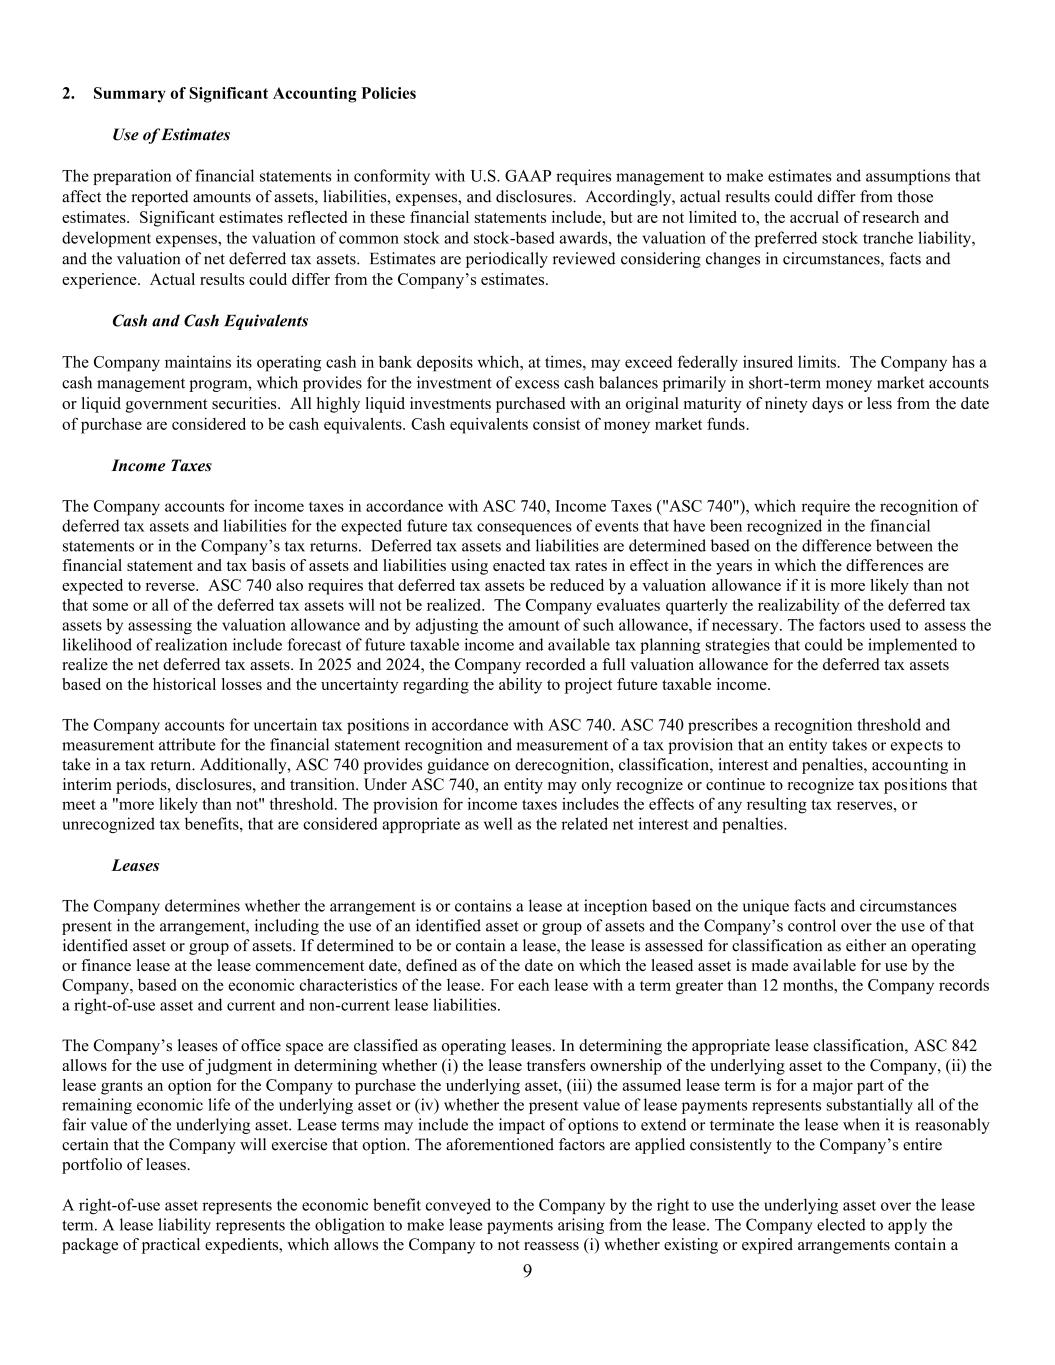
9 2. Summary of Significant Accounting Policies Use of Estimates The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets, liabilities, expenses, and disclosures. Accordingly, actual results could differ from those estimates. Significant estimates reflected in these financial statements include, but are not limited to, the accrual of research and development expenses, the valuation of common stock and stock-based awards, the valuation of the preferred stock tranche liability, and the valuation of net deferred tax assets. Estimates are periodically reviewed considering changes in circumstances, facts and experience. Actual results could differ from the Company’s estimates. Cash and Cash Equivalents The Company maintains its operating cash in bank deposits which, at times, may exceed federally insured limits. The Company has a cash management program, which provides for the investment of excess cash balances primarily in short-term money market accounts or liquid government securities. All highly liquid investments purchased with an original maturity of ninety days or less from the date of purchase are considered to be cash equivalents. Cash equivalents consist of money market funds. Income Taxes The Company accounts for income taxes in accordance with ASC 740, Income Taxes ("ASC 740"), which require the recognition of deferred tax assets and liabilities for the expected future tax consequences of events that have been recognized in the financial statements or in the Company’s tax returns. Deferred tax assets and liabilities are determined based on the difference between the financial statement and tax basis of assets and liabilities using enacted tax rates in effect in the years in which the differences are expected to reverse. ASC 740 also requires that deferred tax assets be reduced by a valuation allowance if it is more likely than not that some or all of the deferred tax assets will not be realized. The Company evaluates quarterly the realizability of the deferred tax assets by assessing the valuation allowance and by adjusting the amount of such allowance, if necessary. The factors used to assess the likelihood of realization include forecast of future taxable income and available tax planning strategies that could be implemented to realize the net deferred tax assets. In 2025 and 2024, the Company recorded a full valuation allowance for the deferred tax assets based on the historical losses and the uncertainty regarding the ability to project future taxable income. The Company accounts for uncertain tax positions in accordance with ASC 740. ASC 740 prescribes a recognition threshold and measurement attribute for the financial statement recognition and measurement of a tax provision that an entity takes or expects to take in a tax return. Additionally, ASC 740 provides guidance on derecognition, classification, interest and penalties, accounting in interim periods, disclosures, and transition. Under ASC 740, an entity may only recognize or continue to recognize tax positions that meet a "more likely than not" threshold. The provision for income taxes includes the effects of any resulting tax reserves, or unrecognized tax benefits, that are considered appropriate as well as the related net interest and penalties. Leases The Company determines whether the arrangement is or contains a lease at inception based on the unique facts and circumstances present in the arrangement, including the use of an identified asset or group of assets and the Company’s control over the use of that identified asset or group of assets. If determined to be or contain a lease, the lease is assessed for classification as either an operating or finance lease at the lease commencement date, defined as of the date on which the leased asset is made available for use by the Company, based on the economic characteristics of the lease. For each lease with a term greater than 12 months, the Company records a right-of-use asset and current and non-current lease liabilities. The Company’s leases of office space are classified as operating leases. In determining the appropriate lease classification, ASC 842 allows for the use of judgment in determining whether (i) the lease transfers ownership of the underlying asset to the Company, (ii) the lease grants an option for the Company to purchase the underlying asset, (iii) the assumed lease term is for a major part of the remaining economic life of the underlying asset or (iv) whether the present value of lease payments represents substantially all of the fair value of the underlying asset. Lease terms may include the impact of options to extend or terminate the lease when it is reasonably certain that the Company will exercise that option. The aforementioned factors are applied consistently to the Company’s entire portfolio of leases. A right-of-use asset represents the economic benefit conveyed to the Company by the right to use the underlying asset over the lease term. A lease liability represents the obligation to make lease payments arising from the lease. The Company elected to apply the package of practical expedients, which allows the Company to not reassess (i) whether existing or expired arrangements contain a
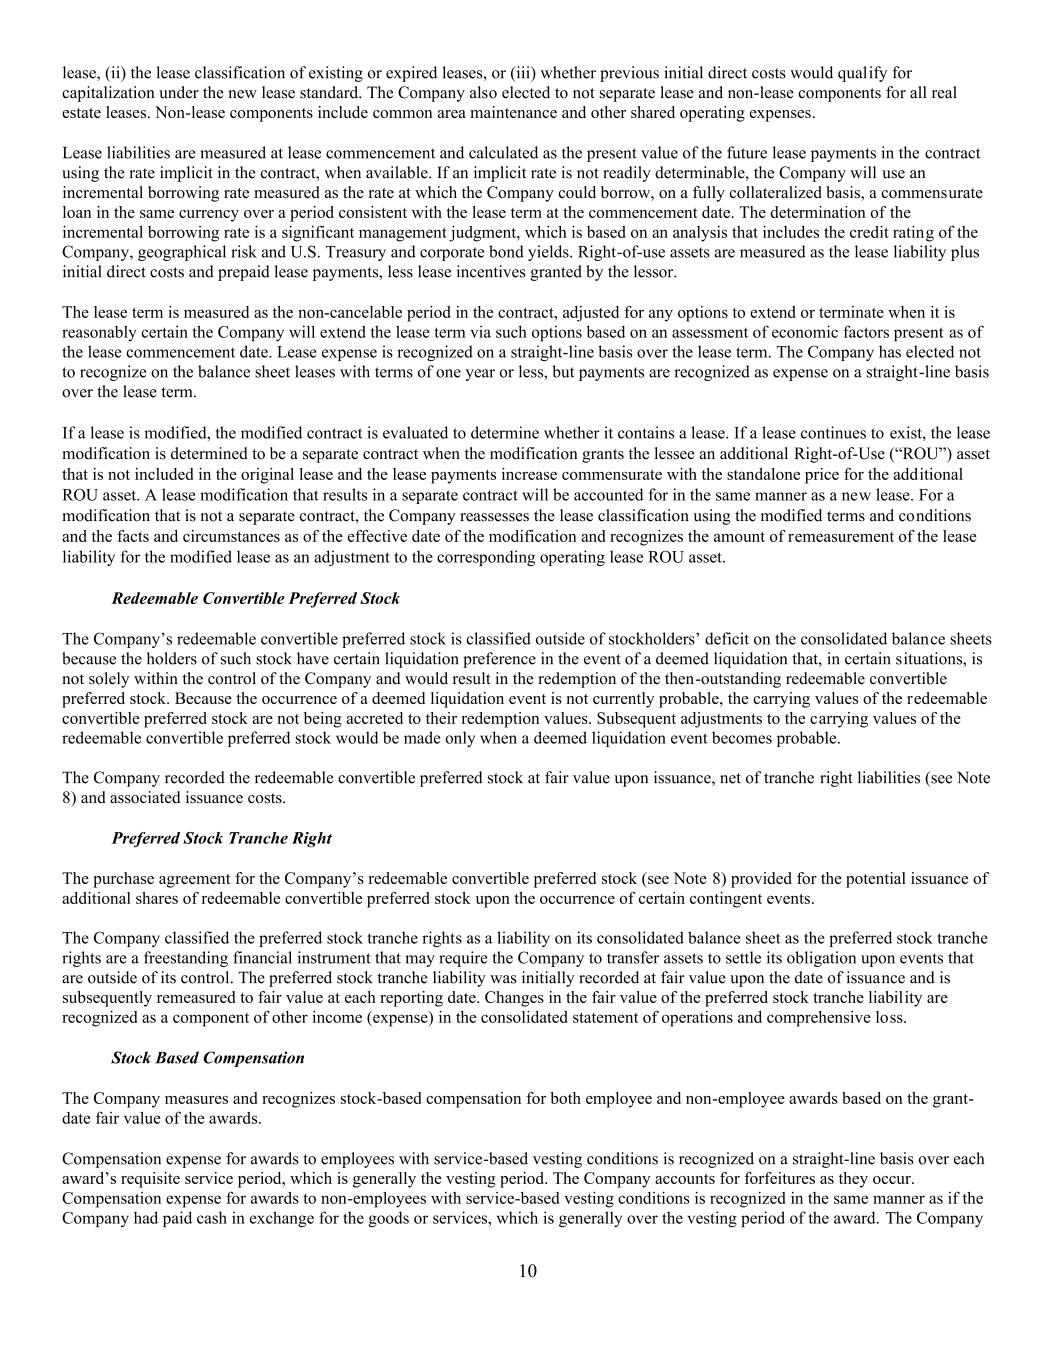
10 lease, (ii) the lease classification of existing or expired leases, or (iii) whether previous initial direct costs would qualify for capitalization under the new lease standard. The Company also elected to not separate lease and non-lease components for all real estate leases. Non-lease components include common area maintenance and other shared operating expenses. Lease liabilities are measured at lease commencement and calculated as the present value of the future lease payments in the contract using the rate implicit in the contract, when available. If an implicit rate is not readily determinable, the Company will use an incremental borrowing rate measured as the rate at which the Company could borrow, on a fully collateralized basis, a commensurate loan in the same currency over a period consistent with the lease term at the commencement date. The determination of the incremental borrowing rate is a significant management judgment, which is based on an analysis that includes the credit rating of the Company, geographical risk and U.S. Treasury and corporate bond yields. Right-of-use assets are measured as the lease liability plus initial direct costs and prepaid lease payments, less lease incentives granted by the lessor. The lease term is measured as the non-cancelable period in the contract, adjusted for any options to extend or terminate when it is reasonably certain the Company will extend the lease term via such options based on an assessment of economic factors present as of the lease commencement date. Lease expense is recognized on a straight-line basis over the lease term. The Company has elected not to recognize on the balance sheet leases with terms of one year or less, but payments are recognized as expense on a straight-line basis over the lease term. If a lease is modified, the modified contract is evaluated to determine whether it contains a lease. If a lease continues to exist, the lease modification is determined to be a separate contract when the modification grants the lessee an additional Right-of-Use (“ROU”) asset that is not included in the original lease and the lease payments increase commensurate with the standalone price for the additional ROU asset. A lease modification that results in a separate contract will be accounted for in the same manner as a new lease. For a modification that is not a separate contract, the Company reassesses the lease classification using the modified terms and conditions and the facts and circumstances as of the effective date of the modification and recognizes the amount of remeasurement of the lease liability for the modified lease as an adjustment to the corresponding operating lease ROU asset. Redeemable Convertible Preferred Stock The Company’s redeemable convertible preferred stock is classified outside of stockholders’ deficit on the consolidated balance sheets because the holders of such stock have certain liquidation preference in the event of a deemed liquidation that, in certain situations, is not solely within the control of the Company and would result in the redemption of the then-outstanding redeemable convertible preferred stock. Because the occurrence of a deemed liquidation event is not currently probable, the carrying values of the redeemable convertible preferred stock are not being accreted to their redemption values. Subsequent adjustments to the carrying values of the redeemable convertible preferred stock would be made only when a deemed liquidation event becomes probable. The Company recorded the redeemable convertible preferred stock at fair value upon issuance, net of tranche right liabilities (see Note 8) and associated issuance costs. Preferred Stock Tranche Right The purchase agreement for the Company’s redeemable convertible preferred stock (see Note 8) provided for the potential issuance of additional shares of redeemable convertible preferred stock upon the occurrence of certain contingent events. The Company classified the preferred stock tranche rights as a liability on its consolidated balance sheet as the preferred stock tranche rights are a freestanding financial instrument that may require the Company to transfer assets to settle its obligation upon events that are outside of its control. The preferred stock tranche liability was initially recorded at fair value upon the date of issuance and is subsequently remeasured to fair value at each reporting date. Changes in the fair value of the preferred stock tranche liability are recognized as a component of other income (expense) in the consolidated statement of operations and comprehensive loss. Stock Based Compensation The Company measures and recognizes stock-based compensation for both employee and non-employee awards based on the grant- date fair value of the awards. Compensation expense for awards to employees with service-based vesting conditions is recognized on a straight-line basis over each award’s requisite service period, which is generally the vesting period. The Company accounts for forfeitures as they occur. Compensation expense for awards to non-employees with service-based vesting conditions is recognized in the same manner as if the Company had paid cash in exchange for the goods or services, which is generally over the vesting period of the award. The Company
11 measures restricted common stock awards using the difference, if any, between the purchase price per share of the award and the fair value of the Company’s common stock at the date of grant. Compensation expense for awards with performance-based vesting conditions is recognized over the requisite service period to the extent the achievement of the related performance condition is estimated to be probable. At each reporting date, the Company evaluates whether any performance conditions related to a performance-based award have changed. The effect of any change in performance conditions is recognized as a cumulative catch-up adjustment in the period such change occurs. Any remaining unrecognized compensation expense would be recognized using the accelerated attribution method over the remaining requisite service period. The Company classifies stock-based compensation expense in its consolidated statements of operations in the same manner in which the award recipient’s payroll costs are classified or in which the award recipient’s service payments are classified. Determination of the Fair Value of Stock-Based Awards The Company estimates the fair value of stock options using the Black-Scholes option pricing model, which requires inputs of subjective assumptions, including: (i) the expected volatility of the Company’s common stock, (ii) the expected term of the award, (iii) the risk-free interest rate, (iv) expected dividends and (v) the fair value of the Company’s common stock. Due to the lack of a public market for the trading of the Company’s common stock and a lack of company-specific historical and implied volatility data, management bases the estimate of expected volatility on the historical volatilities of a representative group of publicly traded guideline companies. For these analyses, the Company selects companies with comparable characteristics and with historical share price information that approximates the expected term of the equity-based awards. The Company computes the historical volatility data using the daily closing prices for the selected companies’ shares during the equivalent period that approximates the calculated expected term of the Company’s stock options. The Company estimates the expected term of its stock options granted to employees and directors using the simplified method, whereby the expected term equals the average of the vesting term and the original contractual term of the option. The Company utilizes this method as it does not have sufficient historical exercise data to provide a reasonable basis upon which to estimate the expected term. The expected dividend yield is assumed to be zero as the Company has no current plans to pay any dividends on common stock. The Company has elected to use the expected term for stock options granted to non-employees, using the simplified method, as the basis for the expected term assumption. Determination of Fair Value of Common Stock on Grant Dates Given the absence of an active market for the Company’s common stock, the Board is required to determine the fair value of the Company’s common stock at the time of each grant of a stock-based award. In order to do so, the Company engages a third-party valuation specialist to estimate the fair value of its common stock in accordance with the framework of the American Institute of Certified Public Accountants’ Technical Practice Aid, Valuation of Privately-Held Company Equity Securities Issued as Compensation. In addition to this estimate, the Board considers a number of various objective and subjective factors in determining the fair value of the Company’s equity instruments as of each grant date. Research and Development The Company expenses all research and development costs as incurred. Included in research and development costs are wages, stock- based compensation and benefits of employees and other operational costs related to the Company’s research and development activities, including external costs of outside contractors engaged by the Company. Patents and Trademarks Costs associated with successful and pending applications of patents and trademarks have been charged to general and administrative expenses as incurred, as recoverability of such expenditures is uncertain. General and Administrative General and administrative expenses consist primarily of payroll and employee related costs, including stock-based compensation; professional fees for accounting, tax and legal services; consultant fees; information technology costs; depreciation and maintenance of property and equipment; and the allocated portion of rent and utilities, infrastructure, corporate insurance and office expenses.
12 Other Comprehensive Income (Loss) Comprehensive income (loss) is defined as the change in equity of a business enterprise during a period from transactions and other events and circumstances from non-owner sources, including foreign currency translation adjustments and unrealized gains and losses on marketable securities held as available for sale. For the years ended September 30, 2025, and 2024, there was no difference between the net loss and comprehensive loss. Government Grants Grants from the U.S. government are recognized where there is a reasonable assurance that the grant will be received, and the Company will comply with all attached conditions. The Company concluded that there is a reasonable assurance that the Company will comply with conditions attached to grants which have been recognized in the statement of operations. Government grants relating to cost reimbursements are deferred and recognized in the statements of operations and comprehensive loss over the period necessary to match them with the costs or economic losses that they are intended to compensate. Grant income recognized during the years ended September 30, 2025, and 2024 was $0.2 and $0.3 million respectively and are included in other income in the consolidated statements of operations and comprehensive loss. There were no deferred grants as of September 30, 2025, and 2024. Recently Adopted Accounting Pronouncements In December 2019, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2019- 12, Simplifying the Accounting for Income Taxes, which eliminates certain exceptions within ASC 740, Income Taxes, and clarifies certain aspects of the current guidance to promote consistency among reporting entities. ASU 2019-12 is effective for fiscal years beginning after December 15, 2020, for public entities and December 15, 2021, for nonpublic entities. Most amendments within the standard are required to be applied on a prospective basis, while certain amendments must be applied on a retrospective or modified retrospective basis. The Company adopted ASU 2019-12 effective October 1, 2022. The adoption of this guidance did not have a material impact on the Company’s financial statements and accompanying disclosures. In June 2016, the FASB issued ASU 2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments, (“ASU 2016-03”). Subsequent to the issuance of ASU 2016-13, ASC 326 was amended by various updates that amend and clarify the impact and implementation of ASU 2016-13. The new guidance introduces the current expected credit loss model, which will require an entity to record an allowance for credit losses for certain financial instruments and financial assets, including trade receivables, based on expected losses rather than incurred losses. Under this update, on initial recognition and at each reporting period, an entity will be required to recognize an allowance that reflects the entity’s current estimate of credit losses expected to be incurred over the life of the financial instrument. In November 2019, the FASB issued ASU 2019-10, Financial Instruments—Credit Losses (Topic 326), Derivatives and Hedging (Topic 815), and Leases (Topic 842): Effective Dates, which delays the effective date of ASU 2016-13 until fiscal years beginning after December 15, 2022, including interim periods within those fiscal years, for nonpublic companies. This ASU is effective for the Company beginning on October 1, 2023. The adoption of this guidance did not have a material impact on the Company’s financial statements and accompanying disclosures. Recently Issued Accounting Pronouncements From time to time, new accounting pronouncements are issued by the FASB or other standard setting bodies that are adopted by the Company as of the specified effective date. Unless otherwise discussed, the Company believes that the impact of recently issued standards that are not effective will not have a material impact on its financial position or results of operations upon adoption. In December 2023, the FASB issued ASU 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures. This ASU expands disclosures in an entity’s income tax rate reconciliation table and income taxes paid by jurisdiction. This update is effective for annual reporting periods beginning after December 15, 2024, with early adoption permitted. The Company is currently evaluating the impact of adopting ASU 2023-09 and does not expect a material impact. In December 2025, the FASB issued ASU 2025-10, Government Grants (Topic 832): Accounting for Government Grants Received by Business Entities. This ASU adds guidance on the recognition, measurement and presentation of government grants. This update is effective for fiscal years beginning after December 15, 2028, and permits modified prospective, modified retrospective, or full retrospective adoption. The Company is currently evaluating the impact of adopting ASU 2025-10 and does not expect a material impact.
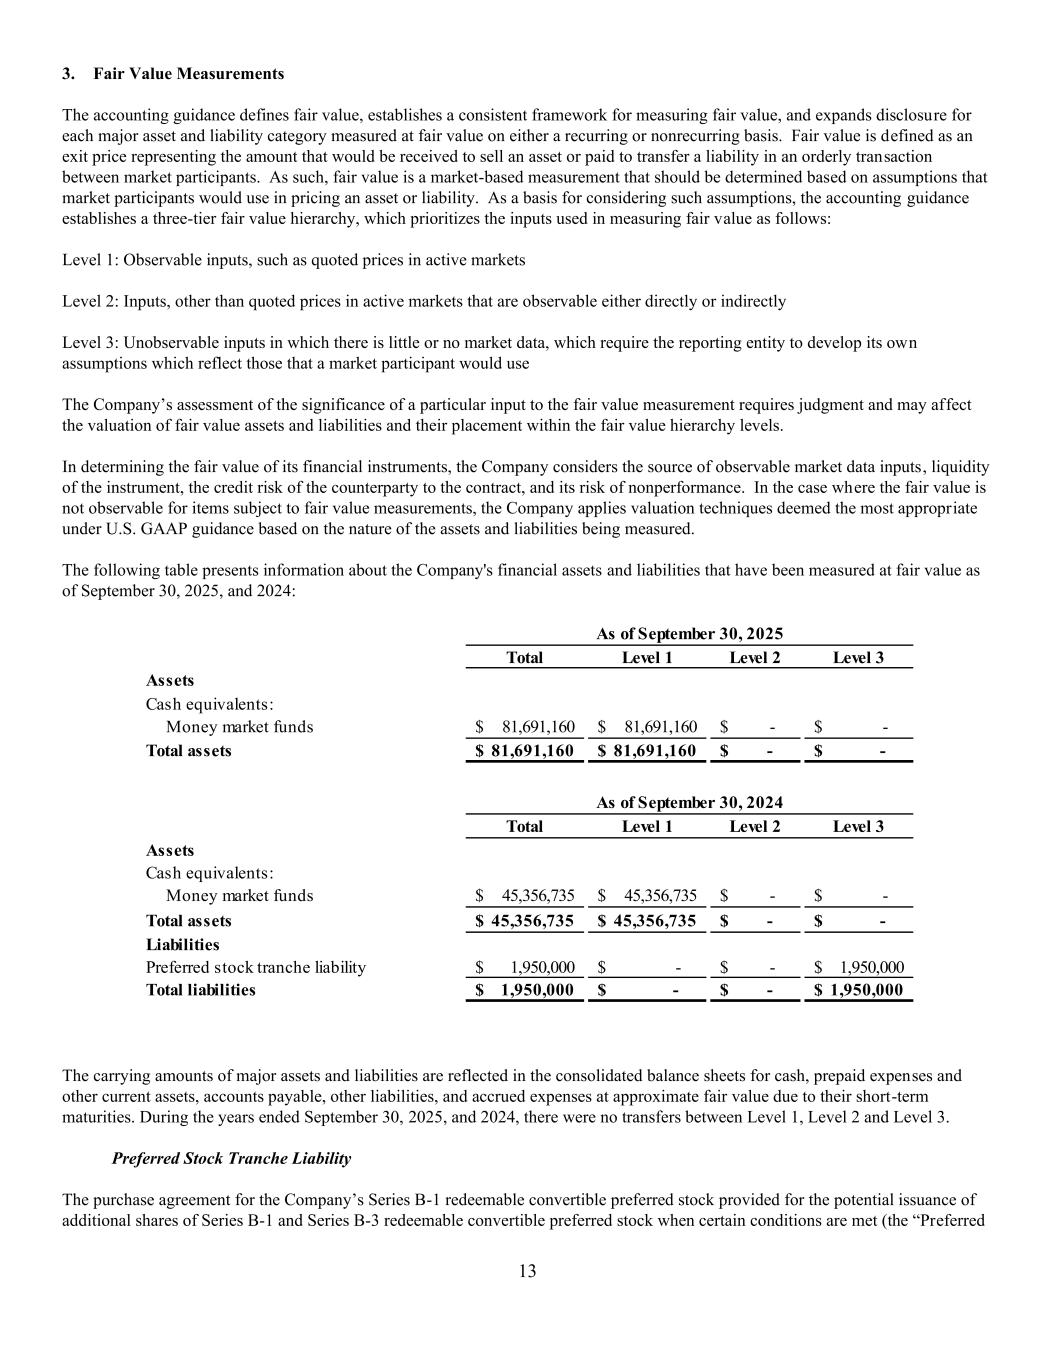
13 3. Fair Value Measurements The accounting guidance defines fair value, establishes a consistent framework for measuring fair value, and expands disclosure for each major asset and liability category measured at fair value on either a recurring or nonrecurring basis. Fair value is defined as an exit price representing the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants. As such, fair value is a market-based measurement that should be determined based on assumptions that market participants would use in pricing an asset or liability. As a basis for considering such assumptions, the accounting guidance establishes a three-tier fair value hierarchy, which prioritizes the inputs used in measuring fair value as follows: Level 1: Observable inputs, such as quoted prices in active markets Level 2: Inputs, other than quoted prices in active markets that are observable either directly or indirectly Level 3: Unobservable inputs in which there is little or no market data, which require the reporting entity to develop its own assumptions which reflect those that a market participant would use The Company’s assessment of the significance of a particular input to the fair value measurement requires judgment and may affect the valuation of fair value assets and liabilities and their placement within the fair value hierarchy levels. In determining the fair value of its financial instruments, the Company considers the source of observable market data inputs, liquidity of the instrument, the credit risk of the counterparty to the contract, and its risk of nonperformance. In the case where the fair value is not observable for items subject to fair value measurements, the Company applies valuation techniques deemed the most appropriate under U.S. GAAP guidance based on the nature of the assets and liabilities being measured. The following table presents information about the Company's financial assets and liabilities that have been measured at fair value as of September 30, 2025, and 2024: Total Level 1 Level 2 Level 3 Assets Cash equivalents: Money market funds 81,691,160$ 81,691,160$ -$ -$ Total assets 81,691,160$ 81,691,160$ -$ -$ Total Level 1 Level 2 Level 3 Assets Cash equivalents: Money market funds 45,356,735$ 45,356,735$ -$ -$ Total assets 45,356,735$ 45,356,735$ -$ -$ Liabilities Preferred stock tranche liability 1,950,000$ -$ -$ 1,950,000$ Total liabilities 1,950,000$ -$ -$ 1,950,000$ As of September 30, 2024 As of September 30, 2025 The carrying amounts of major assets and liabilities are reflected in the consolidated balance sheets for cash, prepaid expenses and other current assets, accounts payable, other liabilities, and accrued expenses at approximate fair value due to their short-term maturities. During the years ended September 30, 2025, and 2024, there were no transfers between Level 1, Level 2 and Level 3. Preferred Stock Tranche Liability The purchase agreement for the Company’s Series B-1 redeemable convertible preferred stock provided for the potential issuance of additional shares of Series B-1 and Series B-3 redeemable convertible preferred stock when certain conditions are met (the “Preferred
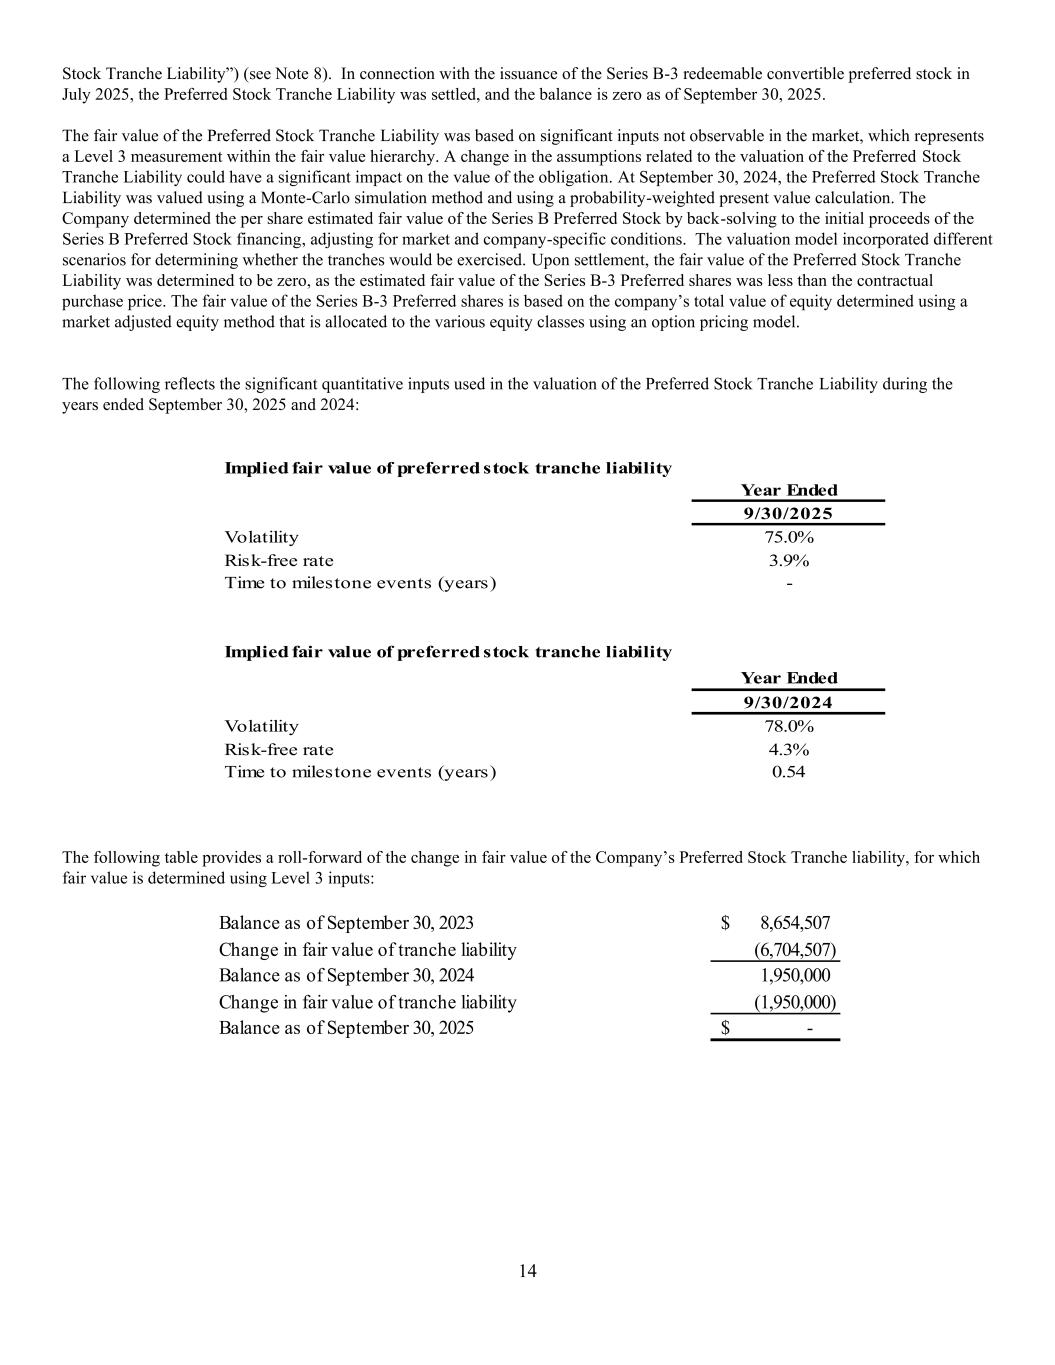
14 Stock Tranche Liability”) (see Note 8). In connection with the issuance of the Series B-3 redeemable convertible preferred stock in July 2025, the Preferred Stock Tranche Liability was settled, and the balance is zero as of September 30, 2025. The fair value of the Preferred Stock Tranche Liability was based on significant inputs not observable in the market, which represents a Level 3 measurement within the fair value hierarchy. A change in the assumptions related to the valuation of the Preferred Stock Tranche Liability could have a significant impact on the value of the obligation. At September 30, 2024, the Preferred Stock Tranche Liability was valued using a Monte-Carlo simulation method and using a probability-weighted present value calculation. The Company determined the per share estimated fair value of the Series B Preferred Stock by back-solving to the initial proceeds of the Series B Preferred Stock financing, adjusting for market and company-specific conditions. The valuation model incorporated different scenarios for determining whether the tranches would be exercised. Upon settlement, the fair value of the Preferred Stock Tranche Liability was determined to be zero, as the estimated fair value of the Series B-3 Preferred shares was less than the contractual purchase price. The fair value of the Series B-3 Preferred shares is based on the company’s total value of equity determined using a market adjusted equity method that is allocated to the various equity classes using an option pricing model. The following reflects the significant quantitative inputs used in the valuation of the Preferred Stock Tranche Liability during the years ended September 30, 2025 and 2024: Implied fair value of preferred stock tranche liability Year Ended 9/30/2025 Volatility 75.0% Risk-free rate 3.9% Time to milestone events (years) - Implied fair value of preferred stock tranche liability Year Ended 9/30/2024 Volatility 78.0% Risk-free rate 4.3% Time to milestone events (years) 0.54 The following table provides a roll-forward of the change in fair value of the Company’s Preferred Stock Tranche liability, for which fair value is determined using Level 3 inputs: Balance as of September 30, 2023 8,654,507$ Change in fair value of tranche liability (6,704,507) Balance as of September 30, 2024 1,950,000 Change in fair value of tranche liability (1,950,000) Balance as of September 30, 2025 -$
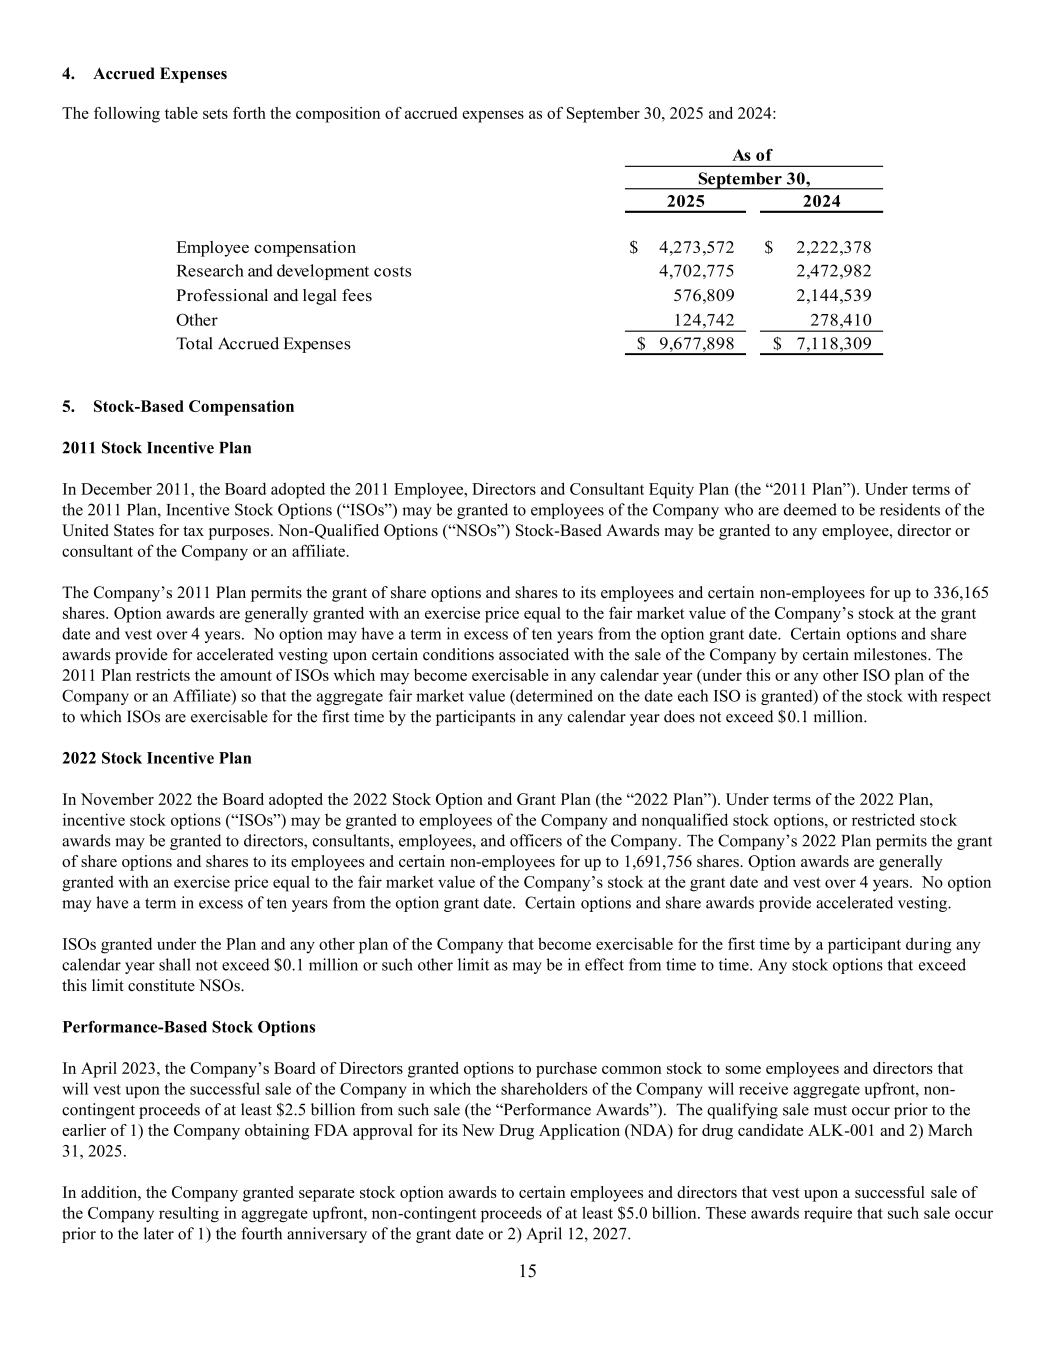
15 4. Accrued Expenses The following table sets forth the composition of accrued expenses as of September 30, 2025 and 2024: As of 2025 2024 Employee compensation 4,273,572$ 2,222,378$ Research and development costs 4,702,775 2,472,982 Professional and legal fees 576,809 2,144,539 Other 124,742 278,410 Total Accrued Expenses 9,677,898$ 7,118,309$ September 30, 5. Stock-Based Compensation 2011 Stock Incentive Plan In December 2011, the Board adopted the 2011 Employee, Directors and Consultant Equity Plan (the “2011 Plan”). Under terms of the 2011 Plan, Incentive Stock Options (“ISOs”) may be granted to employees of the Company who are deemed to be residents of the United States for tax purposes. Non-Qualified Options (“NSOs”) Stock-Based Awards may be granted to any employee, director or consultant of the Company or an affiliate. The Company’s 2011 Plan permits the grant of share options and shares to its employees and certain non-employees for up to 336,165 shares. Option awards are generally granted with an exercise price equal to the fair market value of the Company’s stock at the grant date and vest over 4 years. No option may have a term in excess of ten years from the option grant date. Certain options and share awards provide for accelerated vesting upon certain conditions associated with the sale of the Company by certain milestones. The 2011 Plan restricts the amount of ISOs which may become exercisable in any calendar year (under this or any other ISO plan of the Company or an Affiliate) so that the aggregate fair market value (determined on the date each ISO is granted) of the stock with respect to which ISOs are exercisable for the first time by the participants in any calendar year does not exceed $0.1 million. 2022 Stock Incentive Plan In November 2022 the Board adopted the 2022 Stock Option and Grant Plan (the “2022 Plan”). Under terms of the 2022 Plan, incentive stock options (“ISOs”) may be granted to employees of the Company and nonqualified stock options, or restricted stock awards may be granted to directors, consultants, employees, and officers of the Company. The Company’s 2022 Plan permits the grant of share options and shares to its employees and certain non-employees for up to 1,691,756 shares. Option awards are generally granted with an exercise price equal to the fair market value of the Company’s stock at the grant date and vest over 4 years. No option may have a term in excess of ten years from the option grant date. Certain options and share awards provide accelerated vesting. ISOs granted under the Plan and any other plan of the Company that become exercisable for the first time by a participant during any calendar year shall not exceed $0.1 million or such other limit as may be in effect from time to time. Any stock options that exceed this limit constitute NSOs. Performance-Based Stock Options In April 2023, the Company’s Board of Directors granted options to purchase common stock to some employees and directors that will vest upon the successful sale of the Company in which the shareholders of the Company will receive aggregate upfront, non- contingent proceeds of at least $2.5 billion from such sale (the “Performance Awards”). The qualifying sale must occur prior to the earlier of 1) the Company obtaining FDA approval for its New Drug Application (NDA) for drug candidate ALK-001 and 2) March 31, 2025. In addition, the Company granted separate stock option awards to certain employees and directors that vest upon a successful sale of the Company resulting in aggregate upfront, non-contingent proceeds of at least $5.0 billion. These awards require that such sale occur prior to the later of 1) the fourth anniversary of the grant date or 2) April 12, 2027.
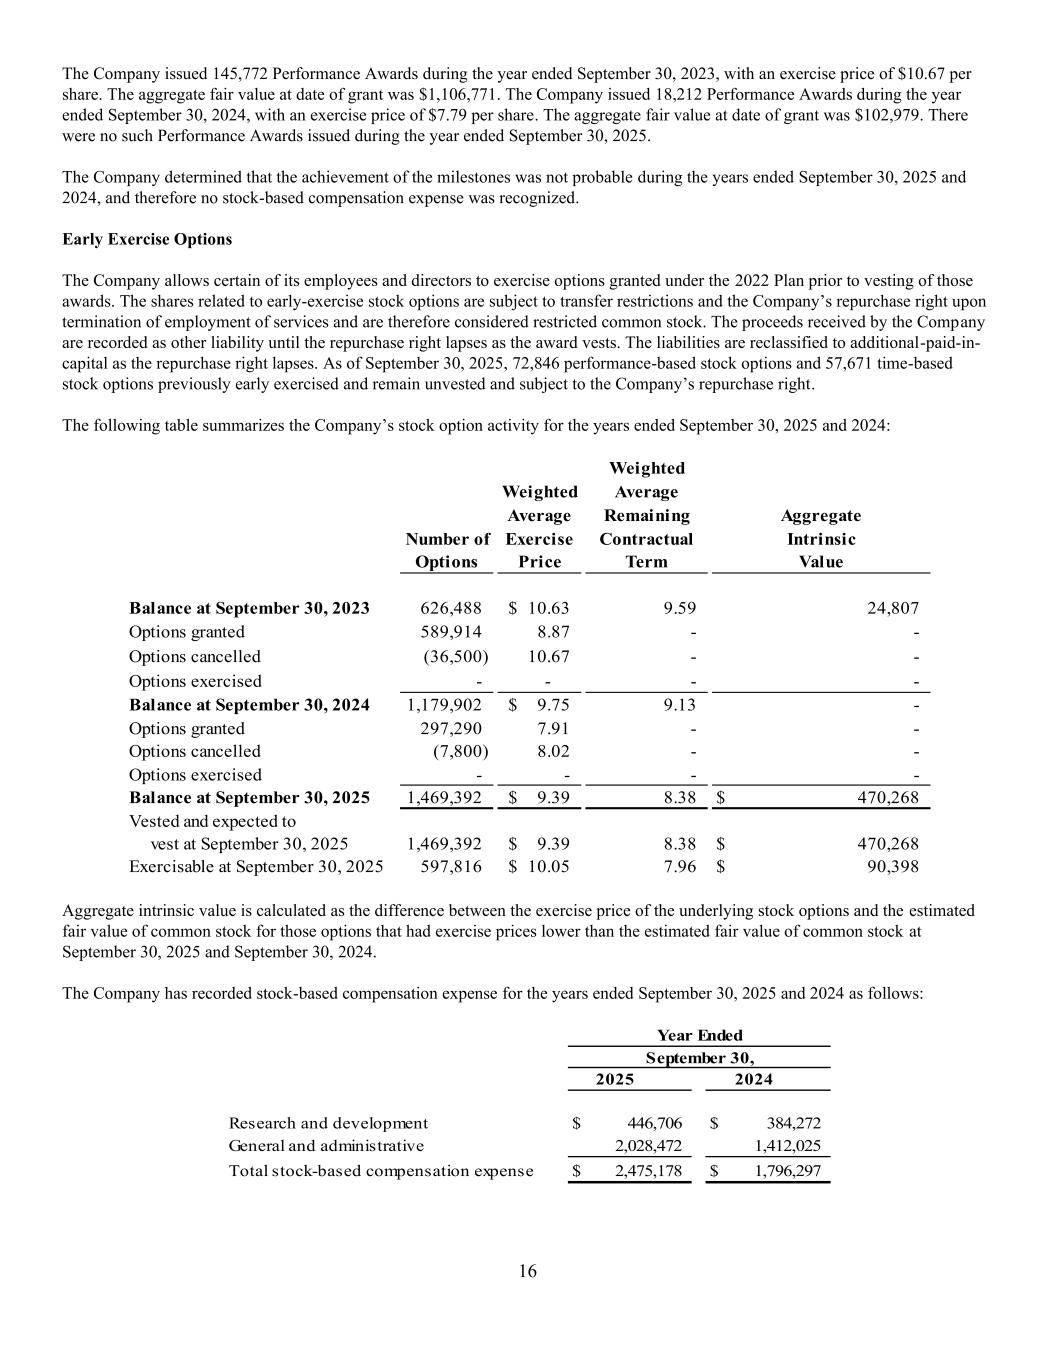
16 The Company issued 145,772 Performance Awards during the year ended September 30, 2023, with an exercise price of $10.67 per share. The aggregate fair value at date of grant was $1,106,771. The Company issued 18,212 Performance Awards during the year ended September 30, 2024, with an exercise price of $7.79 per share. The aggregate fair value at date of grant was $102,979. There were no such Performance Awards issued during the year ended September 30, 2025. The Company determined that the achievement of the milestones was not probable during the years ended September 30, 2025 and 2024, and therefore no stock-based compensation expense was recognized. Early Exercise Options The Company allows certain of its employees and directors to exercise options granted under the 2022 Plan prior to vesting of those awards. The shares related to early-exercise stock options are subject to transfer restrictions and the Company’s repurchase right upon termination of employment of services and are therefore considered restricted common stock. The proceeds received by the Company are recorded as other liability until the repurchase right lapses as the award vests. The liabilities are reclassified to additional-paid-in- capital as the repurchase right lapses. As of September 30, 2025, 72,846 performance-based stock options and 57,671 time-based stock options previously early exercised and remain unvested and subject to the Company’s repurchase right. The following table summarizes the Company’s stock option activity for the years ended September 30, 2025 and 2024: Weighted Weighted Average Average Remaining Aggregate Number of Exercise Contractual Intrinsic Options Price Term Value Balance at September 30, 2023 626,488 10.63$ 9.59 24,807 Options granted 589,914 8.87 - - Options cancelled (36,500) 10.67 - - Options exercised - - - - Balance at September 30, 2024 1,179,902 9.75$ 9.13 - Options granted 297,290 7.91 - - Options cancelled (7,800) 8.02 - - Options exercised - - - - Balance at September 30, 2025 1,469,392 9.39$ 8.38 470,268$ Vested and expected to vest at September 30, 2025 1,469,392 9.39$ 8.38 470,268$ Exercisable at September 30, 2025 597,816 10.05$ 7.96 90,398$ Aggregate intrinsic value is calculated as the difference between the exercise price of the underlying stock options and the estimated fair value of common stock for those options that had exercise prices lower than the estimated fair value of common stock at September 30, 2025 and September 30, 2024. The Company has recorded stock-based compensation expense for the years ended September 30, 2025 and 2024 as follows: 2025 2024 Research and development 446,706$ 384,272$ General and administrative 2,028,472 1,412,025 Total stock-based compensation expense 2,475,178$ 1,796,297$ Year Ended September 30,
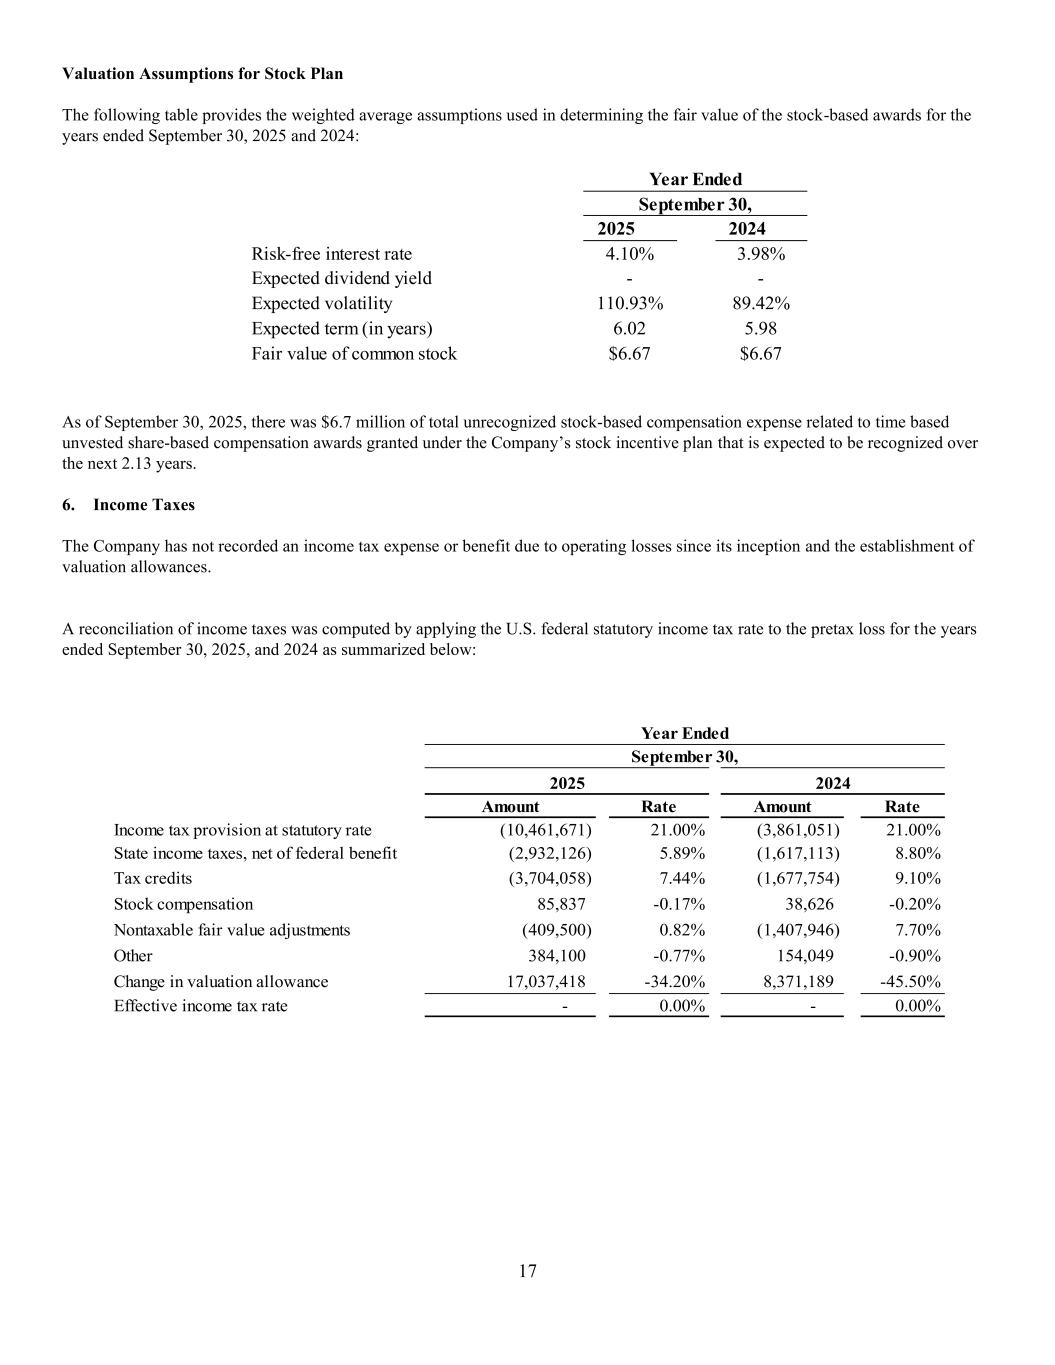
17 Valuation Assumptions for Stock Plan The following table provides the weighted average assumptions used in determining the fair value of the stock-based awards for the years ended September 30, 2025 and 2024: 2025 2024 Risk-free interest rate 4.10% 3.98% Expected dividend yield - - Expected volatility 110.93% 89.42% Expected term (in years) 6.02 5.98 Fair value of common stock $6.67 $6.67 Year Ended September 30, As of September 30, 2025, there was $6.7 million of total unrecognized stock-based compensation expense related to time based unvested share-based compensation awards granted under the Company’s stock incentive plan that is expected to be recognized over the next 2.13 years. 6. Income Taxes The Company has not recorded an income tax expense or benefit due to operating losses since its inception and the establishment of valuation allowances. A reconciliation of income taxes was computed by applying the U.S. federal statutory income tax rate to the pretax loss for the years ended September 30, 2025, and 2024 as summarized below: Amount Rate Amount Rate Income tax provision at statutory rate (10,461,671) 21.00% (3,861,051) 21.00% State income taxes, net of federal benefit (2,932,126) 5.89% (1,617,113) 8.80% Tax credits (3,704,058) 7.44% (1,677,754) 9.10% Stock compensation 85,837 -0.17% 38,626 -0.20% Nontaxable fair value adjustments (409,500) 0.82% (1,407,946) 7.70% Other 384,100 -0.77% 154,049 -0.90% Change in valuation allowance 17,037,418 -34.20% 8,371,189 -45.50% Effective income tax rate - 0.00% - 0.00% 20242025 Year Ended September 30,
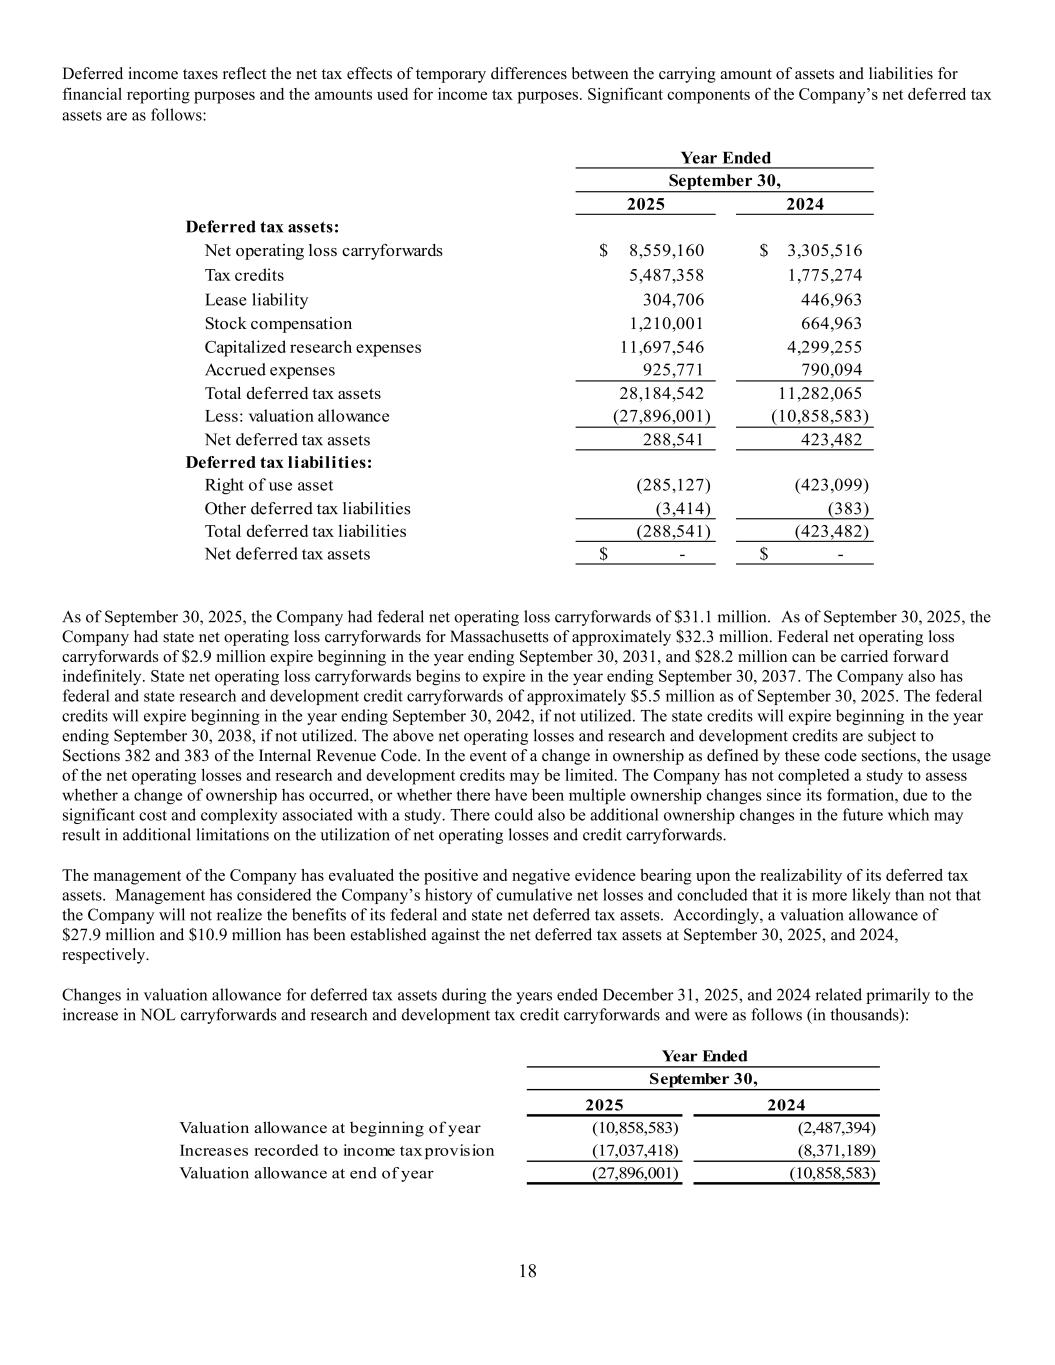
18 Deferred income taxes reflect the net tax effects of temporary differences between the carrying amount of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes. Significant components of the Company’s net deferred tax assets are as follows: Year Ended 2025 2024 Deferred tax assets: Net operating loss carryforwards 8,559,160$ 3,305,516$ Tax credits 5,487,358 1,775,274 Lease liability 304,706 446,963 Stock compensation 1,210,001 664,963 Capitalized research expenses 11,697,546 4,299,255 Accrued expenses 925,771 790,094 Total deferred tax assets 28,184,542 11,282,065 Less: valuation allowance (27,896,001) (10,858,583) Net deferred tax assets 288,541 423,482 Deferred tax liabilities: Right of use asset (285,127) (423,099) Other deferred tax liabilities (3,414) (383) Total deferred tax liabilities (288,541) (423,482) Net deferred tax assets -$ -$ September 30, As of September 30, 2025, the Company had federal net operating loss carryforwards of $31.1 million. As of September 30, 2025, the Company had state net operating loss carryforwards for Massachusetts of approximately $32.3 million. Federal net operating loss carryforwards of $2.9 million expire beginning in the year ending September 30, 2031, and $28.2 million can be carried forward indefinitely. State net operating loss carryforwards begins to expire in the year ending September 30, 2037. The Company also has federal and state research and development credit carryforwards of approximately $5.5 million as of September 30, 2025. The federal credits will expire beginning in the year ending September 30, 2042, if not utilized. The state credits will expire beginning in the year ending September 30, 2038, if not utilized. The above net operating losses and research and development credits are subject to Sections 382 and 383 of the Internal Revenue Code. In the event of a change in ownership as defined by these code sections, the usage of the net operating losses and research and development credits may be limited. The Company has not completed a study to assess whether a change of ownership has occurred, or whether there have been multiple ownership changes since its formation, due to the significant cost and complexity associated with a study. There could also be additional ownership changes in the future which may result in additional limitations on the utilization of net operating losses and credit carryforwards. The management of the Company has evaluated the positive and negative evidence bearing upon the realizability of its deferred tax assets. Management has considered the Company’s history of cumulative net losses and concluded that it is more likely than not that the Company will not realize the benefits of its federal and state net deferred tax assets. Accordingly, a valuation allowance of $27.9 million and $10.9 million has been established against the net deferred tax assets at September 30, 2025, and 2024, respectively. Changes in valuation allowance for deferred tax assets during the years ended December 31, 2025, and 2024 related primarily to the increase in NOL carryforwards and research and development tax credit carryforwards and were as follows (in thousands): 2025 2024 Valuation allowance at beginning of year (10,858,583) (2,487,394) Increases recorded to income tax provision (17,037,418) (8,371,189) Valuation allowance at end of year (27,896,001) (10,858,583) Year Ended September 30,
19 On July 4, 2025, the One Big Beautiful Bill Act (“OBBBA”) was enacted in the United States. The OBBBA includes significant provisions, such as the permanent extension of certain expiring provisions of the Tax Cuts and Jobs Act, modification to the international tax framework, and the restoration of favorable tax treatment for certain business provisions. The legislation has multiple effective dates, with certain provisions effective in 2025 and others implemented through 2027. The majority of these provisions are not in effect for the year ended September 30, 2025. These changes, to the extent applicable in the current year, are reflected in our results for the year ended September 30, 2025 and did not have a material impact. As of September 30, 2025, and 2024, the Company had not recorded any amounts for unrecognized tax benefits. The Company’s policy is to record interest and penalties related to income taxes as part of its income tax provision. As of September 30, 2025, and 2024, the Company had no accrued interest or penalties related to uncertain tax positions in the consolidated statements of operations and comprehensive loss. The Company files income tax returns in the U.S. federal and various state jurisdictions, as prescribed by tax laws. In the normal course of business, the Company is subject to examination by federal and state jurisdictions, where applicable. The statute of limitations for federal and state tax authorities is generally closed for years ending September 30, 2021, and prior, although carryforward attributes that were generated prior to this tax period may still be subject to change upon examination if they are utilized to offset taxable income in subsequent tax years. There are currently no federal or state income tax audits in progress. 7. Common Stock The Second Amended and Restated Certificate of Incorporation of Alkeus Pharmaceuticals, Inc. as certified on April 28, 2023 (the “Charter”) authorizes the Company to issue 10,815,595 shares of $0.0001 par value common stock. Each share of common stock entitles the stockholder to one vote on all matters submitted to a vote of the Company's stockholders. Common stockholders are entitled to receive dividends, as may be declared by the board of directors, if any, subject to the preferential dividend rights of the convertible preferred stock. When dividends are declared on shares of common stock, the Company must declare at the same time a dividend payable to the holders convertible preferred stock equivalent to the dividend amount they would receive if each preferred share were converted into common stock. As of September 30, 2025, and 2024, no dividends had been declared. As of September 30, 2025, and 2024 and per the Company Charter, the Company had reserved sufficient shares of common stock for the conversion of the Series A, Series B-1, Series B-2 and Series B-3 convertible preferred stock (see Note 8) and the exercise of outstanding stock options (see Note 5). 8. Redeemable Convertible Preferred Stock The Company has issued Series A redeemable convertible preferred stock ("Series A Preferred Stock") and Series B-1, B-2 and B-3 redeemable convertible preferred stock ("Series B Preferred Stock"), together, "Preferred Stock”. In 2011, the Company issued 369,591 shares of Series A Preferred Stock at an original issue price of $5.67 per share for total cash proceeds of $2.1 million. In November 2022 the Company issued 1,618,809 shares of Series B-1 Preferred Stock in an initial closing at $30.89 per share for total gross proceeds of approximately $50 million less issuance costs of approximately $0.4 million. In April 2023, the Company issued 809,404 shares of Series B-1 Preferred Stock in a subsequent initial closing at $30.89 per share for total gross proceeds of approximately $25 million. Additionally, in November 2022, the Company issued 103,466 shares of Series B-2 Preferred Stock in exchange for the convertible promissory notes which were recorded at their fair value of $3.2 million. Pursuant to the terms of the Series B Preferred Stock Purchase Agreement (the “Purchase Agreement”), due to the non-occurrence of the First Tranche Expansion prior to June 30, 2024, effective July 1, 2024, 63,939 shares of Series B-1 Preferred Stock and 2,725 shares of Series B-2 Preferred Stock were forfeited by investors to the Company. These share forfeitures resulted in an adjustment to the Series B-1 Preferred Stock original issue price per share from $30.89 to $31.7222 and the Series B-2 Preferred Stock price per share from $23.1652 to $23.79. On April 11, 2025, the Company and the Holders of the Series B Preferred Stock entered into an amendment to the Purchase Agreement (the “Amended Purchase Agreement”) which extended the timing and adjusted the criteria of the closing of the 2nd tranche period.
20 On July 7, 2025, the Company issued 2,482,488 shares of Series B-3 Preferred Stock to stockholders in accordance with the Amended Purchase Agreement at $30.21 per share for total gross proceeds of $75.0 million, which represented the remaining funding under the Purchase Agreement. The $10.7 million of proceeds received in excess of the fair value of the Series B-3 Preferred Stock was recorded as additional paid-in capital. As part of the issuance of the Series B-3 Preferred Stock, the Preferred Stock Tranche Liability was settled (see Note 3). The Series B Preferred Stock Purchase Agreement included certain obligations to issue Series B-1 and Series B-3 Preferred Stock, including: - The First Tranche Expansion: The Company can require investors to purchase up to $25.0 million on a pro rata basis within 14 days of US or EU regulatory acceptance of the Company's new drug application if the acceptance occurs before June 30, 2024. The First Tranche Expansion would consist of an additional 809,404 Series B-1 shares issued at an original issue price of $30.89 per share. - The Second Tranche: Investors have the option to purchase, and the Company is required to sell up to $75.0 million Series B-3 shares, less any dollars funded in the First Tranche Expansion. The Second Tranche commences on the earliest of (a) FDA Approval, (b) EMA Approval, (c) the unanimous Board consent that neither FDA Approval nor EMA Approval will occur before the Approval By Date, or (d) one day after the Approval By Date and ends on the earlier of (a) April 15, 2025, or (b) the consummation of an Alternative Financing. The “Approval By Date” is March 31, 2025, subject to extension if the FDA originally notifies the Company of a PDUFA (Prescription Drug User Fee Act) date on or prior to March 31, 2025, and if the FDA needs to postpone that date due to certain conditions. o Prior to either FDA or EMA approval, the Second Tranche would consist of (a) 2,482,490 Series B-3 shares at $30.2116 per share in the event there shall not have been a First Tranche Expansion closing or (b) 1,666,422 Series B shares at $30.0044 per share in the event there shall have been a First Tranche Expansion closing. o Subsequent to EMA Approval and prior to FDA Approval, the Second Tranche would consist of (a) 1,797,496 Series B-3 shares at $41.7247 per share in the event there shall not have been a First Tranche Expansion closing or (b) 1,202,871 Series B-3 shares at $41.5672 per share in the event there shall have been a First Tranche Expansion closing. o Subsequent to FDA Approval, the Second Tranche shares purchase price shall be (a) 549,257 Series B-3 shares at $136.5479 per share in the event there shall not have been a First Tranche Expansion closing and (b) 389,997 Series B-3 shares at $128.2060 per share in the event there shall have been a First Tranche Expansion closing. The Company initially recorded the Preferred Stock Tranche Liability at fair value of $12.7 million in April 2023. Changes in the fair value of the Preferred Stock Tranche Liability are recognized as a component of other income (expense) in the consolidated statement of operations and comprehensive loss. During the year ended September 30, 2024, the Company recorded $6.7 million for the remeasurement to fair value at the end of the reporting period. During the year ended September 30, 2025, the Company recorded $1.95 million as part of the settlement of the tranche liability in connection with the issuance of the Series B-3 Preferred Stock.
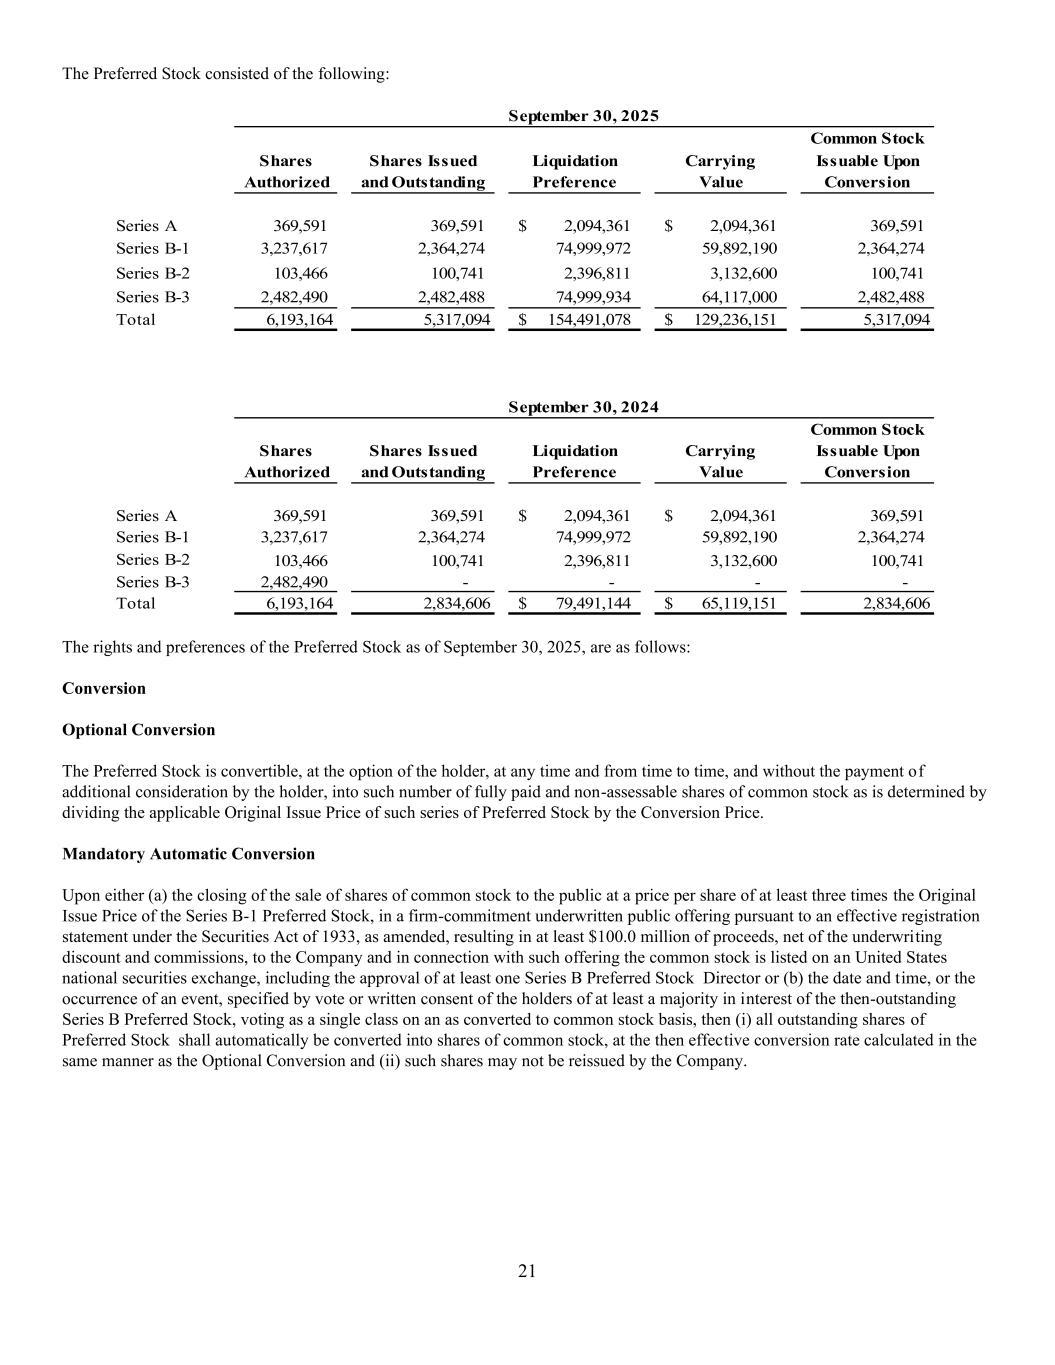
21 The Preferred Stock consisted of the following: Common Stock Shares Shares Issued Liquidation Carrying Issuable Upon Authorized and Outstanding Preference Value Conversion Series A 369,591 369,591 2,094,361$ 2,094,361$ 369,591 Series B-1 3,237,617 2,364,274 74,999,972 59,892,190 2,364,274 Series B-2 103,466 100,741 2,396,811 3,132,600 100,741 Series B-3 2,482,490 2,482,488 74,999,934 64,117,000 2,482,488 Total 6,193,164 5,317,094 154,491,078$ 129,236,151$ 5,317,094 Common Stock Shares Shares Issued Liquidation Carrying Issuable Upon Authorized and Outstanding Preference Value Conversion Series A 369,591 369,591 2,094,361$ 2,094,361$ 369,591 Series B-1 3,237,617 2,364,274 74,999,972 59,892,190 2,364,274 Series B-2 103,466 100,741 2,396,811 3,132,600 100,741 Series B-3 2,482,490 - - - - Total 6,193,164 2,834,606 79,491,144$ 65,119,151$ 2,834,606 September 30, 2024 September 30, 2025 The rights and preferences of the Preferred Stock as of September 30, 2025, are as follows: Conversion Optional Conversion The Preferred Stock is convertible, at the option of the holder, at any time and from time to time, and without the payment of additional consideration by the holder, into such number of fully paid and non-assessable shares of common stock as is determined by dividing the applicable Original Issue Price of such series of Preferred Stock by the Conversion Price. Mandatory Automatic Conversion Upon either (a) the closing of the sale of shares of common stock to the public at a price per share of at least three times the Original Issue Price of the Series B-1 Preferred Stock, in a firm-commitment underwritten public offering pursuant to an effective registration statement under the Securities Act of 1933, as amended, resulting in at least $100.0 million of proceeds, net of the underwriting discount and commissions, to the Company and in connection with such offering the common stock is listed on an United States national securities exchange, including the approval of at least one Series B Preferred Stock Director or (b) the date and time, or the occurrence of an event, specified by vote or written consent of the holders of at least a majority in interest of the then-outstanding Series B Preferred Stock, voting as a single class on an as converted to common stock basis, then (i) all outstanding shares of Preferred Stock shall automatically be converted into shares of common stock, at the then effective conversion rate calculated in the same manner as the Optional Conversion and (ii) such shares may not be reissued by the Company.
22 Conversion Price The Conversion Price is initially equal to the Original Issue Price of the respective series of Preferred Stock. The Conversion Price is subject to adjustment in the event of any down-round, stock dividend, stock split, combination or other similar recapitalization. Upon the occurrence of certain regulatory approvals or in the event the First Tranche Expansion does not occur, holders of Series B Preferred Stock are required to forfeit a specified number of shares of Preferred Stock depending on which event occurred. Upon such forfeiture, the Original Issue Price and corresponding Conversion Price would be adjusted to preserve the liquidation preference of such shares. Dividend Rights Series B Preferred Stock is entitled to receive, only when, as and if declared by the Board of Directors non-cumulative dividends at the rate of 6.0% of the respective original issue price (the “Series B Dividend”). The Company shall not declare, pay or set aside any dividends on common shares of the Company unless the holders of Preferred Stock then outstanding shall first receive, or simultaneously receive, in addition to the Series B Dividend, a dividend on each outstanding share of Preferred Stock in an amount at least equal to the product of (1) the dividend payable on each share of such class or series determined, as if all shares of such class or series had been converted into common stock and (2) the number of shares of common stock issuable upon conversion of a share of such series of Preferred Stock, in each case calculated on the record date for determination of the holders entitled to receive such dividend. As of September 30, 2025, and 2024, no cash dividends have been declared or paid. Liquidation Preference In the event of any voluntary or involuntary liquidation, dissolution, or winding up of the Company, or Deemed Liquidation Event (defined below), the holders of Series B Preferred Stock are entitled to be paid an amount equal to the greater of (i) the original issuance price plus the amount of all declared but unpaid dividends on each such share or (ii) such amount per share as would have been payable had all shares of Series B Preferred Stock been converted into common stock. In the event that the assets and funds legally available for distribution to the stockholders are insufficient to pay the holders of shares of Series B Preferred Stock the full Series B preference amounts to which the holders shall be entitled, the holders of Series B Preferred Stock shall share ratably in any distribution of the assets and funds of the Company in proportion to the respective amounts that would otherwise be payable in respect of such shares held by them upon such distribution if all amounts payable on or with respect to such shares were paid in full. After the payment of all preferential amounts required to be paid to the holders of Series B Preferred Stock, the holders of Series A Preferred Stock are entitled to be paid an amount equal to the greater of (i) the original issuance price plus the amount of all declared but unpaid dividends on each such share or (ii) such amount per share as would have been payable had all shares of Series A Preferred Stock been converted into common stock. In the event that the assets and funds legally available for distribution to the stockholders are insufficient to pay the holders of shares of Series A Preferred Stock the full Series A preference amounts to which the holders shall be entitled, the holders of Series A Preferred Stock shall share ratably in any distribution of the assets and funds of the Company in proportion to the respective amounts that would otherwise be payable in respect of such shares held by them upon such distribution if all amounts payable on or with respect to such shares were paid in full. After the payment in full of the Preferred Stock preference amount, the remaining assets of the Company available for distribution to stockholders shall be distributed among the holders of common stock on a pro-rata basis. Each of the following events shall be considered a Deemed Liquidation Event (“Deemed Liquidation Event”) unless the holders of a majority of the then outstanding shares of Preferred Stock, voting together as a single class on an as converted to common stock basis elect otherwise, a merger, consolidation, or share exchange (other than one in which stockholders of the Company own a majority by voting power of the outstanding shares of the surviving or acquiring corporation) or a sale, lease, transfer, exclusive license or other disposition of all or substantially all of the assets of the Company, or transaction resulting in the issuance of securities representing in the aggregate a majority of the voting power of the Company’s issued and outstanding voting securities. Redemption Rights The Preferred Stock does not have redemption rights, except for the contingent redemption upon the occurrence of a Deemed Liquidation Events.
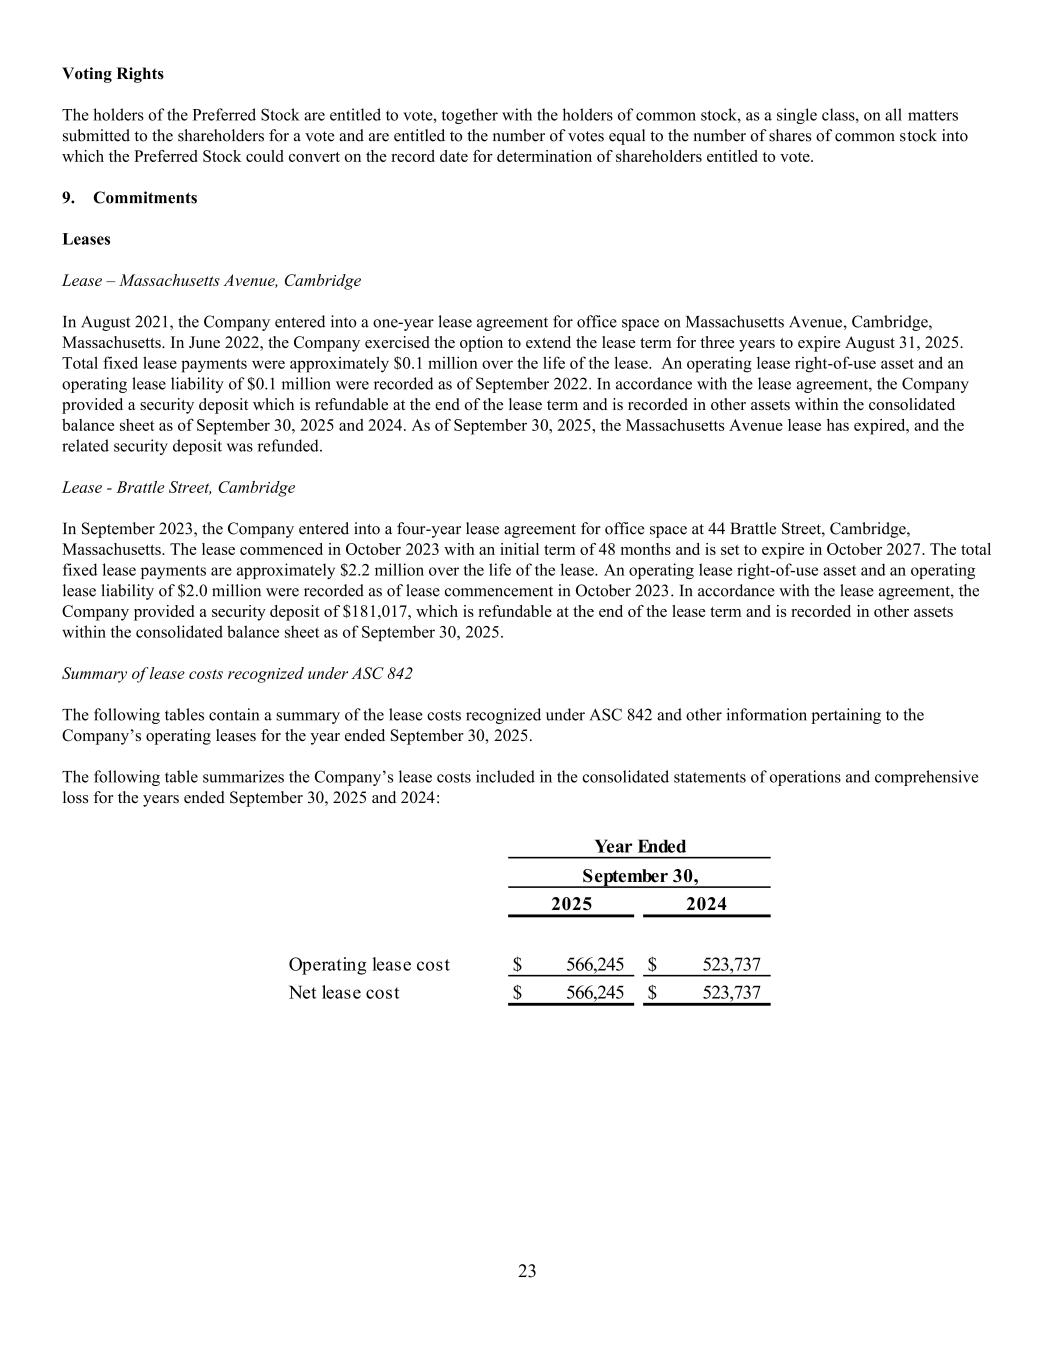
23 Voting Rights The holders of the Preferred Stock are entitled to vote, together with the holders of common stock, as a single class, on all matters submitted to the shareholders for a vote and are entitled to the number of votes equal to the number of shares of common stock into which the Preferred Stock could convert on the record date for determination of shareholders entitled to vote. 9. Commitments Leases Lease – Massachusetts Avenue, Cambridge In August 2021, the Company entered into a one-year lease agreement for office space on Massachusetts Avenue, Cambridge, Massachusetts. In June 2022, the Company exercised the option to extend the lease term for three years to expire August 31, 2025. Total fixed lease payments were approximately $0.1 million over the life of the lease. An operating lease right-of-use asset and an operating lease liability of $0.1 million were recorded as of September 2022. In accordance with the lease agreement, the Company provided a security deposit which is refundable at the end of the lease term and is recorded in other assets within the consolidated balance sheet as of September 30, 2025 and 2024. As of September 30, 2025, the Massachusetts Avenue lease has expired, and the related security deposit was refunded. Lease - Brattle Street, Cambridge In September 2023, the Company entered into a four-year lease agreement for office space at 44 Brattle Street, Cambridge, Massachusetts. The lease commenced in October 2023 with an initial term of 48 months and is set to expire in October 2027. The total fixed lease payments are approximately $2.2 million over the life of the lease. An operating lease right-of-use asset and an operating lease liability of $2.0 million were recorded as of lease commencement in October 2023. In accordance with the lease agreement, the Company provided a security deposit of $181,017, which is refundable at the end of the lease term and is recorded in other assets within the consolidated balance sheet as of September 30, 2025. Summary of lease costs recognized under ASC 842 The following tables contain a summary of the lease costs recognized under ASC 842 and other information pertaining to the Company’s operating leases for the year ended September 30, 2025. The following table summarizes the Company’s lease costs included in the consolidated statements of operations and comprehensive loss for the years ended September 30, 2025 and 2024: 2025 2024 Operating lease cost 566,245$ 523,737$ Net lease cost 566,245$ 523,737$ Year Ended September 30,
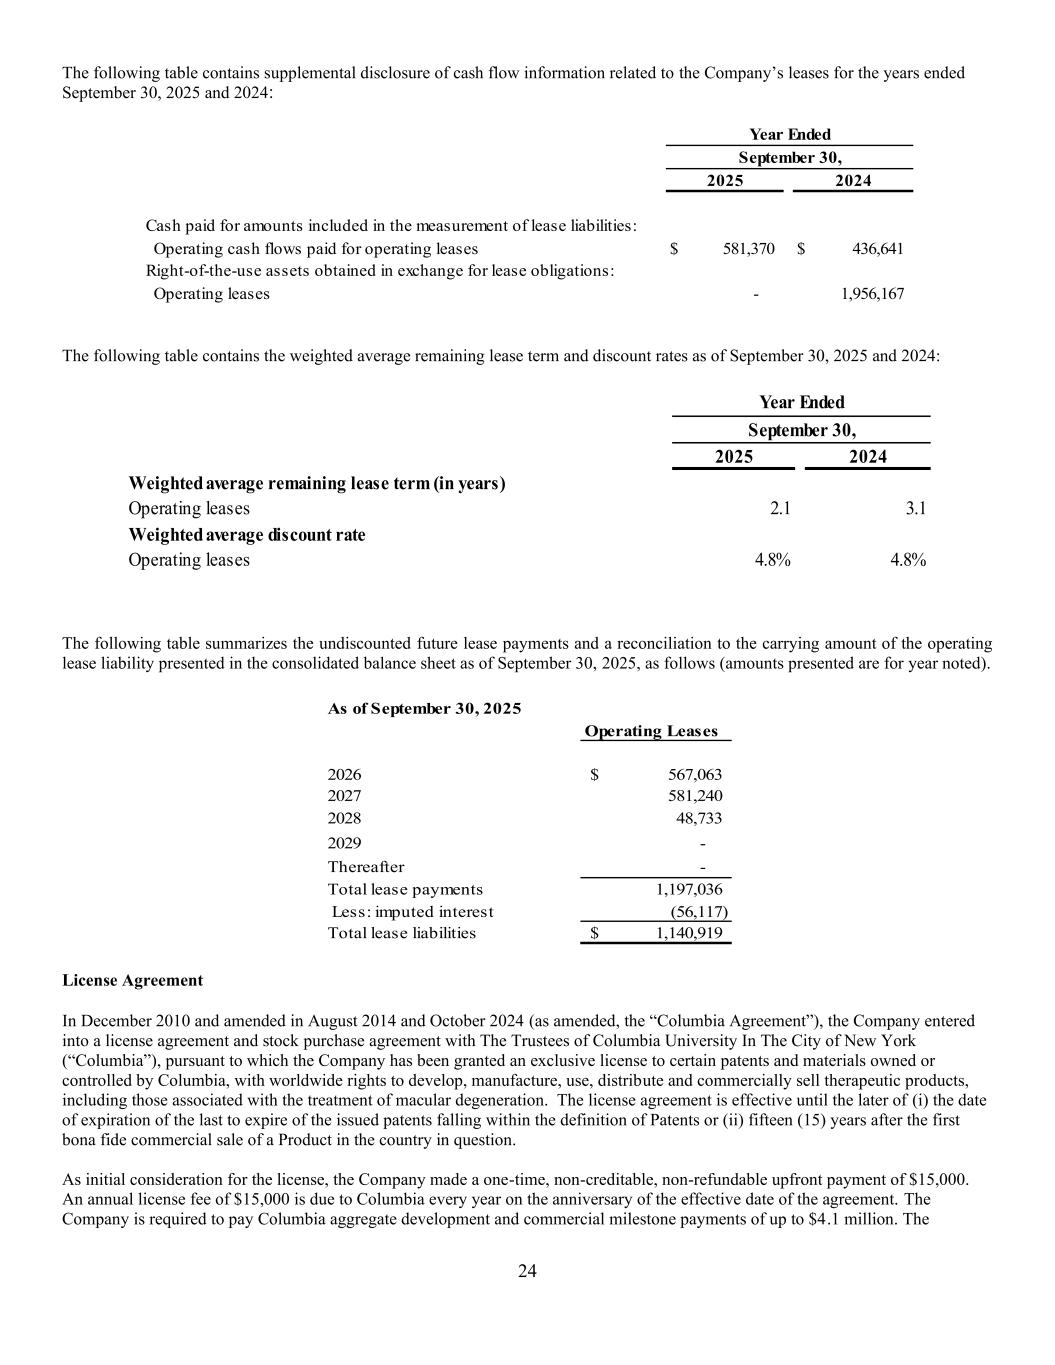
24 The following table contains supplemental disclosure of cash flow information related to the Company’s leases for the years ended September 30, 2025 and 2024: 2025 2024 Cash paid for amounts included in the measurement of lease liabilities: Operating cash flows paid for operating leases 581,370$ 436,641$ Right-of-the-use assets obtained in exchange for lease obligations: Operating leases - 1,956,167 Year Ended September 30, The following table contains the weighted average remaining lease term and discount rates as of September 30, 2025 and 2024: 2025 2024 Weighted average remaining lease term (in years) Operating leases 2.1 3.1 Weighted average discount rate Operating leases 4.8% 4.8% Year Ended September 30, The following table summarizes the undiscounted future lease payments and a reconciliation to the carrying amount of the operating lease liability presented in the consolidated balance sheet as of September 30, 2025, as follows (amounts presented are for year noted). As of September 30, 2025 Operating Leases 2026 567,063$ 2027 581,240 2028 48,733 2029 - Thereafter - Total lease payments 1,197,036 Less: imputed interest (56,117) Total lease liabilities 1,140,919$ License Agreement In December 2010 and amended in August 2014 and October 2024 (as amended, the “Columbia Agreement”), the Company entered into a license agreement and stock purchase agreement with The Trustees of Columbia University In The City of New York (“Columbia”), pursuant to which the Company has been granted an exclusive license to certain patents and materials owned or controlled by Columbia, with worldwide rights to develop, manufacture, use, distribute and commercially sell therapeutic products, including those associated with the treatment of macular degeneration. The license agreement is effective until the later of (i) the date of expiration of the last to expire of the issued patents falling within the definition of Patents or (ii) fifteen (15) years after the first bona fide commercial sale of a Product in the country in question. As initial consideration for the license, the Company made a one-time, non-creditable, non-refundable upfront payment of $15,000. An annual license fee of $15,000 is due to Columbia every year on the anniversary of the effective date of the agreement. The Company is required to pay Columbia aggregate development and commercial milestone payments of up to $4.1 million. The
25 Company is also obligated to pay a tiered percentage royalty on annual net sales in the low single-digits, subject to certain specified reductions. In connection with the Columbia Agreement, the Company initially issued Columbia 120,000 shares of common stock (the “Columbia Equity”) The Company issued a total of an additional 35,451 shares of common stock to Columbia in connection with anti-dilution rights as of September 30, 2023, including 9,401 shares during the year ended September 30, 2023. The Company’s obligations to Columbia for anti-dilution rights were fully settled as part of the Company’s Series B Preferred Stock issuance in November 2022. As of September 30, 2025, no milestone payments or royalties have been incurred related to the Columbia Agreement. 10. Subsequent Events The Company evaluated subsequent events for the consolidated financial statements as of and for the year ended September 30, 2025, events through July 17, 2026, the date on which those financial statements were available to be issued. During November 2025, the board of directors approved a workforce reduction representing 25 employees. The Company incurred approximately $2.9 million in restructuring and restructuring-related charges.
ALKEUS PHARMACEUTICALS, INC. Condensed Consolidated Financial Statements Nine Months ended June 30, 2026 and 2025 Exhibit 99.2
1 ALKEUS PHARMACEUTICALS, INC. Condensed Consolidated Financial Statements Nine Months ended June 30, 2026 and 2025 Table of Contents Condensed Consolidated Balance Sheets................................................................................................................................................... 2 Condensed Consolidated Statements of Operations and Comprehensive Loss ......................................................................................... 3 Condensed Consolidated Statements of Redeemable Convertible Preferred Stock and Stockholders’ Deficit ......................................... 4 Condensed Consolidated Statements of Cash Flows ................................................................................................................................ 5 Notes to Condensed Consolidated Financial Statements .................................................................................................................... 6-19
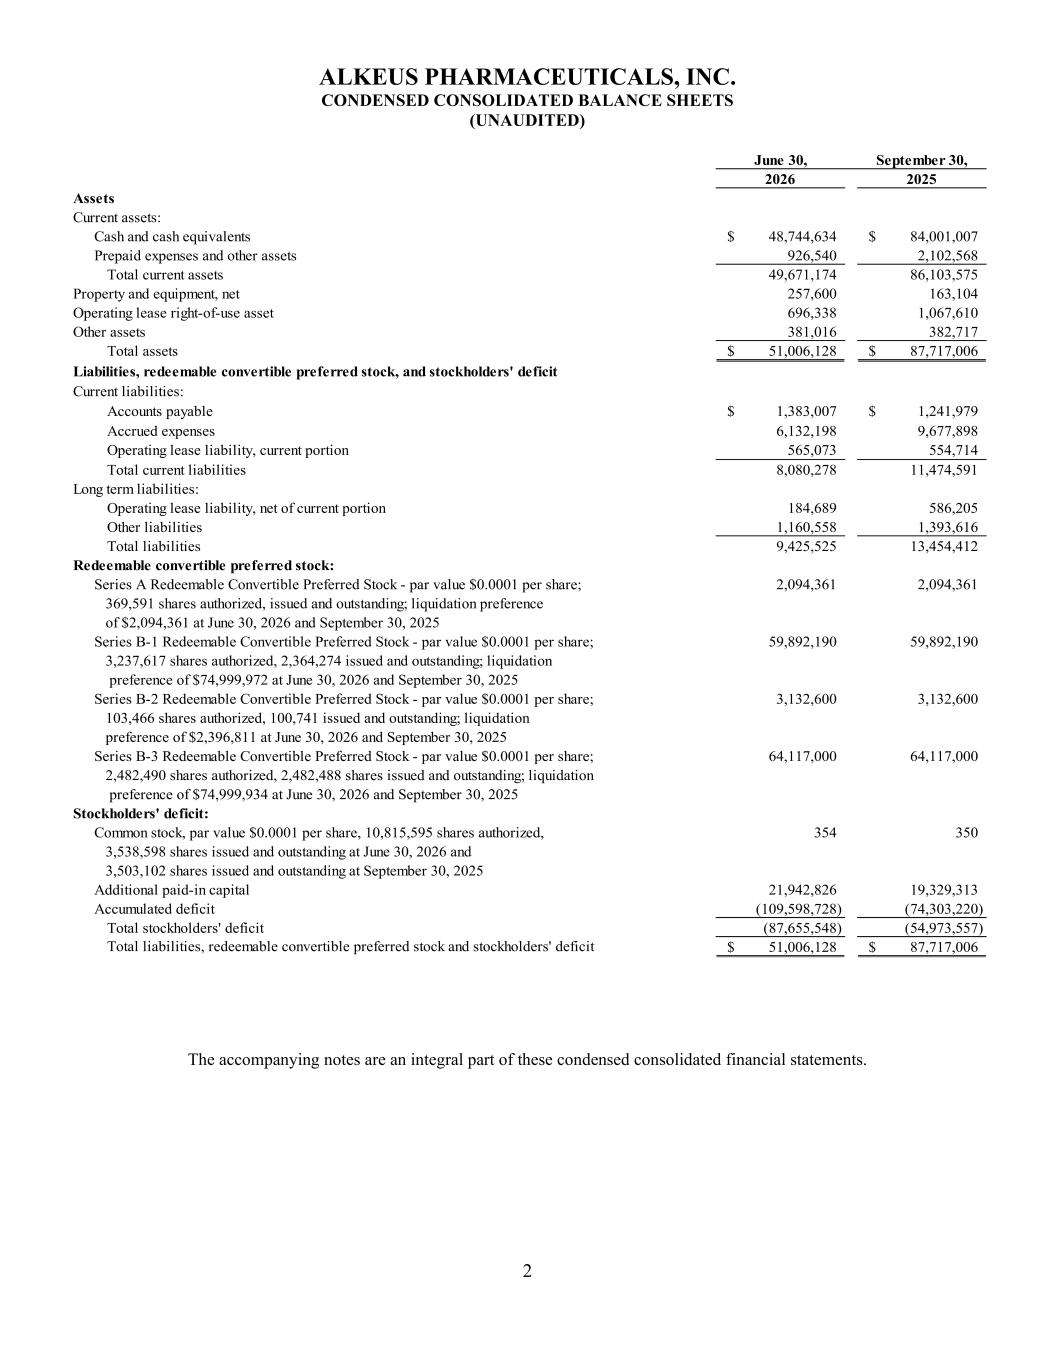
2 ALKEUS PHARMACEUTICALS, INC. CONDENSED CONSOLIDATED BALANCE SHEETS (UNAUDITED) June 30, September 30, 2026 2025 Assets Current assets: Cash and cash equivalents 48,744,634$ 84,001,007$ Prepaid expenses and other assets 926,540 2,102,568 Total current assets 49,671,174 86,103,575 Property and equipment, net 257,600 163,104 Operating lease right-of-use asset 696,338 1,067,610 Other assets 381,016 382,717 Total assets 51,006,128$ 87,717,006$ Liabilities, redeemable convertible preferred stock, and stockholders' deficit Current liabilities: Accounts payable 1,383,007$ 1,241,979$ Accrued expenses 6,132,198 9,677,898 Operating lease liability, current portion 565,073 554,714 Total current liabilities 8,080,278 11,474,591 Long term liabilities: Operating lease liability, net of current portion 184,689 586,205 Other liabilities 1,160,558 1,393,616 Total liabilities 9,425,525 13,454,412 Redeemable convertible preferred stock: Series A Redeemable Convertible Preferred Stock - par value $0.0001 per share; 2,094,361 2,094,361 369,591 shares authorized, issued and outstanding; liquidation preference of $2,094,361 at June 30, 2026 and September 30, 2025 Series B-1 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 59,892,190 59,892,190 3,237,617 shares authorized, 2,364,274 issued and outstanding; liquidation preference of $74,999,972 at June 30, 2026 and September 30, 2025 Series B-2 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 3,132,600 3,132,600 103,466 shares authorized, 100,741 issued and outstanding; liquidation preference of $2,396,811 at June 30, 2026 and September 30, 2025 Series B-3 Redeemable Convertible Preferred Stock - par value $0.0001 per share; 64,117,000 64,117,000 2,482,490 shares authorized, 2,482,488 shares issued and outstanding; liquidation preference of $74,999,934 at June 30, 2026 and September 30, 2025 Stockholders' deficit: Common stock, par value $0.0001 per share, 10,815,595 shares authorized, 354 350 3,538,598 shares issued and outstanding at June 30, 2026 and 3,503,102 shares issued and outstanding at September 30, 2025 Additional paid-in capital 21,942,826 19,329,313 Accumulated deficit (109,598,728) (74,303,220) Total stockholders' deficit (87,655,548) (54,973,557) Total liabilities, redeemable convertible preferred stock and stockholders' deficit 51,006,128$ 87,717,006$ The accompanying notes are an integral part of these condensed consolidated financial statements.
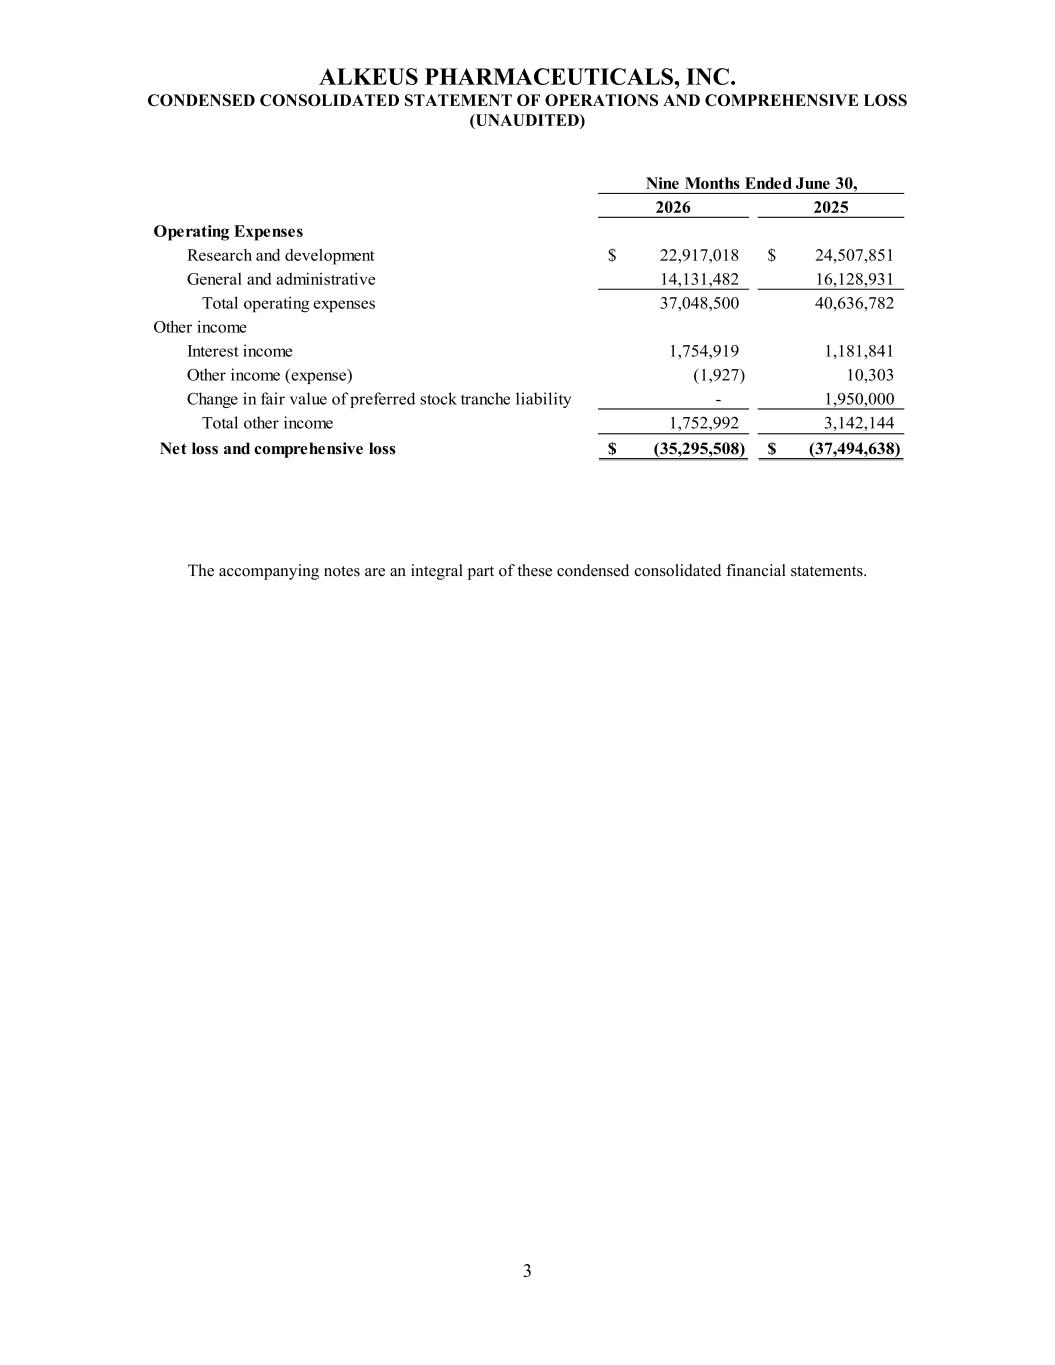
3 ALKEUS PHARMACEUTICALS, INC. CONDENSED CONSOLIDATED STATEMENT OF OPERATIONS AND COMPREHENSIVE LOSS (UNAUDITED) 2026 2025 Operating Expenses Research and development 22,917,018$ 24,507,851$ General and administrative 14,131,482 16,128,931 Total operating expenses 37,048,500 40,636,782 Other income Interest income 1,754,919 1,181,841 Other income (expense) (1,927) 10,303 Change in fair value of preferred stock tranche liability - 1,950,000 Total other income 1,752,992 3,142,144 Net loss and comprehensive loss (35,295,508)$ (37,494,638)$ Nine Months Ended June 30, The accompanying notes are an integral part of these condensed consolidated financial statements.
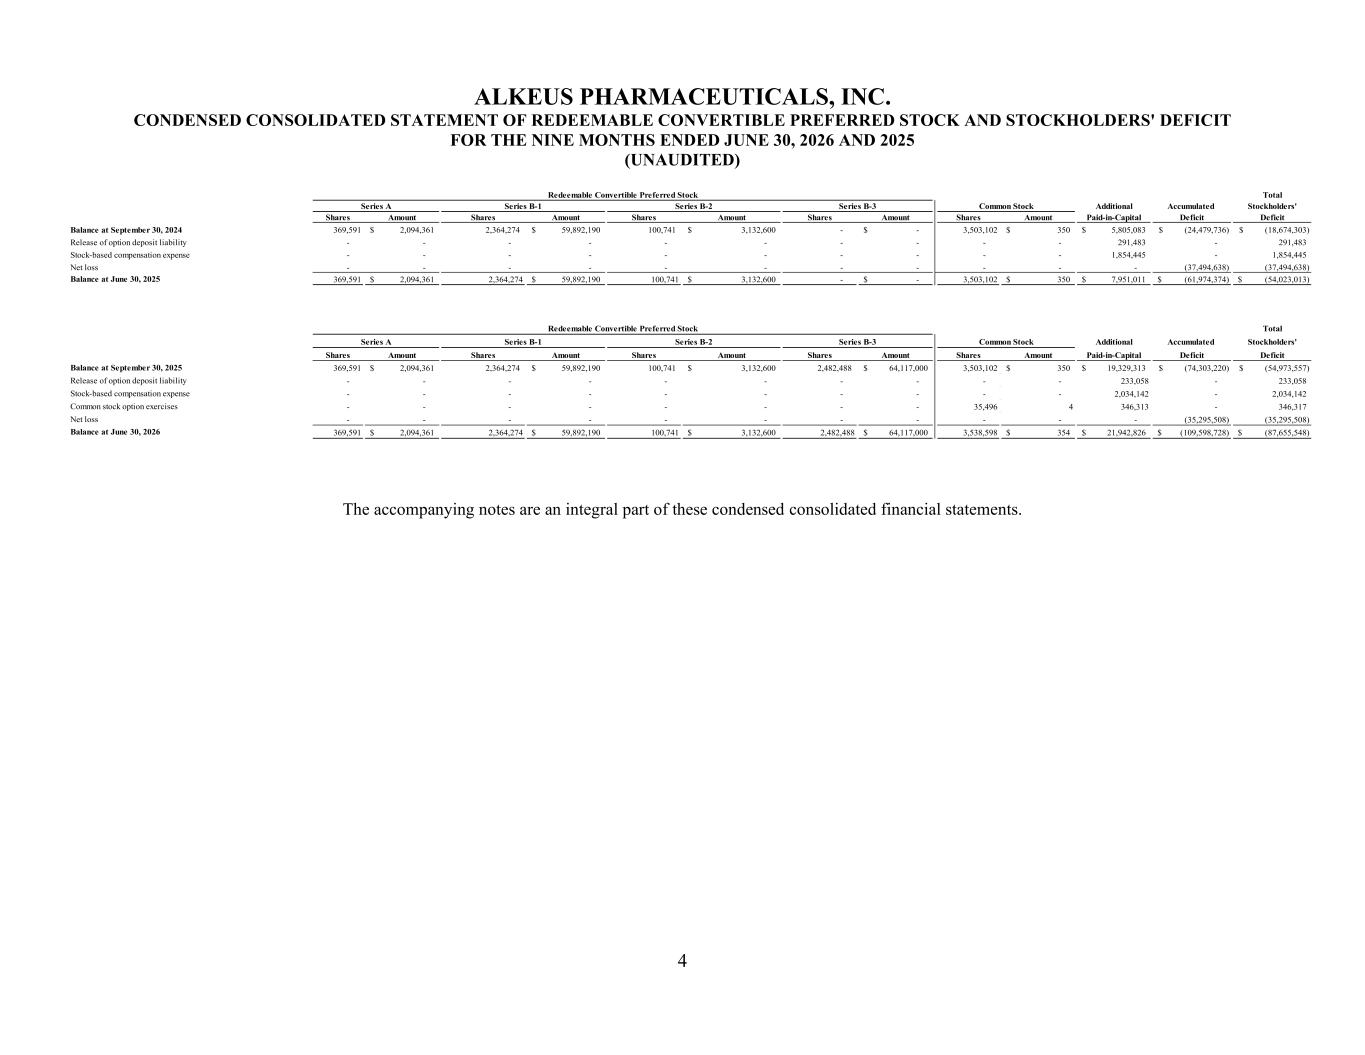
4 ALKEUS PHARMACEUTICALS, INC. CONDENSED CONSOLIDATED STATEMENT OF REDEEMABLE CONVERTIBLE PREFERRED STOCK AND STOCKHOLDERS' DEFICIT FOR THE NINE MONTHS ENDED JUNE 30, 2026 AND 2025 (UNAUDITED) Total Additional Accumulated Stockholders' Shares Amount Shares Amount Shares Amount Shares Amount Shares Amount Paid-in-Capital Deficit Deficit Balance at September 30, 2024 369,591 2,094,361$ 2,364,274 59,892,190$ 100,741 3,132,600$ - -$ 3,503,102 350$ 5,805,083$ (24,479,736)$ (18,674,303)$ Release of option deposit liability - - - - - - - - - - 291,483 - 291,483 Stock-based compensation expense - - - - - - - - - - 1,854,445 - 1,854,445 Net loss - - - - - - - - - - - (37,494,638) (37,494,638) Balance at June 30, 2025 369,591 2,094,361$ 2,364,274 59,892,190$ 100,741 3,132,600$ - -$ 3,503,102 350$ 7,951,011$ (61,974,374)$ (54,023,013)$ Total Additional Accumulated Stockholders' Shares Amount Shares Amount Shares Amount Shares Amount Shares Amount Paid-in-Capital Deficit Deficit Balance at September 30, 2025 369,591 2,094,361$ 2,364,274 59,892,190$ 100,741 3,132,600$ 2,482,488 64,117,000$ 3,503,102 350$ 19,329,313$ (74,303,220)$ (54,973,557)$ Release of option deposit liability - - - - - - - - - - 233,058 - 233,058 Stock-based compensation expense - - - - - - - - - - 2,034,142 - 2,034,142 Common stock option exercises - - - - - - - - 35,496 4 346,313 - 346,317 Net loss - - - - - - - - - - - (35,295,508) (35,295,508) Balance at June 30, 2026 369,591 2,094,361$ 2,364,274 59,892,190$ 100,741 3,132,600$ 2,482,488 64,117,000$ 3,538,598 354$ 21,942,826$ (109,598,728)$ (87,655,548)$ Common Stock Redeemable Convertible Preferred Stock Series A Series B-1 Series B-2 Series B-3 Common Stock Redeemable Convertible Preferred Stock Series A Series B-1 Series B-2 Series B-3 The accompanying notes are an integral part of these condensed consolidated financial statements.
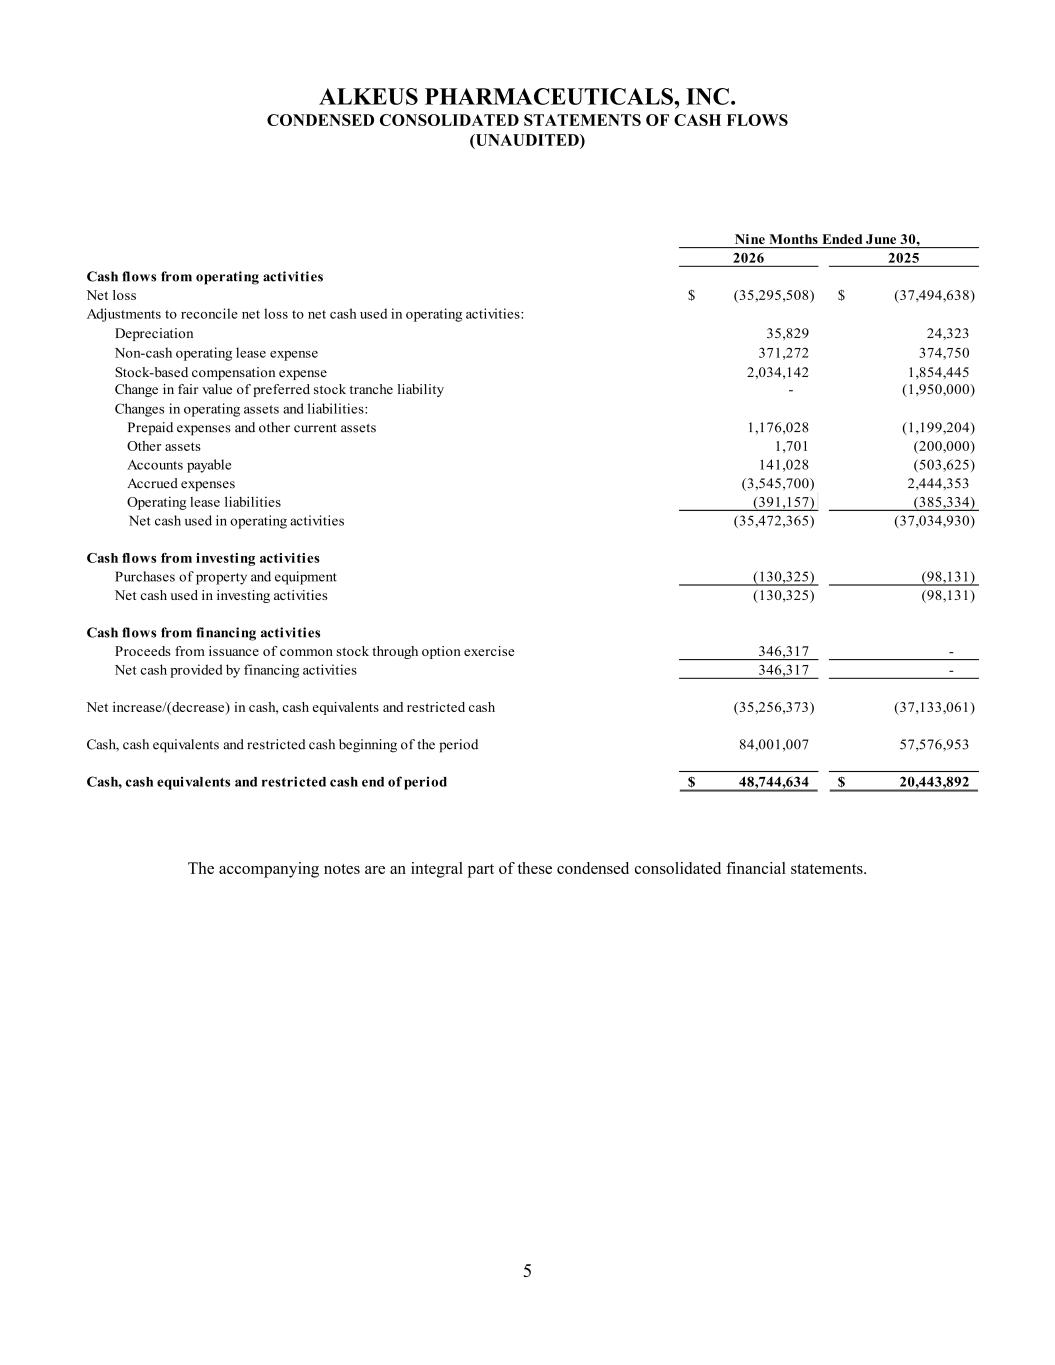
5 ALKEUS PHARMACEUTICALS, INC. CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS (UNAUDITED) 2026 2025 Cash flows from operating activities Net loss (35,295,508)$ (37,494,638)$ Adjustments to reconcile net loss to net cash used in operating activities: Depreciation 35,829 24,323 Non-cash operating lease expense 371,272 374,750 Stock-based compensation expense 2,034,142 1,854,445 Change in fair value of preferred stock tranche liability - (1,950,000) Changes in operating assets and liabilities: Prepaid expenses and other current assets 1,176,028 (1,199,204) Other assets 1,701 (200,000) Accounts payable 141,028 (503,625) Accrued expenses (3,545,700) 2,444,353 Operating lease liabilities (391,157) (385,334) Net cash used in operating activities (35,472,365) (37,034,930) Cash flows from investing activities Purchases of property and equipment (130,325) (98,131) Net cash used in investing activities (130,325) (98,131) Cash flows from financing activities Proceeds from issuance of common stock through option exercise 346,317 - Net cash provided by financing activities 346,317 - Net increase/(decrease) in cash, cash equivalents and restricted cash (35,256,373) (37,133,061) Cash, cash equivalents and restricted cash beginning of the period 84,001,007 57,576,953 Cash, cash equivalents and restricted cash end of period 48,744,634$ 20,443,892$ Nine Months Ended June 30, The accompanying notes are an integral part of these condensed consolidated financial statements.
6 ALKEUS PHARMACEUTICALS, INC. NOTES TO THE CONDENSED CONSOLIDATED FINANCIAL STATEMENTS AS OF AND FOR THE NINE MONTHS ENDED JUNE 30, 2026 AND 2025 (UNAUDITED) 1. Nature of the Business and Basis of Presentation Alkeus Pharmaceuticals, Inc. (the "Company" or "Alkeus") was incorporated on March 3, 2010, under the laws of the State of Delaware. Since its inception, the Company has devoted substantially all of its efforts in developing and advancing a comprehensive clinical program for its lead molecule, gildeuretinol acetate (ALK-001), to treat serious conditions such as Stargardt disease and age- related macular degeneration that leads to retinal damage, vision loss, and blindness. On July 31, 2026, the Company entered into an Agreement and Plan of Merger with Tarsus Pharmaceuticals, Inc. (“Tarsus”). Further details regarding the transaction are disclosed in Note 11, Subsequent Events, to the condensed consolidated financial statements. Risks and Uncertainties The Company is subject to risks common to companies in the pharmaceutical industry. There can be no assurance that the Company's research and development will be successfully completed, that adequate protection for the Company's technology will be obtained, that any products developed will obtain necessary government regulatory approval or that any approved products will be commercially viable. The Company operates in an environment of rapid change in science and technology and of substantial competition from other pharmaceutical companies. In addition, the Company is dependent upon the services of its employees, consultants and contractors. The ongoing research and development activities are subject to regulation by governmental authorities in the United States, as well as other markets. Prior to obtaining marketing approval in the United States or any other markets, any product developed by the Company must undergo rigorous preclinical and clinical testing and an extensive regulatory approval process. There can be no assurance that the Company will not encounter problems in clinical trials that will cause the Company to delay or suspend clinical trials or require additional trials for approval. Clinical trials are currently underway in the United States, in Europe, and other countries. Even if the Company’s product development efforts are successful, it is uncertain when, if ever, the Company will realize revenue from product sales. Basis of Presentation The accompanying unaudited condensed consolidated financial statements have been prepared by the Company in conformity with generally accepted accounting principles in the United States of America (“U.S. GAAP”) and pursuant to the rules and regulations of the U.S. Securities and Exchange Commission (the “SEC”) for interim financial statements. Certain information and footnote disclosures normally included in financial statements prepared in accordance with U.S. GAAP have been condensed or omitted pursuant to such rules and regulations. However, the Company believes that the disclosures are adequate to make the information presented not misleading. These unaudited condensed consolidated financial statements should be read in conjunction with the Company’s audited consolidated financial statements and the notes thereto for the year ended September 30, 2025. The unaudited condensed consolidated financial statements have been prepared on the same basis as the audited consolidated financial statements. In the opinion of management, the accompanying unaudited condensed consolidated financial statements contain all adjustments, including those adjustments that are normal and recurring in nature, which are necessary for a fair statement of the Company’s financial position as of June 30, 2026, and condensed consolidated results of operations for the nine months ended June 30, 2026 and 2025, and cash flows for the nine months ended June 30, 2026 and 2025. The results of operations for the nine months ended June 30, 2026 are not necessarily indicative of the results of operations that may be expected for the year ending September 30, 2026 or for any future period. Principles of Consolidation The accompanying condensed consolidated financial statements include the accounts of Alkeus Pharmaceuticals, Inc. and its wholly owned subsidiary, Alkeus Pharmaceuticals Security Corporation. All intercompany transactions and balances have been eliminated in consolidation.
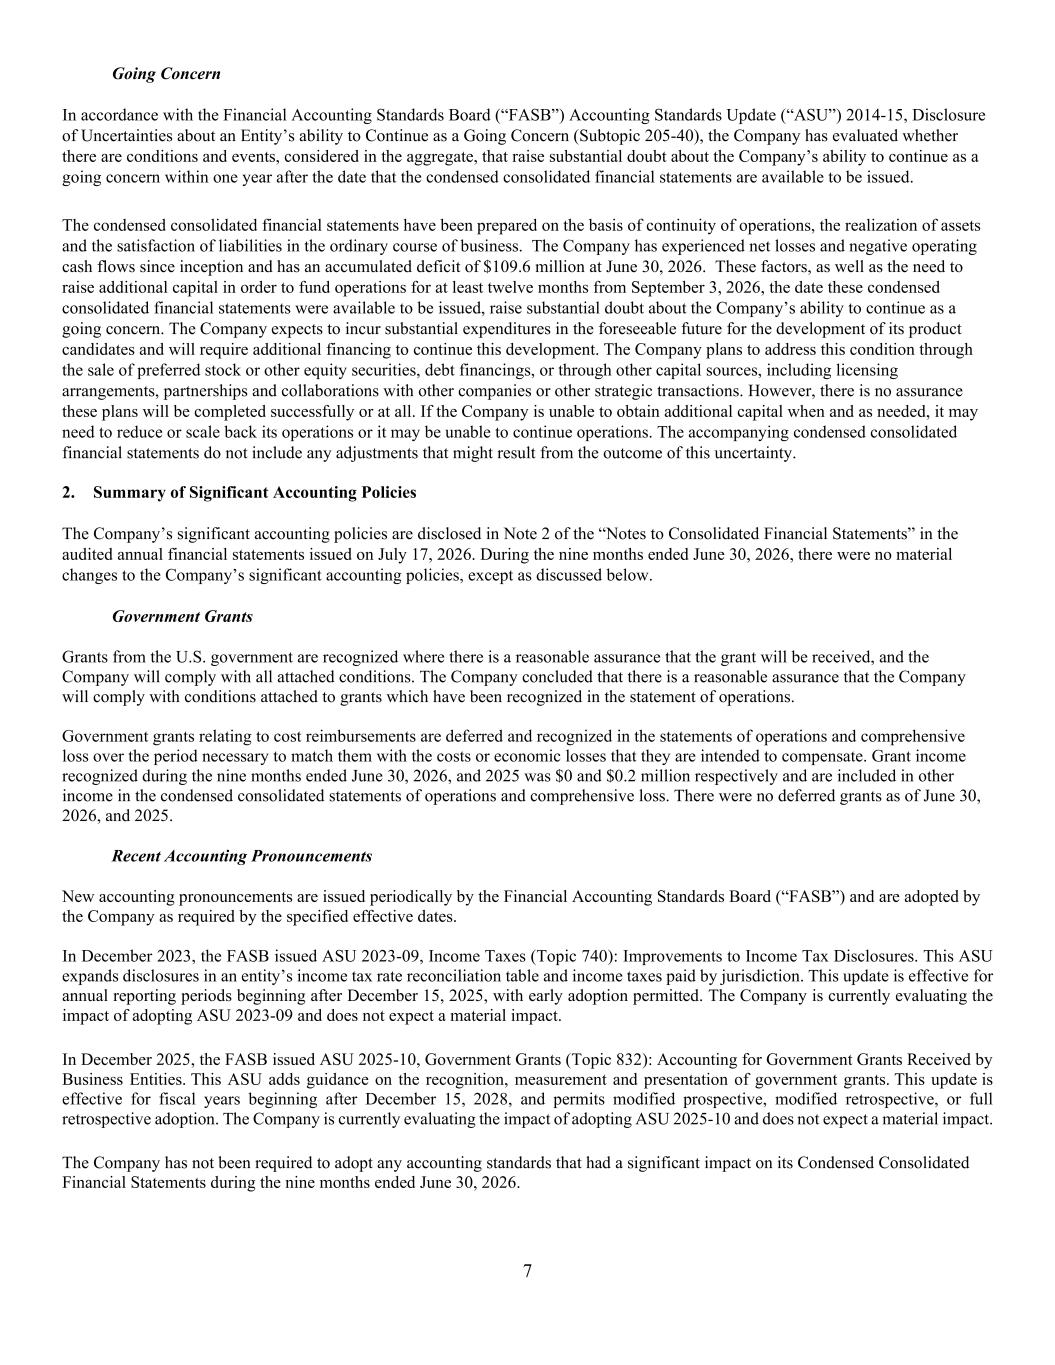
7 Going Concern In accordance with the Financial Accounting Standards Board (“FASB”) Accounting Standards Update (“ASU”) 2014-15, Disclosure of Uncertainties about an Entity’s ability to Continue as a Going Concern (Subtopic 205-40), the Company has evaluated whether there are conditions and events, considered in the aggregate, that raise substantial doubt about the Company’s ability to continue as a going concern within one year after the date that the condensed consolidated financial statements are available to be issued. The condensed consolidated financial statements have been prepared on the basis of continuity of operations, the realization of assets and the satisfaction of liabilities in the ordinary course of business. The Company has experienced net losses and negative operating cash flows since inception and has an accumulated deficit of $109.6 million at June 30, 2026. These factors, as well as the need to raise additional capital in order to fund operations for at least twelve months from September 3, 2026, the date these condensed consolidated financial statements were available to be issued, raise substantial doubt about the Company’s ability to continue as a going concern. The Company expects to incur substantial expenditures in the foreseeable future for the development of its product candidates and will require additional financing to continue this development. The Company plans to address this condition through the sale of preferred stock or other equity securities, debt financings, or through other capital sources, including licensing arrangements, partnerships and collaborations with other companies or other strategic transactions. However, there is no assurance these plans will be completed successfully or at all. If the Company is unable to obtain additional capital when and as needed, it may need to reduce or scale back its operations or it may be unable to continue operations. The accompanying condensed consolidated financial statements do not include any adjustments that might result from the outcome of this uncertainty. 2. Summary of Significant Accounting Policies The Company’s significant accounting policies are disclosed in Note 2 of the “Notes to Consolidated Financial Statements” in the audited annual financial statements issued on July 17, 2026. During the nine months ended June 30, 2026, there were no material changes to the Company’s significant accounting policies, except as discussed below. Government Grants Grants from the U.S. government are recognized where there is a reasonable assurance that the grant will be received, and the Company will comply with all attached conditions. The Company concluded that there is a reasonable assurance that the Company will comply with conditions attached to grants which have been recognized in the statement of operations. Government grants relating to cost reimbursements are deferred and recognized in the statements of operations and comprehensive loss over the period necessary to match them with the costs or economic losses that they are intended to compensate. Grant income recognized during the nine months ended June 30, 2026, and 2025 was $0 and $0.2 million respectively and are included in other income in the condensed consolidated statements of operations and comprehensive loss. There were no deferred grants as of June 30, 2026, and 2025. Recent Accounting Pronouncements New accounting pronouncements are issued periodically by the Financial Accounting Standards Board (“FASB”) and are adopted by the Company as required by the specified effective dates. In December 2023, the FASB issued ASU 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures. This ASU expands disclosures in an entity’s income tax rate reconciliation table and income taxes paid by jurisdiction. This update is effective for annual reporting periods beginning after December 15, 2025, with early adoption permitted. The Company is currently evaluating the impact of adopting ASU 2023-09 and does not expect a material impact. In December 2025, the FASB issued ASU 2025-10, Government Grants (Topic 832): Accounting for Government Grants Received by Business Entities. This ASU adds guidance on the recognition, measurement and presentation of government grants. This update is effective for fiscal years beginning after December 15, 2028, and permits modified prospective, modified retrospective, or full retrospective adoption. The Company is currently evaluating the impact of adopting ASU 2025-10 and does not expect a material impact. The Company has not been required to adopt any accounting standards that had a significant impact on its Condensed Consolidated Financial Statements during the nine months ended June 30, 2026.
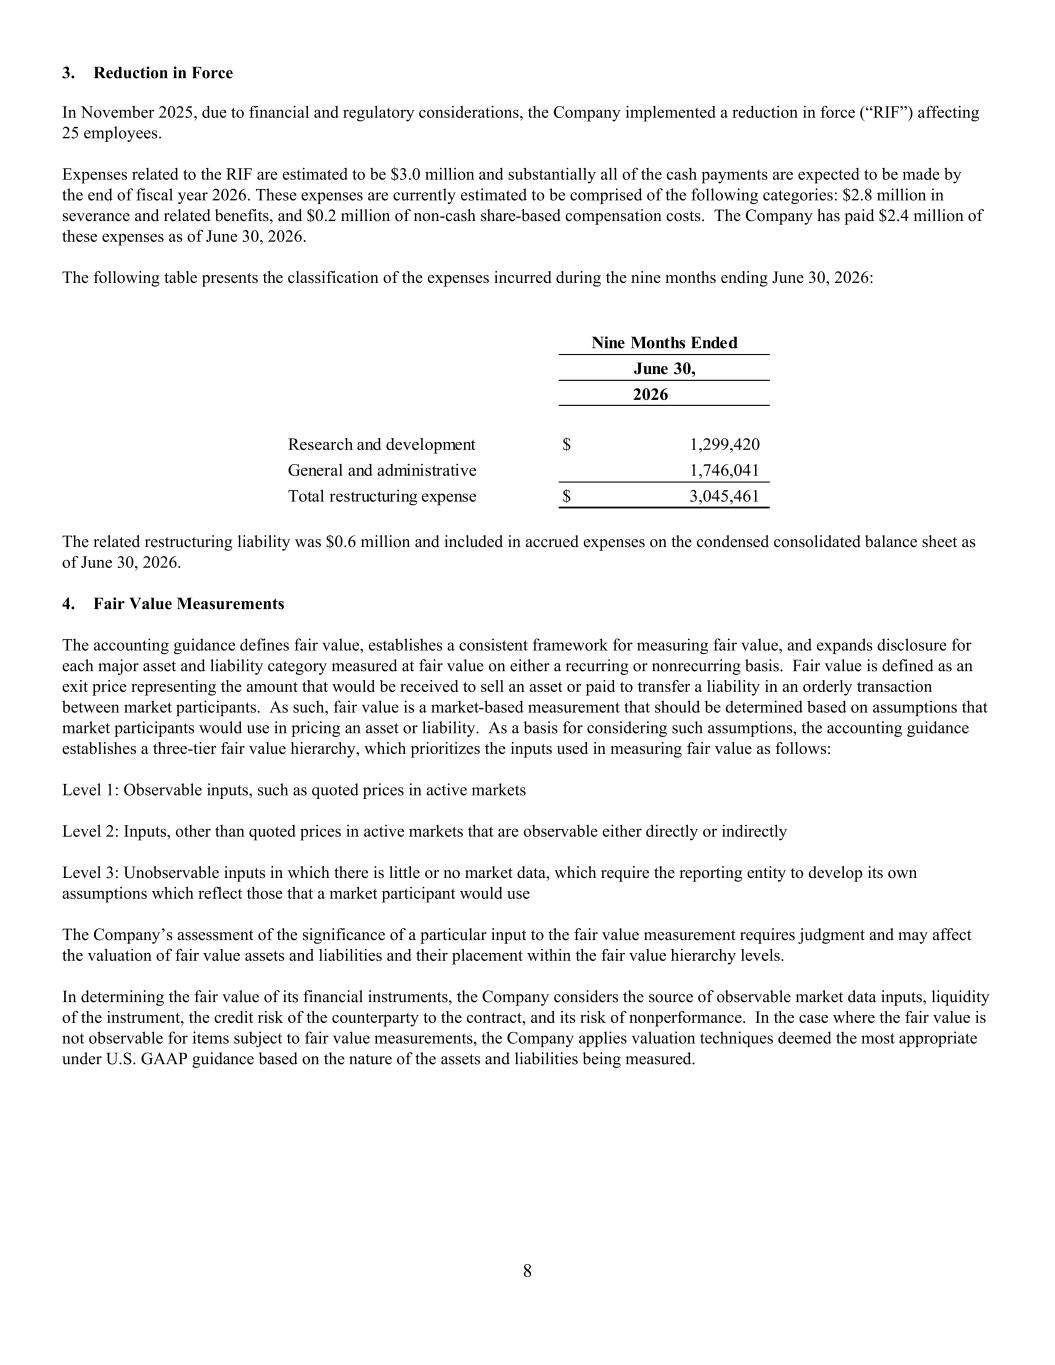
8 3. Reduction in Force In November 2025, due to financial and regulatory considerations, the Company implemented a reduction in force (“RIF”) affecting 25 employees. Expenses related to the RIF are estimated to be $3.0 million and substantially all of the cash payments are expected to be made by the end of fiscal year 2026. These expenses are currently estimated to be comprised of the following categories: $2.8 million in severance and related benefits, and $0.2 million of non-cash share-based compensation costs. The Company has paid $2.4 million of these expenses as of June 30, 2026. The following table presents the classification of the expenses incurred during the nine months ending June 30, 2026: 2026 Research and development 1,299,420$ General and administrative 1,746,041 Total restructuring expense 3,045,461$ Nine Months Ended June 30, The related restructuring liability was $0.6 million and included in accrued expenses on the condensed consolidated balance sheet as of June 30, 2026. 4. Fair Value Measurements The accounting guidance defines fair value, establishes a consistent framework for measuring fair value, and expands disclosure for each major asset and liability category measured at fair value on either a recurring or nonrecurring basis. Fair value is defined as an exit price representing the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants. As such, fair value is a market-based measurement that should be determined based on assumptions that market participants would use in pricing an asset or liability. As a basis for considering such assumptions, the accounting guidance establishes a three-tier fair value hierarchy, which prioritizes the inputs used in measuring fair value as follows: Level 1: Observable inputs, such as quoted prices in active markets Level 2: Inputs, other than quoted prices in active markets that are observable either directly or indirectly Level 3: Unobservable inputs in which there is little or no market data, which require the reporting entity to develop its own assumptions which reflect those that a market participant would use The Company’s assessment of the significance of a particular input to the fair value measurement requires judgment and may affect the valuation of fair value assets and liabilities and their placement within the fair value hierarchy levels. In determining the fair value of its financial instruments, the Company considers the source of observable market data inputs, liquidity of the instrument, the credit risk of the counterparty to the contract, and its risk of nonperformance. In the case where the fair value is not observable for items subject to fair value measurements, the Company applies valuation techniques deemed the most appropriate under U.S. GAAP guidance based on the nature of the assets and liabilities being measured.
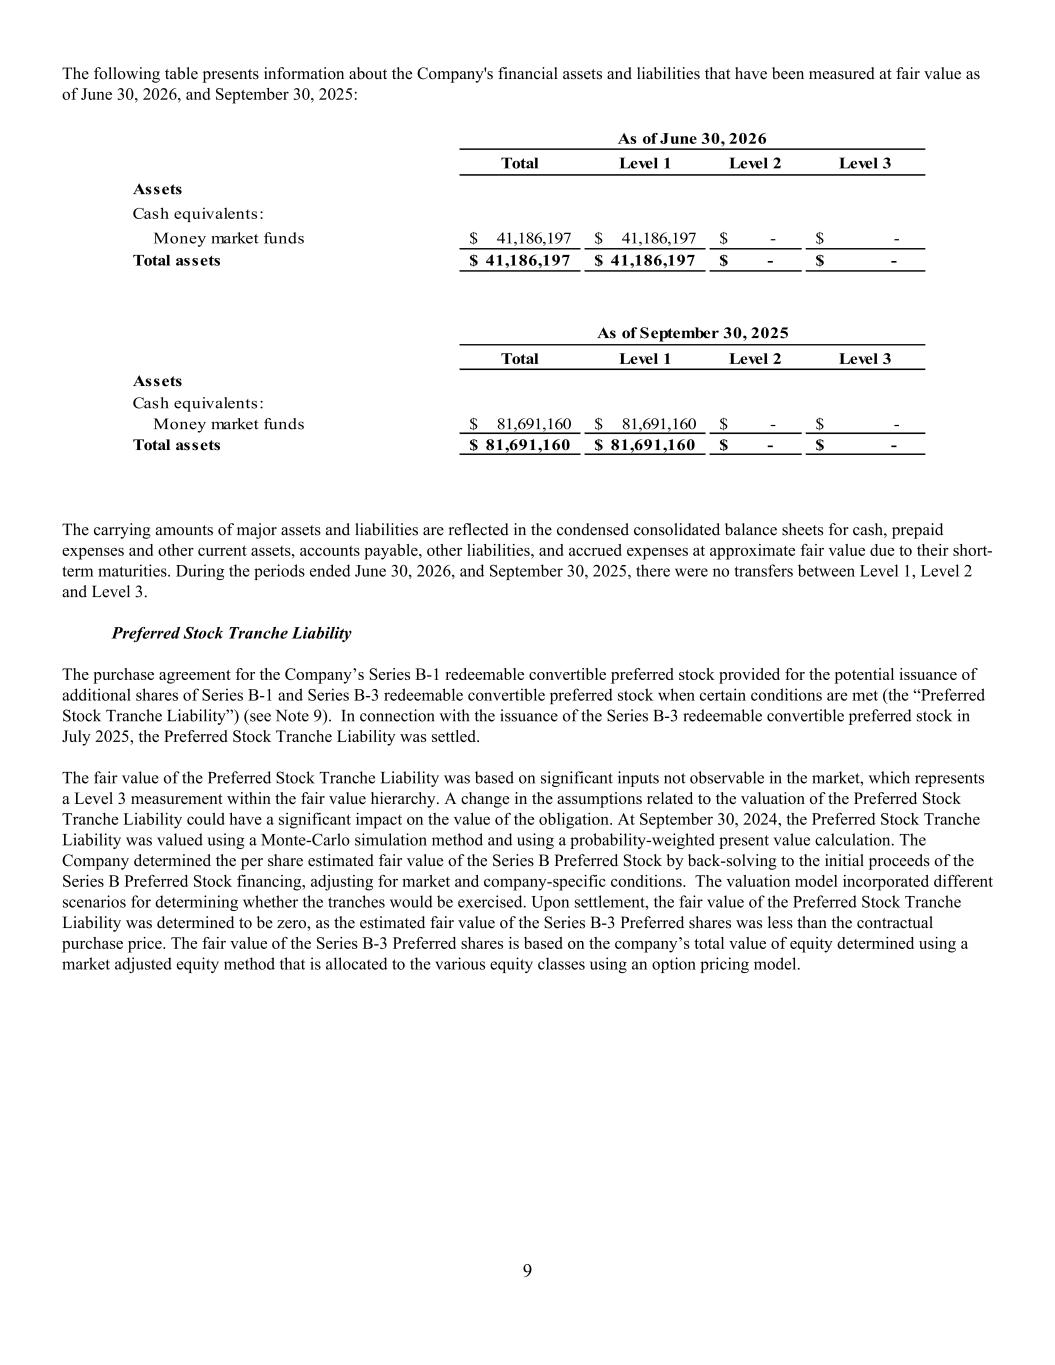
9 The following table presents information about the Company's financial assets and liabilities that have been measured at fair value as of June 30, 2026, and September 30, 2025: Total Level 1 Level 2 Level 3 Assets Cash equivalents: Money market funds 41,186,197$ 41,186,197$ -$ -$ Total assets 41,186,197$ 41,186,197$ -$ -$ Total Level 1 Level 2 Level 3 Assets Cash equivalents: Money market funds 81,691,160$ 81,691,160$ -$ -$ Total assets 81,691,160$ 81,691,160$ -$ -$ As of June 30, 2026 As of September 30, 2025 The carrying amounts of major assets and liabilities are reflected in the condensed consolidated balance sheets for cash, prepaid expenses and other current assets, accounts payable, other liabilities, and accrued expenses at approximate fair value due to their short- term maturities. During the periods ended June 30, 2026, and September 30, 2025, there were no transfers between Level 1, Level 2 and Level 3. Preferred Stock Tranche Liability The purchase agreement for the Company’s Series B-1 redeemable convertible preferred stock provided for the potential issuance of additional shares of Series B-1 and Series B-3 redeemable convertible preferred stock when certain conditions are met (the “Preferred Stock Tranche Liability”) (see Note 9). In connection with the issuance of the Series B-3 redeemable convertible preferred stock in July 2025, the Preferred Stock Tranche Liability was settled. The fair value of the Preferred Stock Tranche Liability was based on significant inputs not observable in the market, which represents a Level 3 measurement within the fair value hierarchy. A change in the assumptions related to the valuation of the Preferred Stock Tranche Liability could have a significant impact on the value of the obligation. At September 30, 2024, the Preferred Stock Tranche Liability was valued using a Monte-Carlo simulation method and using a probability-weighted present value calculation. The Company determined the per share estimated fair value of the Series B Preferred Stock by back-solving to the initial proceeds of the Series B Preferred Stock financing, adjusting for market and company-specific conditions. The valuation model incorporated different scenarios for determining whether the tranches would be exercised. Upon settlement, the fair value of the Preferred Stock Tranche Liability was determined to be zero, as the estimated fair value of the Series B-3 Preferred shares was less than the contractual purchase price. The fair value of the Series B-3 Preferred shares is based on the company’s total value of equity determined using a market adjusted equity method that is allocated to the various equity classes using an option pricing model.
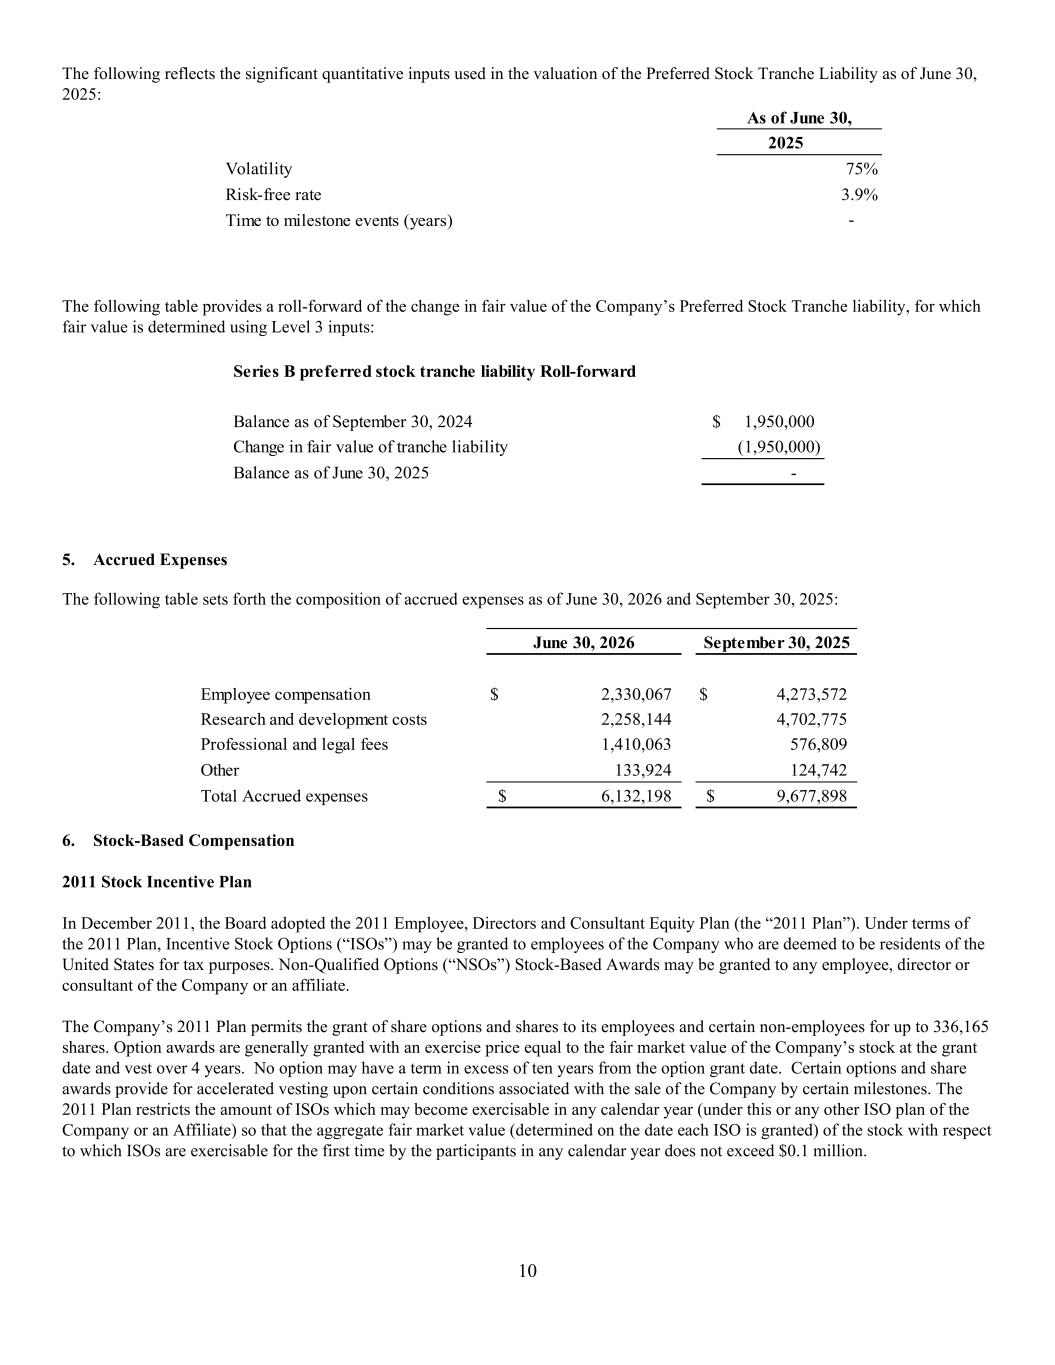
10 The following reflects the significant quantitative inputs used in the valuation of the Preferred Stock Tranche Liability as of June 30, 2025: 2025 Volatility 75% Risk-free rate 3.9% Time to milestone events (years) - As of June 30, The following table provides a roll-forward of the change in fair value of the Company’s Preferred Stock Tranche liability, for which fair value is determined using Level 3 inputs: Series B preferred stock tranche liability Roll-forward Balance as of September 30, 2024 1,950,000$ Change in fair value of tranche liability (1,950,000) Balance as of June 30, 2025 - 5. Accrued Expenses The following table sets forth the composition of accrued expenses as of June 30, 2026 and September 30, 2025: June 30, 2026 September 30, 2025 Employee compensation 2,330,067$ 4,273,572$ Research and development costs 2,258,144 4,702,775 Professional and legal fees 1,410,063 576,809 Other 133,924 124,742 Total Accrued expenses 6,132,198$ 9,677,898$ 6. Stock-Based Compensation 2011 Stock Incentive Plan In December 2011, the Board adopted the 2011 Employee, Directors and Consultant Equity Plan (the “2011 Plan”). Under terms of the 2011 Plan, Incentive Stock Options (“ISOs”) may be granted to employees of the Company who are deemed to be residents of the United States for tax purposes. Non-Qualified Options (“NSOs”) Stock-Based Awards may be granted to any employee, director or consultant of the Company or an affiliate. The Company’s 2011 Plan permits the grant of share options and shares to its employees and certain non-employees for up to 336,165 shares. Option awards are generally granted with an exercise price equal to the fair market value of the Company’s stock at the grant date and vest over 4 years. No option may have a term in excess of ten years from the option grant date. Certain options and share awards provide for accelerated vesting upon certain conditions associated with the sale of the Company by certain milestones. The 2011 Plan restricts the amount of ISOs which may become exercisable in any calendar year (under this or any other ISO plan of the Company or an Affiliate) so that the aggregate fair market value (determined on the date each ISO is granted) of the stock with respect to which ISOs are exercisable for the first time by the participants in any calendar year does not exceed $0.1 million.
11 2022 Stock Incentive Plan In November 2022 the Board adopted the 2022 Stock Option and Grant Plan (the “2022 Plan”). Under terms of the 2022 Plan, incentive stock options (“ISOs”) may be granted to employees of the Company and nonqualified stock options, or restricted stock awards may be granted to directors, consultants, employees, and officers of the Company. The Company’s 2022 Plan permits the grant of share options and shares to its employees and certain non-employees for up to 1,691,756 shares. Option awards are generally granted with an exercise price equal to the fair market value of the Company’s stock at the grant date and vest over 4 years. No option may have a term in excess of ten years from the option grant date. Certain options and share awards provide accelerated vesting. ISOs granted under the Plan and any other plan of the Company that become exercisable for the first time by a participant during any calendar year shall not exceed $0.1 million or such other limit as may be in effect from time to time. Any stock options that exceed this limit constitute NSOs. Performance-Based Stock Options In April 2023, the Company’s Board of Directors granted options to purchase common stock to some employees and directors that will vest upon the successful sale of the Company in which the shareholders of the Company will receive aggregate upfront, non- contingent proceeds of at least $2.5 billion from such sale (the “Performance Awards”). The qualifying sale must occur prior to the earlier of 1) the Company obtaining FDA approval for its New Drug Application (NDA) for drug candidate ALK-001 and 2) March 31, 2025. In addition, the Company granted separate stock option awards to certain employees and directors that vest upon a successful sale of the Company resulting in aggregate upfront, non-contingent proceeds of at least $5.0 billion. These awards require that such sale occur prior to the later of 1) the fourth anniversary of the grant date or 2) April 12, 2027. The Company issued 145,772 Performance Awards during the year ended September 30, 2023, with an exercise price of $10.67 per share. The aggregate fair value at date of grant was $1,106,771. The Company issued 18,212 Performance Awards during the year ended September 30, 2024, with an exercise price of $7.79 per share. The aggregate fair value at date of grant was $102,979. There were no such Performance Awards issued during the year ended September 30, 2025 and the nine months ended June 30, 2026. The Company determined that the achievement of the milestones was not probable during the nine months ended June 30, 2025, and June 30, 2026, and therefore no stock-based compensation expense was recognized in the respective periods. Early Exercise Options The Company allows certain of its employees and directors to exercise options granted under the 2022 Plan prior to the vesting of those awards. The shares related to early-exercise stock options are subject to transfer restrictions and the Company’s repurchase right upon termination of employment of services and are therefore considered restricted common stock. The proceeds received by the Company are recorded as other liability until the repurchase right lapses as the award vests. The liabilities are reclassified to additional-paid-in-capital as the repurchase right lapses. As of June 30, 2026, 72,846 performance-based stock options and 37,853 time-based stock options early exercised remain unvested and subject to the Company’s repurchase right.
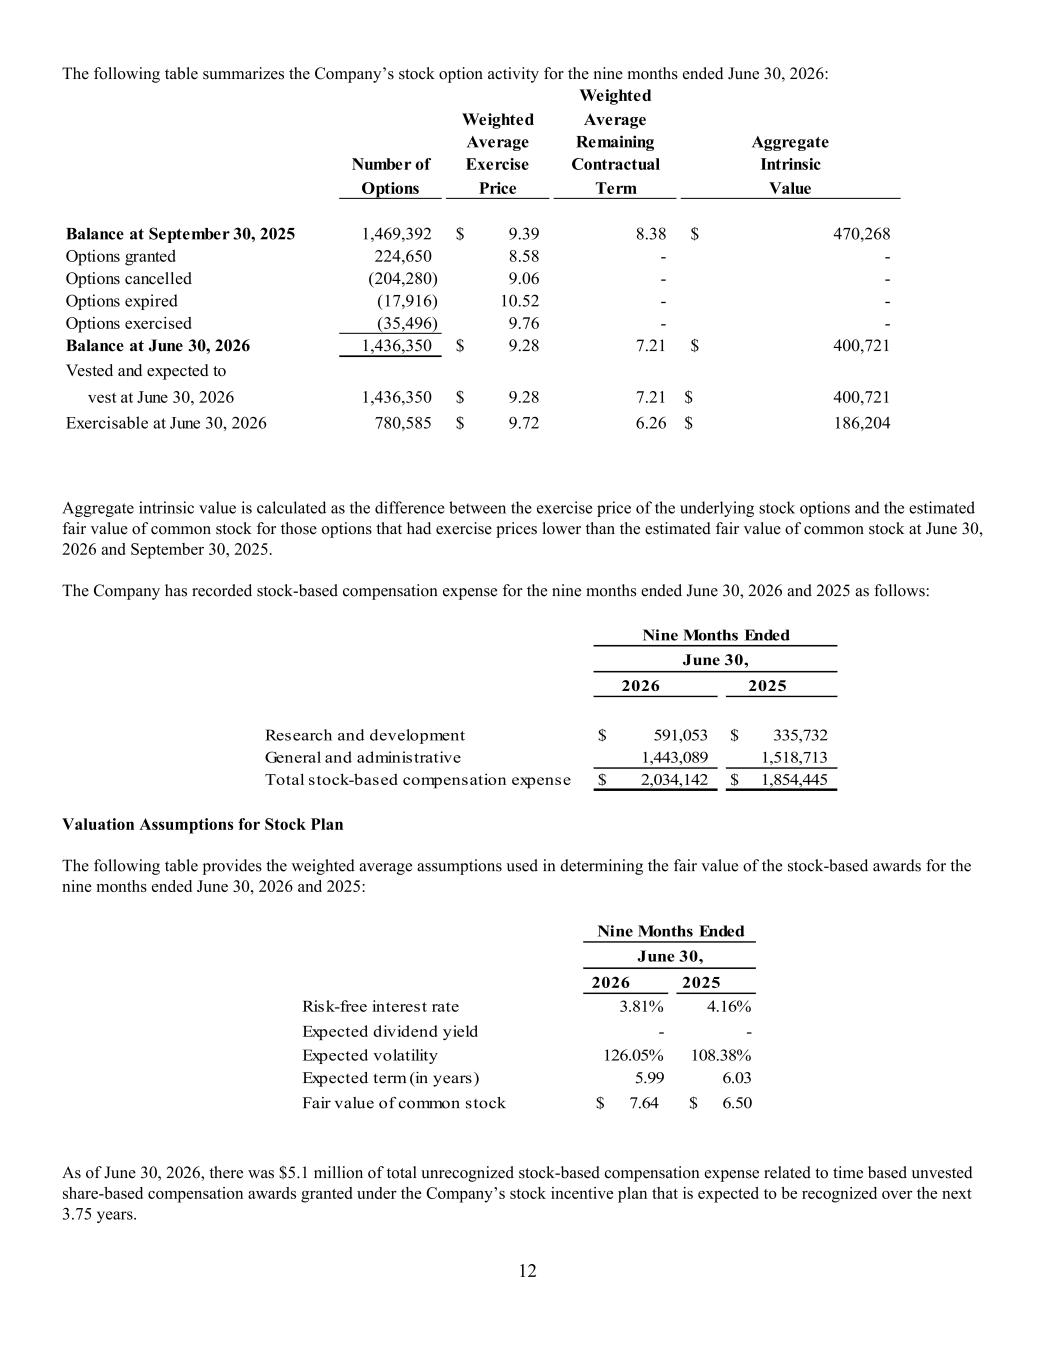
12 The following table summarizes the Company’s stock option activity for the nine months ended June 30, 2026: Weighted Weighted Average Average Remaining Aggregate Number of Exercise Contractual Intrinsic Options Price Term Value Balance at September 30, 2025 1,469,392 9.39$ 8.38 470,268$ Options granted 224,650 8.58 - - Options cancelled (204,280) 9.06 - - Options expired (17,916) 10.52 - - Options exercised (35,496) 9.76 - - Balance at June 30, 2026 1,436,350 9.28$ 7.21 400,721$ Vested and expected to vest at June 30, 2026 1,436,350 9.28$ 7.21 400,721$ Exercisable at June 30, 2026 780,585 9.72$ 6.26 186,204$ Aggregate intrinsic value is calculated as the difference between the exercise price of the underlying stock options and the estimated fair value of common stock for those options that had exercise prices lower than the estimated fair value of common stock at June 30, 2026 and September 30, 2025. The Company has recorded stock-based compensation expense for the nine months ended June 30, 2026 and 2025 as follows: 2026 2025 Research and development 591,053$ 335,732$ General and administrative 1,443,089 1,518,713 Total stock-based compensation expense 2,034,142$ 1,854,445$ June 30, Nine Months Ended Valuation Assumptions for Stock Plan The following table provides the weighted average assumptions used in determining the fair value of the stock-based awards for the nine months ended June 30, 2026 and 2025: 2026 2025 Risk-free interest rate 3.81% 4.16% Expected dividend yield - - Expected volatility 126.05% 108.38% Expected term (in years) 5.99 6.03 Fair value of common stock 7.64$ $ 6.50 Nine Months Ended June 30, As of June 30, 2026, there was $5.1 million of total unrecognized stock-based compensation expense related to time based unvested share-based compensation awards granted under the Company’s stock incentive plan that is expected to be recognized over the next 3.75 years.
13 7. Income Taxes The Company has not recorded an income tax expense or benefit due to operating losses since its inception and the establishment of valuation allowances. The Company is forecasting a taxable loss position for the year-ended September 30, 2026 for which no tax benefit is recorded due to the valuation allowance maintained against the Company’s deferred tax assets. The effective income tax rate for the nine months ended June 30, 2026 and 2025 differed from the 21.0% federal statutory rate primarily due to the valuation allowance maintained against the Company’s deferred tax assets. On July 4, 2025, new U.S. tax legislation referred to as the OBBBA was signed into law. The OBBBA contains several changes to corporate taxation, including modifications to capitalization of research and development expenses, limitations on deductions for interest expense and accelerated fixed asset depreciation. The legislation has multiple effective dates including the 2026 tax year. The Company does not expect the OBBBA to have a material impact on its effective tax rate and net deferred tax asset balance in 2026 and there was no material impact on 2025. 8. Common Stock The Second Amended and Restated Certificate of Incorporation of Alkeus Pharmaceuticals, Inc. as certified on April 28, 2023 (the “Charter”) authorizes the Company to issue 10,815,595 shares of $0.0001 par value common stock. Each share of common stock entitles the stockholder to one vote on all matters submitted to a vote of the Company's stockholders. Common stockholders are entitled to receive dividends, as may be declared by the board of directors, if any, subject to the preferential dividend rights of the convertible preferred stock. When dividends are declared on shares of common stock, the Company must declare at the same time a dividend payable to the holders of convertible preferred stock equivalent to the dividend amount they would receive if each preferred share were converted into common stock. As of June 30, 2026, and 2025, no dividends had been declared. As of June 30, 2026, and 2025 and per the Company Charter, the Company had reserved sufficient shares of common stock for the conversion of the Series A, Series B-1, Series B-2 and Series B-3 convertible preferred stock (see Note 9) and the exercise of outstanding stock options (see Note 6). 9. Redeemable Convertible Preferred Stock The Company has issued Series A redeemable convertible preferred stock ("Series A Preferred Stock") and Series B-1, B-2 and B-3 redeemable convertible preferred stock ("Series B Preferred Stock"), together, "Preferred Stock”. In 2011, the Company issued 369,591 shares of Series A Preferred Stock at an original issue price of $5.67 per share for total cash proceeds of $2.1 million. In November 2022 the Company issued 1,618,809 shares of Series B-1 Preferred Stock in an initial closing at $30.89 per share for total gross proceeds of approximately $50 million less issuance costs of approximately $0.4 million. In April 2023, the Company issued 809,404 shares of Series B-1 Preferred Stock in a subsequent initial closing at $30.89 per share for total gross proceeds of approximately $25 million. Additionally, in November 2022, the Company issued 103,466 shares of Series B-2 Preferred Stock in exchange for the convertible promissory notes which were recorded at their fair value of $3.2 million. Pursuant to the terms of the Series B Preferred Stock Purchase Agreement (the “Purchase Agreement”), due to the non-occurrence of the First Tranche Expansion prior to June 30, 2024, effective July 1, 2024, 63,939 shares of Series B-1 Preferred Stock and 2,725 shares of Series B-2 Preferred Stock were forfeited by investors to the Company. These share forfeitures resulted in an adjustment to the Series B-1 Preferred Stock original issue price per share from $30.89 to $31.7222 and the Series B-2 Preferred Stock price per share from $23.1652 to $23.79. On April 11, 2025, the Company and the Holders of the Series B Preferred Stock entered into an amendment to the Purchase Agreement (the “Amended Purchase Agreement”) which extended the timing and adjusted the criteria of the closing of the 2nd tranche period. On July 7, 2025, the Company issued 2,482,488 shares of Series B-3 Preferred Stock to stockholders in accordance with the Amended Purchase Agreement at $30.21 per share for total gross proceeds of $75.0 million, which represented the remaining funding under the Purchase Agreement. The $10.7 million of proceeds received in excess of the fair value of the Series B-3 Preferred Stock was recorded as additional paid-in capital. As part of the issuance of the Series B-3 Preferred Stock, the Preferred Stock Tranche Liability was settled (see Note 4).
14 The Series B Preferred Stock Purchase Agreement included certain obligations to issue Series B-1 and Series B-3 Preferred Stock, including: - The First Tranche Expansion: The Company can require investors to purchase up to $25.0 million on a pro rata basis within 14 days of US or EU regulatory acceptance of the Company's new drug application if the acceptance occurs before June 30, 2024. The First Tranche Expansion would consist of an additional 809,404 Series B-1 shares issued at an original issue price of $30.89 per share. - The Second Tranche: Investors have the option to purchase, and the Company is required to sell up to $75.0 million Series B-3 shares, less any dollars funded in the First Tranche Expansion. The Second Tranche commences on the earliest of (a) FDA Approval, (b) EMA Approval, (c) the unanimous Board consent that neither FDA Approval nor EMA Approval will occur before the Approval By Date, or (d) one day after the Approval By Date and ends on the earlier of (a) April 15, 2025, or (b) the consummation of an Alternative Financing. The “Approval By Date” is March 31, 2025, subject to extension if the FDA originally notifies the Company of a PDUFA (Prescription Drug User Fee Act) date on or prior to March 31, 2025, and if the FDA needs to postpone that date due to certain conditions. o Prior to either FDA or EMA approval, the Second Tranche would consist of (a) 2,482,490 Series B-3 shares at $30.2116 per share in the event there shall not have been a First Tranche Expansion closing or (b) 1,666,422 Series B shares at $30.0044 per share in the event there shall have been a First Tranche Expansion closing. o Subsequent to EMA Approval and prior to FDA Approval, the Second Tranche would consist of (a) 1,797,496 Series B-3 shares at $41.7247 per share in the event there shall not have been a First Tranche Expansion closing or (b) 1,202,871 Series B-3 shares at $41.5672 per share in the event there shall have been a First Tranche Expansion closing. o Subsequent to FDA Approval, the Second Tranche shares purchase price shall be (a) 549,257 Series B-3 shares at $136.5479 per share in the event there shall not have been a First Tranche Expansion closing and (b) 389,997 Series B-3 shares at $128.2060 per share in the event there shall have been a First Tranche Expansion closing. The Company initially recorded the Preferred Stock Tranche Liability at fair value of $12.7 million in April 2023. Changes in the fair value of the Preferred Stock Tranche Liability are recognized as a component of other income (expense) in the condensed consolidated statement of operations and comprehensive loss. During the year ended September 30, 2024, the Company recorded $6.7 million as other income for the remeasurement to fair value at the end of the reporting period. During the year ended September 30, 2025, the Company recorded $1.95 million as other income as part of the settlement of the tranche liability in connection with the issuance of the Series B-3 Preferred Stock.
15 The Preferred Stock consisted of the following: Common Stock Shares Shares Issued Liquidation Carrying Issuable Upon Authorized and Outstanding Preference Value Conversion Series A 369,591 369,591 2,094,361$ 2,094,361$ 369,591 Series B-1 3,237,617 2,364,274 74,999,972 59,892,190 2,364,274 Series B-2 103,466 100,741 2,396,811 3,132,600 100,741 Series B-3 2,482,490 2,482,488 74,999,934 64,117,000 2,482,488 Total 6,193,164 5,317,094 154,491,078$ 129,236,151$ 5,317,094 Common Stock Shares Shares Issued Liquidation Carrying Issuable Upon Authorized and Outstanding Preference Value Conversion Series A 369,591 369,591 2,094,361$ 2,094,361$ 369,591 Series B-1 3,237,617 2,364,274 74,999,972 59,892,190 2,364,274 Series B-2 103,466 100,741 2,396,811 3,132,600 100,741 Series B-3 2,482,490 2,482,488 74,999,934 64,117,000 2,482,488 Total 6,193,164 5,317,094 154,491,078$ 129,236,151$ 5,317,094 September 30, 2025 June 30, 2026 The rights and preferences of the Preferred Stock as of June 30, 2026, are as follows: Conversion Optional Conversion The Preferred Stock is convertible, at the option of the holder, at any time and from time to time, and without the payment of additional consideration by the holder, into such number of fully paid and non-assessable shares of common stock as is determined by dividing the applicable Original Issue Price of such series of Preferred Stock by the Conversion Price. Mandatory Automatic Conversion Upon either (a) the closing of the sale of shares of common stock to the public at a price per share of at least three times the Original Issue Price of the Series B-1 Preferred Stock, in a firm-commitment underwritten public offering pursuant to an effective registration statement under the Securities Act of 1933, as amended, resulting in at least $100.0 million of proceeds, net of the underwriting discount and commissions, to the Company and in connection with such offering the common stock is listed on an United States national securities exchange, including the approval of at least one Series B Preferred Stock Director or (b) the date and time, or the occurrence of an event, specified by vote or written consent of the holders of at least a majority in interest of the then-outstanding Series B Preferred Stock, voting as a single class on an as converted to common stock basis, then (i) all outstanding shares of Preferred Stock shall automatically be converted into shares of common stock, at the then effective conversion rate calculated in the same manner as the Optional Conversion and (ii) such shares may not be reissued by the Company. Conversion Price The Conversion Price is initially equal to the Original Issue Price of the respective series of Preferred Stock. The Conversion Price is subject to adjustment in the event of any down-round, stock dividend, stock split, combination or other similar recapitalization. Upon the occurrence of certain regulatory approvals or in the event the First Tranche Expansion does not occur, holders of Series B Preferred Stock are required to forfeit a specified number of shares of Preferred Stock depending on which event occurred. Upon such
16 forfeiture, the Original Issue Price and corresponding Conversion Price would be adjusted to preserve the liquidation preference of such shares. Dividend Rights Series B Preferred Stock is entitled to receive, only when, as and if declared by the Board of Directors non-cumulative dividends at the rate of 6.0% of the respective original issue price (the “Series B Dividend”). The Company shall not declare, pay or set aside any dividends on common shares of the Company unless the holders of Preferred Stock then outstanding shall first receive, or simultaneously receive, in addition to the Series B Dividend, a dividend on each outstanding share of Preferred Stock in an amount at least equal to the product of (1) the dividend payable on each share of such class or series determined, as if all shares of such class or series had been converted into common stock and (2) the number of shares of common stock issuable upon conversion of a share of such series of Preferred Stock, in each case calculated on the record date for determination of the holders entitled to receive such dividend. As of June 30, 2026, no cash dividends have been declared or paid. Liquidation Preference In the event of any voluntary or involuntary liquidation, dissolution, or winding up of the Company, or Deemed Liquidation Event (defined below), the holders of Series B Preferred Stock are entitled to be paid an amount equal to the greater of (i) the original issuance price plus the amount of all declared but unpaid dividends on each such share or (ii) such amount per share as would have been payable had all shares of Series B Preferred Stock been converted into common stock. In the event that the assets and funds legally available for distribution to the stockholders are insufficient to pay the holders of shares of Series B Preferred Stock the full Series B preference amounts to which the holders shall be entitled, the holders of Series B Preferred Stock shall share ratably in any distribution of the assets and funds of the Company in proportion to the respective amounts that would otherwise be payable in respect of such shares held by them upon such distribution if all amounts payable on or with respect to such shares were paid in full. After the payment of all preferential amounts required to be paid to the holders of Series B Preferred Stock, the holders of Series A Preferred Stock are entitled to be paid an amount equal to the greater of (i) the original issuance price plus the amount of all declared but unpaid dividends on each such share or (ii) such amount per share as would have been payable had all shares of Series A Preferred Stock been converted into common stock. In the event that the assets and funds legally available for distribution to the stockholders are insufficient to pay the holders of shares of Series A Preferred Stock the full Series A preference amounts to which the holders shall be entitled, the holders of Series A Preferred Stock shall share ratably in any distribution of the assets and funds of the Company in proportion to the respective amounts that would otherwise be payable in respect of such shares held by them upon such distribution if all amounts payable on or with respect to such shares were paid in full. After the payment in full of the Preferred Stock preference amount, the remaining assets of the Company available for distribution to stockholders shall be distributed among the holders of common stock on a pro-rata basis. Each of the following events shall be considered a Deemed Liquidation Event (“Deemed Liquidation Event”) unless the holders of a majority of the then outstanding shares of Preferred Stock, voting together as a single class on an as converted to common stock basis elect otherwise, a merger, consolidation, or share exchange (other than one in which stockholders of the Company own a majority by voting power of the outstanding shares of the surviving or acquiring corporation) or a sale, lease, transfer, exclusive license or other disposition of all or substantially all of the assets of the Company, or transaction resulting in the issuance of securities representing in the aggregate a majority of the voting power of the Company’s issued and outstanding voting securities. Redemption Rights The Preferred Stock does not have redemption rights, except for the contingent redemption upon the occurrence of a Deemed Liquidation Events. Voting Rights The holders of the Preferred Stock are entitled to vote, together with the holders of common stock, as a single class, on all matters submitted to the shareholders for a vote and are entitled to the number of votes equal to the number of shares of common stock into which the Preferred Stock could convert on the record date for determination of shareholders entitled to vote.
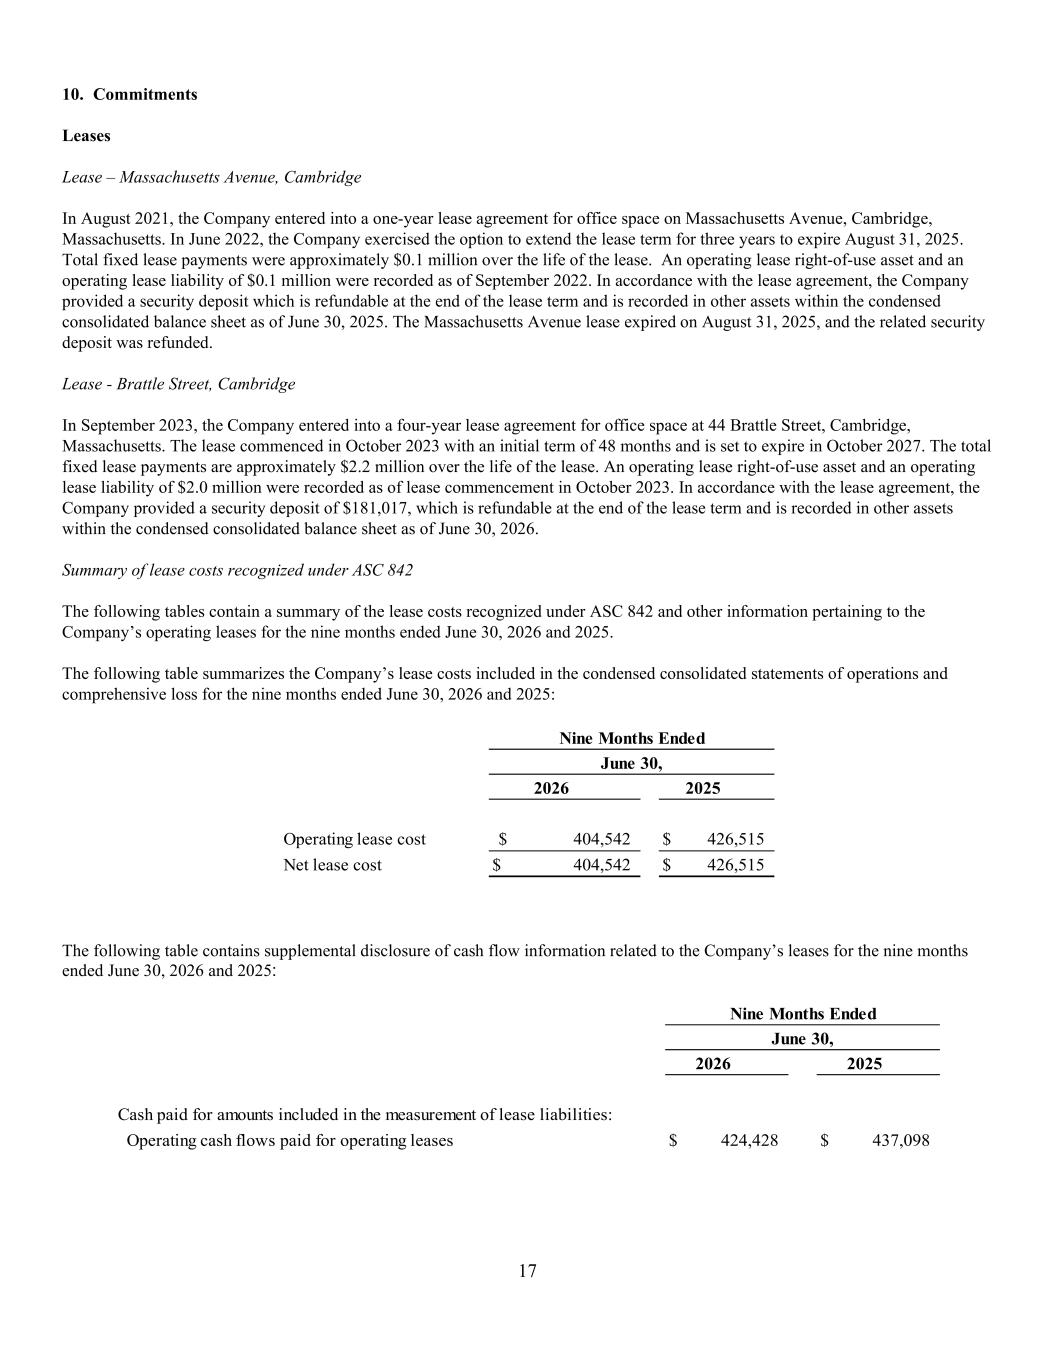
17 10. Commitments Leases Lease – Massachusetts Avenue, Cambridge In August 2021, the Company entered into a one-year lease agreement for office space on Massachusetts Avenue, Cambridge, Massachusetts. In June 2022, the Company exercised the option to extend the lease term for three years to expire August 31, 2025. Total fixed lease payments were approximately $0.1 million over the life of the lease. An operating lease right-of-use asset and an operating lease liability of $0.1 million were recorded as of September 2022. In accordance with the lease agreement, the Company provided a security deposit which is refundable at the end of the lease term and is recorded in other assets within the condensed consolidated balance sheet as of June 30, 2025. The Massachusetts Avenue lease expired on August 31, 2025, and the related security deposit was refunded. Lease - Brattle Street, Cambridge In September 2023, the Company entered into a four-year lease agreement for office space at 44 Brattle Street, Cambridge, Massachusetts. The lease commenced in October 2023 with an initial term of 48 months and is set to expire in October 2027. The total fixed lease payments are approximately $2.2 million over the life of the lease. An operating lease right-of-use asset and an operating lease liability of $2.0 million were recorded as of lease commencement in October 2023. In accordance with the lease agreement, the Company provided a security deposit of $181,017, which is refundable at the end of the lease term and is recorded in other assets within the condensed consolidated balance sheet as of June 30, 2026. Summary of lease costs recognized under ASC 842 The following tables contain a summary of the lease costs recognized under ASC 842 and other information pertaining to the Company’s operating leases for the nine months ended June 30, 2026 and 2025. The following table summarizes the Company’s lease costs included in the condensed consolidated statements of operations and comprehensive loss for the nine months ended June 30, 2026 and 2025: 2026 2025 Operating lease cost 404,542$ 426,515$ Net lease cost 404,542$ 426,515$ Nine Months Ended June 30, The following table contains supplemental disclosure of cash flow information related to the Company’s leases for the nine months ended June 30, 2026 and 2025: 2026 2025 Cash paid for amounts included in the measurement of lease liabilities: Operating cash flows paid for operating leases 424,428$ 437,098$ Nine Months Ended June 30,
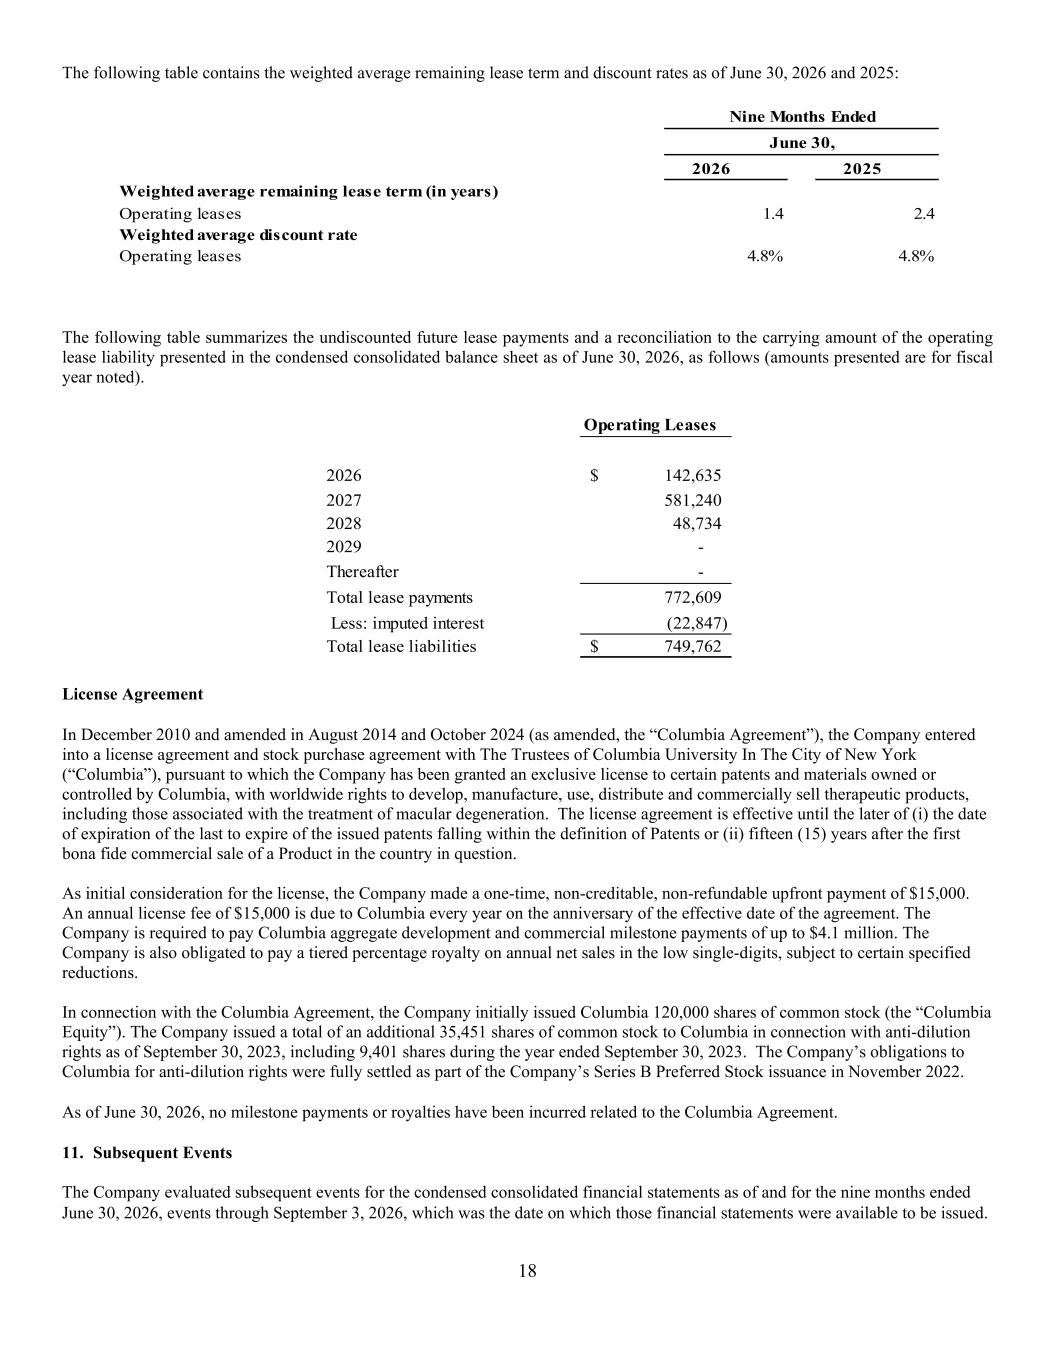
18 The following table contains the weighted average remaining lease term and discount rates as of June 30, 2026 and 2025: 2026 2025 Weighted average remaining lease term (in years) Operating leases 1.4 2.4 Weighted average discount rate Operating leases 4.8% 4.8% Nine Months Ended June 30, The following table summarizes the undiscounted future lease payments and a reconciliation to the carrying amount of the operating lease liability presented in the condensed consolidated balance sheet as of June 30, 2026, as follows (amounts presented are for fiscal year noted). Operating Leases 2026 142,635$ 2027 581,240 2028 48,734 2029 - Thereafter - Total lease payments 772,609 Less: imputed interest (22,847) Total lease liabilities 749,762$ License Agreement In December 2010 and amended in August 2014 and October 2024 (as amended, the “Columbia Agreement”), the Company entered into a license agreement and stock purchase agreement with The Trustees of Columbia University In The City of New York (“Columbia”), pursuant to which the Company has been granted an exclusive license to certain patents and materials owned or controlled by Columbia, with worldwide rights to develop, manufacture, use, distribute and commercially sell therapeutic products, including those associated with the treatment of macular degeneration. The license agreement is effective until the later of (i) the date of expiration of the last to expire of the issued patents falling within the definition of Patents or (ii) fifteen (15) years after the first bona fide commercial sale of a Product in the country in question. As initial consideration for the license, the Company made a one-time, non-creditable, non-refundable upfront payment of $15,000. An annual license fee of $15,000 is due to Columbia every year on the anniversary of the effective date of the agreement. The Company is required to pay Columbia aggregate development and commercial milestone payments of up to $4.1 million. The Company is also obligated to pay a tiered percentage royalty on annual net sales in the low single-digits, subject to certain specified reductions. In connection with the Columbia Agreement, the Company initially issued Columbia 120,000 shares of common stock (the “Columbia Equity”). The Company issued a total of an additional 35,451 shares of common stock to Columbia in connection with anti-dilution rights as of September 30, 2023, including 9,401 shares during the year ended September 30, 2023. The Company’s obligations to Columbia for anti-dilution rights were fully settled as part of the Company’s Series B Preferred Stock issuance in November 2022. As of June 30, 2026, no milestone payments or royalties have been incurred related to the Columbia Agreement. 11. Subsequent Events The Company evaluated subsequent events for the condensed consolidated financial statements as of and for the nine months ended June 30, 2026, events through September 3, 2026, which was the date on which those financial statements were available to be issued.
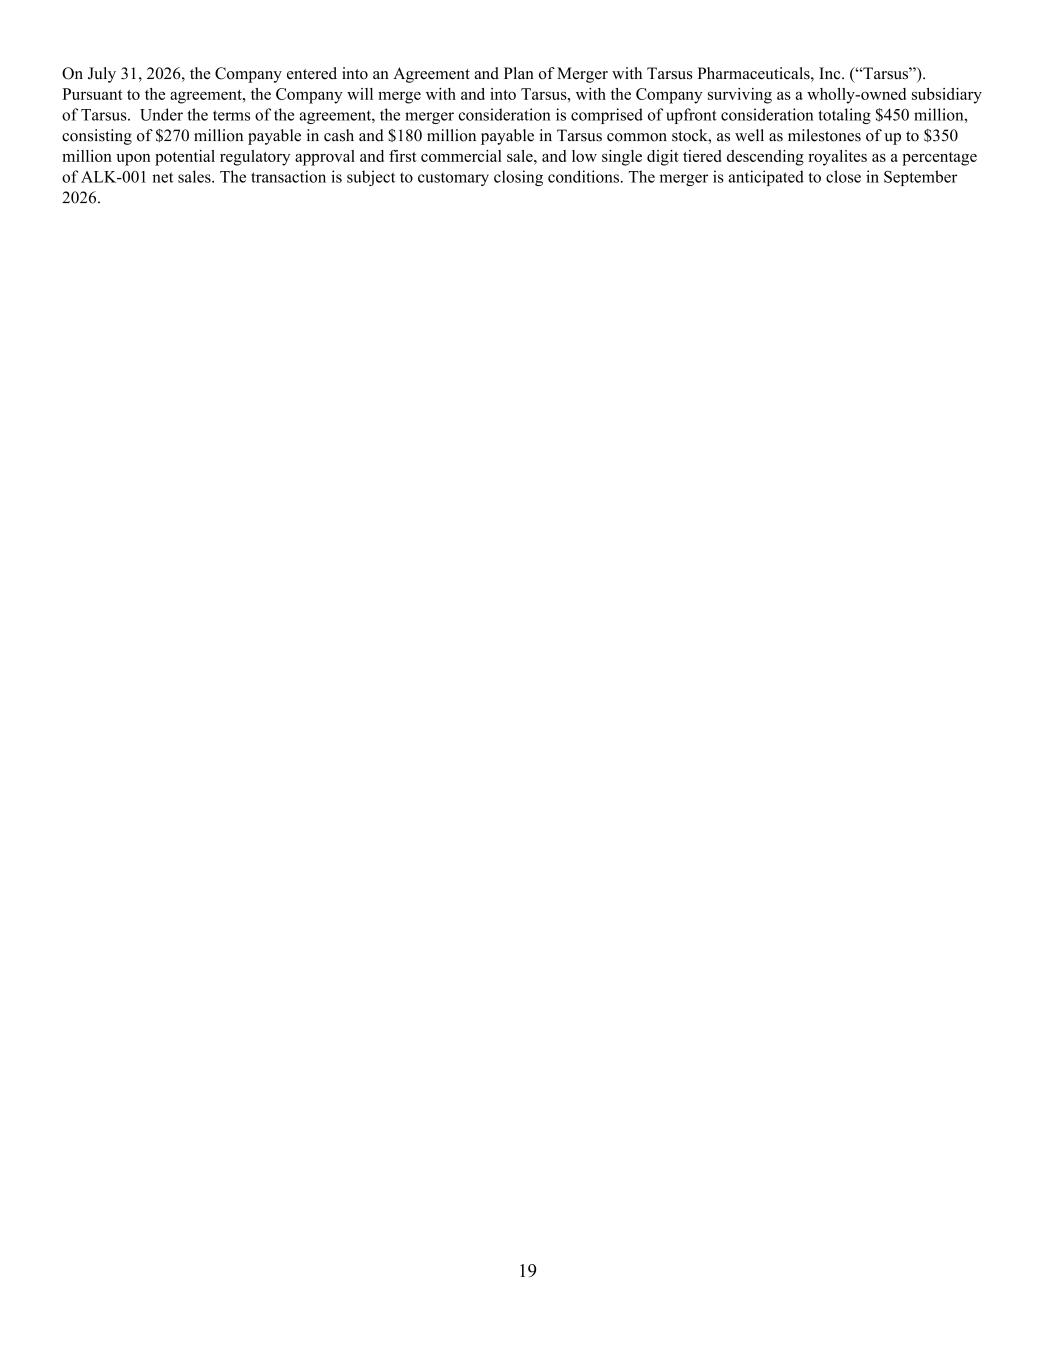
19 On July 31, 2026, the Company entered into an Agreement and Plan of Merger with Tarsus Pharmaceuticals, Inc. (“Tarsus”). Pursuant to the agreement, the Company will merge with and into Tarsus, with the Company surviving as a wholly-owned subsidiary of Tarsus. Under the terms of the agreement, the merger consideration is comprised of upfront consideration totaling $450 million, consisting of $270 million payable in cash and $180 million payable in Tarsus common stock, as well as milestones of up to $350 million upon potential regulatory approval and first commercial sale, and low single digit tiered descending royalites as a percentage of ALK-001 net sales. The transaction is subject to customary closing conditions. The merger is anticipated to close in September 2026.
UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION
The following unaudited pro forma condensed combined financial information combines the historical financial position and results of operations of Tarsus Pharmaceuticals, Inc., a Delaware corporation (“Tarsus”), and Alkeus Pharmaceuticals, Inc., a Delaware corporation (“Alkeus”), after giving effect to (i) the merger (the “Merger”), as further described in Note 1. Description of the Transactions and Basis of Presentation, and (ii) the private placement completed by Tarsus for gross proceeds of approximately $125 million (the “Financing” and, together with the Merger, the “Transactions”), and the pro forma effects of certain assumptions and adjustments described in “Notes to the Unaudited Pro Forma Condensed Combined Financial Information” below. The unaudited pro forma condensed combined financial information has been prepared in accordance with Article 11 of Regulation S-X and should be read in conjunction with the accompanying notes. The Financing was completed on August 7, 2026 and the Merger was completed on September 4, 2026 (the “Closing Date”).
The Merger is reflected in the pro forma condensed combined financial statements in accordance with Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) 810, Consolidation. Tarsus has preliminarily determined that Alkeus does not meet the definition of a business under ASC 805, Business Combinations, because substantially all of the fair value of the gross assets acquired is concentrated in a single in-process research and development ("IPR&D") asset, gildeuretinol. Tarsus has also determined that Alkeus is a variable interest entity ("VIE") and that Tarsus is its primary beneficiary. Under ASC 810, Alkeus' identifiable assets and liabilities are recognized at fair value, with no goodwill. The difference between the fair value of consideration transferred and the net fair value of the identifiable assets acquired and liabilities assumed is recognized as a gain or loss on initial consolidation.
Tarsus and Alkeus have different fiscal year-ends. Tarsus’ fiscal year ends on December 31, whereas Alkeus’ fiscal year ends on September 30. As permitted by Rule 11-02(c)(3) of Regulation S-X, the historical results of Alkeus included in the unaudited pro forma condensed combined statement of operations may have a fiscal year-end that differs from Tarsus’ fiscal year-end by no more than one fiscal quarter. Accordingly, the unaudited pro forma condensed combined statement of operations for the year ended December 31, 2025 combines Tarsus' historical results for the year ended December 31, 2025 with Alkeus’ historical results for the year ended September 30, 2025. For purposes of the unaudited pro forma condensed combined statement of operations for the six months ended June 30, 2026, Alkeus’ historical results for the six-month period ended June 30, 2026 were derived by subtracting Alkeus’ historical results for the three months ended December 31, 2025 from its historical results for the nine months ended June 30, 2026. For the three months ended December 31, 2025, which are not reflected in the unaudited pro forma condensed combined statements of operations presented herein, Alkeus had no revenue and a net loss of $12 million.
The unaudited pro forma condensed combined financial information and related notes should be read in conjunction with the following historical financial statements and the accompanying notes:
• The historical audited financial statements of Tarsus and the related notes included in Tarsus’ Annual Report on Form 10-K as of and for the year ended December 31, 2025;
• The historical audited consolidated financial statements of Alkeus and the related notes as of and for the year ended September 30, 2025, included elsewhere in this Form 8-K/A pursuant to Rule 3-05 of Regulation S-X;
• The historical unaudited condensed financial statements of Tarsus and the related notes included in Tarsus’ Quarterly Report on Form 10-Q for the six months ended June 30, 2026; and
• The historical unaudited condensed consolidated financial statements of Alkeus and the related notes as of and for the nine months ended June 30, 2026, included elsewhere in this Form 8-K/A pursuant to Rule 3-05 of Regulation S-X.
The unaudited pro forma condensed combined balance sheet as of June 30, 2026, gives pro forma effect to the Transactions described below as if they had occurred on June 30, 2026. The unaudited pro forma condensed combined statements of operations for the six months ended June 30, 2026, and the year ended December 31, 2025, give effect to the Transactions as if they had occurred on January 1, 2025, the beginning of the fiscal year presented.
The unaudited pro forma condensed combined financial information appearing below is based on available preliminary information and certain assumptions that are believed to be reasonable as of the date of this filing and also does not consider any potential effects of changes in market conditions on revenues or expense efficiencies, among other factors. Future results may vary significantly from the results reflected because of such factors. In addition, as explained in more detail in the accompanying notes, the preliminary allocation of the pro forma purchase price reflected in the unaudited pro forma condensed combined financial information is subject to adjustment and may vary significantly from the final determination of fair value as additional information becomes available and as additional analyses are performed.
UNAUDITED PRO FORMA CONDENSED COMBINED BALANCE SHEET
As of June 30, 2026
(In thousands, except share information)
Tarsus Historical | Alkeus Historical | Reclassification Adjustments | Notes | Financing Adjustments (Note 1) | Merger Transaction Accounting Adjustments | Notes | Pro Forma Combined | |||||||||||||||||||||||||||||||||||||||||||
ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||
Current assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||
Cash and cash equivalents | $ | 204,595 | $ | 48,745 | $ | — | $ | 119,000 | $ | (245,828) | 3(a), 3(b) | $ | 126,512 | |||||||||||||||||||||||||||||||||||||
Marketable securities | 245,095 | — | — | — | — | 245,095 | ||||||||||||||||||||||||||||||||||||||||||||
Accounts receivable, net | 96,028 | — | — | — | — | 96,028 | ||||||||||||||||||||||||||||||||||||||||||||
Inventory | 4,377 | — | — | — | — | 4,377 | ||||||||||||||||||||||||||||||||||||||||||||
Other receivables | 2,281 | — | — | — | — | 2,281 | ||||||||||||||||||||||||||||||||||||||||||||
Prepaid expenses and other assets | 9,613 | 927 | — | — | — | 10,540 | ||||||||||||||||||||||||||||||||||||||||||||
Total current assets | 561,989 | 49,672 | — | 119,000 | (245,828) | 484,833 | ||||||||||||||||||||||||||||||||||||||||||||
Restricted cash, non-current | 2,001 | — | 381 | 2(f) | — | — | 2,382 | |||||||||||||||||||||||||||||||||||||||||||
Inventory, non-current | 2,525 | — | — | — | — | 2,525 | ||||||||||||||||||||||||||||||||||||||||||||
Property and equipment, net | 20,489 | 258 | — | — | — | 20,747 | ||||||||||||||||||||||||||||||||||||||||||||
Intangible assets, net | 6,885 | — | — | — | — | 6,885 | ||||||||||||||||||||||||||||||||||||||||||||
Operating lease right-of-use assets | 9,911 | 696 | — | — | — | 10,607 | ||||||||||||||||||||||||||||||||||||||||||||
Long-term investments | 6,682 | — | — | — | — | 6,682 | ||||||||||||||||||||||||||||||||||||||||||||
Other assets | 660 | 381 | (381) | 2(f) | — | — | 660 | |||||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 611,142 | $ | 51,007 | $ | — | $ | 119,000 | $ | (245,828) | $ | 535,321 | ||||||||||||||||||||||||||||||||||||||
LIABILITIES, REDEEMABLE CONVERTIBLE PREFERRED STOCK AND STOCKHOLDERS’ EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||
Current liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||
Accounts payable | $ | 40,141 | $ | 1,383 | $ | — | $ | — | $ | — | $ | 41,524 | ||||||||||||||||||||||||||||||||||||||
Accrued expenses | — | 6,132 | (6,132) | 2(a), 2(b) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||
Accrued payroll and benefits | 11,887 | — | 2,326 | 2(a) | — | 9,103 | 3(c) | 23,316 | ||||||||||||||||||||||||||||||||||||||||||
Operating lease liability, current portion | — | 565 | (565) | 2(c) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||
Other accrued liabilities | 123,725 | — | 4,371 | 2(b), 2(c) | — | 24,811 | 3(a), 3(b) | 152,907 | ||||||||||||||||||||||||||||||||||||||||||
Total current liabilities | 175,753 | 8,080 | — | — | 33,914 | 217,747 | ||||||||||||||||||||||||||||||||||||||||||||
Long-term debt, net | 72,762 | — | — | — | — | 72,762 | ||||||||||||||||||||||||||||||||||||||||||||
Operating lease liability, net of current portion | — | 185 | (185) | 2(e) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||
Other liabilities | — | 1,160 | (1,160) | 2(d) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||
Contingent consideration | — | — | — | — | 95,898 | 3(a) | 95,898 | |||||||||||||||||||||||||||||||||||||||||||
Other long-term liabilities | 15,895 | — | 1,345 | 2(d), 2(e) | — | — | 17,240 | |||||||||||||||||||||||||||||||||||||||||||
Total liabilities | 264,410 | 9,425 | — | — | 129,812 | 403,647 | ||||||||||||||||||||||||||||||||||||||||||||
Commitments and contingencies | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
Redeemable convertible preferred stock | ||||||||||||||||||||||||||||||||||||||||||||||||||
Series A Redeemable Convertible Preferred Stock | $ | — | $ | 2,094 | $ | — | $ | — | $ | (2,094) | 3(d) | $ | — | |||||||||||||||||||||||||||||||||||||
Series B-1 Preferred Stock Convertible Preferred Stock | — | 59,892 | — | — | (59,892) | 3(d) | — | |||||||||||||||||||||||||||||||||||||||||||
Series B-2 Preferred Stock Convertible Preferred Stock | — | 3,133 | — | — | (3,133) | 3(d) | — | |||||||||||||||||||||||||||||||||||||||||||
Series B-3 Preferred Stock Convertible Preferred Stock | — | 64,117 | — | — | (64,117) | 3(d) | — | |||||||||||||||||||||||||||||||||||||||||||
Total redeemable convertible preferred stock | — | 129,236 | — | (129,236) | — | |||||||||||||||||||||||||||||||||||||||||||||
Stockholders’ equity: | — | |||||||||||||||||||||||||||||||||||||||||||||||||
Common stock | 6 | — | — | — | — | 6 | ||||||||||||||||||||||||||||||||||||||||||||
Additional paid-in capital | 799,429 | 21,943 | — | 119,000 | 220,089 | 3(d) | 1,160,461 | |||||||||||||||||||||||||||||||||||||||||||
Accumulated other comprehensive income (loss) | (557) | — | — | — | — | (557) | ||||||||||||||||||||||||||||||||||||||||||||
Accumulated deficit | (452,146) | (109,597) | — | — | (466,493) | 3(d) | (1,028,236) | |||||||||||||||||||||||||||||||||||||||||||
Total stockholders’ equity | 346,732 | (87,654) | — | 119,000 | (246,404) | 131,674 | ||||||||||||||||||||||||||||||||||||||||||||
Total liabilities, redeemable convertible preferred stock and stockholders’ equity | $ | 611,142 | $ | 51,007 | $ | — | $ | 119,000 | $ | (245,828) | $ | 535,321 | ||||||||||||||||||||||||||||||||||||||
See the accompanying notes to the Unaudited Pro Forma Condensed Combined Financial Information.
UNAUDITED PRO FORMA CONDENSED COMBINED STATEMENTS OF OPERATIONS For the Six Months Ended June 30, 2026
(In thousands, except share and per share information)
(In thousands, except share and per share information)
Tarsus Historical | Alkeus Historical | Reclassification Adjustments | Notes | Merger Transaction Accounting Adjustments | Notes | Pro Forma Combined | ||||||||||||||||||||||||||||||||||||||
Revenues: | ||||||||||||||||||||||||||||||||||||||||||||
Product sales, net | $ | 319,299 | $ | — | $ | — | $ | — | $ | 319,299 | ||||||||||||||||||||||||||||||||||
License fees and collaboration revenue | 16,667 | — | — | — | 16,667 | |||||||||||||||||||||||||||||||||||||||
Total revenues | 335,966 | — | — | — | 335,966 | |||||||||||||||||||||||||||||||||||||||
Operating expenses: | ||||||||||||||||||||||||||||||||||||||||||||
Cost of sales | 21,509 | — | — | — | 21,509 | |||||||||||||||||||||||||||||||||||||||
Research and development | 53,361 | 15,562 | — | — | 68,923 | |||||||||||||||||||||||||||||||||||||||
General and administrative | — | 9,005 | (9,005) | 2(g) | — | — | ||||||||||||||||||||||||||||||||||||||
Selling, general and administrative | 287,126 | — | 9,005 | 2(g) | — | 296,131 | ||||||||||||||||||||||||||||||||||||||
Total operating expenses | 361,996 | 24,567 | — | — | 386,563 | |||||||||||||||||||||||||||||||||||||||
Loss from operations before other income (expense) | (26,030) | (24,567) | — | — | (50,597) | |||||||||||||||||||||||||||||||||||||||
Other income (expense): | ||||||||||||||||||||||||||||||||||||||||||||
Interest income | $ | 7,420 | $ | 1,043 | $ | — | $ | — | $ | 8,463 | ||||||||||||||||||||||||||||||||||
Interest expense | (4,284) | — | — | — | (4,284) | |||||||||||||||||||||||||||||||||||||||
Gain on exchange of long-term investments | 2,812 | — | — | — | 2,812 | |||||||||||||||||||||||||||||||||||||||
Other income (expense), net | (368) | 4 | — | — | (364) | |||||||||||||||||||||||||||||||||||||||
Total other income (expense), net | $ | 5,580 | $ | 1,047 | $ | — | $ | — | $ | 6,627 | ||||||||||||||||||||||||||||||||||
Provision for income taxes | (5,068) | — | — | — | (5,068) | |||||||||||||||||||||||||||||||||||||||
Net loss | $ | (25,518) | $ | (23,520) | $ | — | $ | — | $ | (49,038) | ||||||||||||||||||||||||||||||||||
Net loss per share, basic and diluted | $ | (0.59) | 3(j) | $ | (1.01) | |||||||||||||||||||||||||||||||||||||||
Weighted-average shares outstanding, basic and diluted | 43,176,514 | 3(j) | 48,317,350 | |||||||||||||||||||||||||||||||||||||||||
See the accompanying notes to the Unaudited Pro Forma Condensed Combined Financial Information.
UNAUDITED PRO FORMA CONDENSED COMBINED STATEMENTS OF OPERATIONS For the Year Ended December 31, 2025
(In thousands, except share and per share amounts)
(In thousands, except share and per share amounts)
Tarsus Historical Year Ended December 31, 2025 | Alkeus Historical Year Ended September 30, 2025 | Reclassification Adjustments | Notes | Merger Transaction Accounting Adjustments | Notes | Pro Forma Combined | ||||||||||||||||||||||||||||||||||||||
Revenues: | ||||||||||||||||||||||||||||||||||||||||||||
Product sales, net | $ | 451,360 | $ | — | $ | — | $ | — | $ | 451,360 | ||||||||||||||||||||||||||||||||||
License fees and collaboration revenue | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
Total revenues | 451,360 | — | — | — | 451,360 | |||||||||||||||||||||||||||||||||||||||
Operating expenses: | ||||||||||||||||||||||||||||||||||||||||||||
Cost of sales | 30,684 | — | — | — | 30,684 | |||||||||||||||||||||||||||||||||||||||
Research and development | 64,322 | 32,447 | — | 11,767 | 3(e), 3(f) | 108,536 | ||||||||||||||||||||||||||||||||||||||
Acquired in-process research and development expense | — | — | — | 567,845 | 3(g) | 567,845 | ||||||||||||||||||||||||||||||||||||||
General and administrative | — | 21,374 | (21,374) | 2(h) | — | — | ||||||||||||||||||||||||||||||||||||||
Selling, general and administrative | 427,323 | — | 21,374 | 2(h) | 21,835 | 3(e), 3(f), 3(h) | 470,532 | |||||||||||||||||||||||||||||||||||||
Total operating expenses | 522,329 | 53,821 | — | 601,447 | 1,177,597 | |||||||||||||||||||||||||||||||||||||||
Loss from operations before other income (expense) | (70,969) | (53,821) | — | (601,447) | (726,237) | |||||||||||||||||||||||||||||||||||||||
Other income (expense): | ||||||||||||||||||||||||||||||||||||||||||||
Interest income | 15,747 | 1,914 | — | — | 17,661 | |||||||||||||||||||||||||||||||||||||||
Interest expense | (8,935) | — | — | — | (8,935) | |||||||||||||||||||||||||||||||||||||||
Other income (expense), net | (202) | 133 | — | — | (69) | |||||||||||||||||||||||||||||||||||||||
Gain on initial consolidation of VIE | — | — | — | 23,570 | 3(a) | 23,570 | ||||||||||||||||||||||||||||||||||||||
Change in fair value of preferred stock tranche liability | — | 1,950 | — | (1,950) | 3(i) | — | ||||||||||||||||||||||||||||||||||||||
Total other income (expense), net | 6,610 | 3,997 | — | 21,620 | 32,227 | |||||||||||||||||||||||||||||||||||||||
Provision for income taxes | (2,059) | — | — | — | (2,059) | |||||||||||||||||||||||||||||||||||||||
Net loss | $ | (66,418) | $ | (49,824) | $ | — | $ | (579,827) | $ | (696,069) | ||||||||||||||||||||||||||||||||||
Net loss per share, basic and diluted | $ | (1.59) | 3(j) | $ | (14.83) | |||||||||||||||||||||||||||||||||||||||
Weighted-average shares outstanding, basic and diluted | 41,784,014 | 3(j) | 46,924,850 | |||||||||||||||||||||||||||||||||||||||||
See the accompanying notes to the Unaudited Pro Forma Condensed Combined Financial Information.
NOTES TO THE UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION
Note 1. Description of the Transactions and Basis of Presentation
Description of the Merger
On September 4, 2026, Tarsus completed its previously announced acquisition of Alkeus pursuant to the Agreement and Plan of Merger, dated as of July 31, 2026 (the "Merger Agreement"), by and among Tarsus, Alkeus, Apex 2026 Merger Sub, Inc., a Delaware corporation and a direct wholly owned subsidiary of Tarsus ("Merger Sub"), and Shareholder Representative Services LLC, solely in its capacity as the securityholders' representative. Pursuant to the Merger Agreement, the Merger Sub merged with and into Alkeus, with Alkeus continuing as the surviving corporation and a wholly owned subsidiary of Tarsus.
For accounting purposes, Tarsus determined that Alkeus does not meet the definition of a business under ASC 805, Business Combinations, because substantially all of the fair value of the gross assets acquired are concentrated in a single IPR&D asset, gildeuretinol. Alkeus was determined to be a VIE under ASC 810, because it did not have sufficient equity to finance its activities without additional subordinated financial support. Tarsus was determined to be the primary beneficiary of Alkeus and accordingly will consolidate Alkeus.
Consideration paid in the Merger consisted of:
•$270.0 million of cash consideration, subject to specified adjustments under the Merger Agreement;
•2,769,696 shares of Tarsus common stock; and
•Qualifying seller transaction costs included in the determination of the consideration transferred.
The Merger Agreement additionally provides for future contingent consideration consisting of:
•$250.0 million upon the first U.S. regulatory approval of a product made with gildeuretinol to be settled in cash or shares, (the "Regulatory Approval Milestone");
•$100.0 million upon the first commercial sale of a product made with gildeuretinol in the United States (the "First Commercial Sale Milestone");
•Tiered, decreasing royalty payments on annual worldwide net sales of products made with gildeuretinol, beginning at a rate of less than 5.0%, payable on a country-by-country basis until the latest of patent expiration, regulatory exclusivity expiration, or ten years after first commercial sale (the “Sales Royalty Earnout”).
Because the Merger is accounted for as the initial consolidation of a VIE, each contingent consideration arrangement is recognized at its acquisition-date fair value as part of the consideration transferred. This treatment does not depend on whether payment is probable. The preliminary fair values at the Closing Date were:
•The Regulatory Approval Milestone has a preliminary estimated fair value of $45.5 million, and is payable in cash or shares of Tarsus common stock, subject to a limit of issuable shares per the Merger Agreement, with any excess payable in cash. The arrangement is classified as a liability under ASC 480, Distinguishing Liabilities from Equity. Fair value was estimated with a probability weighted model. Significant unobservable inputs include the estimated probability and timing of U.S. regulatory approval and a risk-adjusted discount rate. Undiscounted outcomes range from $0, if approval is not obtained, to $250.0 million.
•The First Commercial Sale Milestone has a preliminary estimated fair value of $18.2 million, and is payable in cash. Fair value was estimated with a probability weighted model. Significant unobservable inputs include the estimated probability and timing of the first commercial sale and a risk-adjusted discount rate. Undiscounted outcomes range from $0 to $100.0 million.
•The Sales Royalty Earnout has a preliminary estimated fair value of $32.2 million, and is payable in cash. The valuation estimate is preliminary and is subject to change based on the finalization of a Monte Carlo simulation. This fair value was estimated with a probability weighted model with significant unobservable inputs including projected net sales, probability of commercial success and a risk-adjusted discount rate. Total undiscounted royalty payments are not capped and cannot be reasonably estimated because they depend on future net sales.
Description of the Financing
In August 2026, Tarsus entered into a Securities Purchase Agreement (the "Purchase Agreement") with a syndicate of existing and new healthcare investors for the sale of shares of Tarsus' common stock and pre-funded warrants to purchase shares of Tarsus' common stock in a private placement (the "Financing"). Pursuant to the terms of the Purchase Agreement, Tarsus issued 2,098,519 shares of its common stock at a purchase price of $56.00 per share and pre-funded warrants to purchase an aggregate 133,625 shares of common stock at a purchase price of $55.9999 per pre-funded warrant (the purchase price per share less $0.0001, the exercise price of the pre-funded warrants), which resulted in gross proceeds of approximately $125.0 million and net proceeds of approximately $119.0 million, after deducting placement agent fees and other offering expenses of approximately $6.0 million. The private placement closed on August 7, 2026. Its effects are presented separately from the transaction accounting adjustments for the Merger in the column captioned "Financing Adjustments." The adjustment reflects an increase to cash for the net proceeds received and a corresponding increase to Additional paid-in capital.
Basis of Presentation
The unaudited pro forma condensed combined financial information has been prepared in accordance with Article 11 of Regulation S-X. The unaudited pro forma condensed combined balance sheet as of June 30, 2026, combines the historical unaudited condensed balance sheet of Tarsus and the historical unaudited condensed consolidated balance sheet of Alkeus, giving effect to the Transactions as if they had been consummated on June 30, 2026. The unaudited pro forma condensed combined statements of operations for the six months ended June 30, 2026, and the year ended December 31, 2025, combine the historical condensed statements of operations of Tarsus and the historical condensed consolidated statements of operations of Alkeus, giving effect to the Transactions as if they had been consummated on January 1, 2025, the first day of Tarsus' fiscal year 2025.
The unaudited pro forma condensed combined financial information is presented for informational purposes only and does not necessarily indicate the financial results of the combined company had the Transactions occurred at the dates indicated, nor does it necessarily indicate the results of the operations in future periods or the future financial position of the combined company. The valuation analyses and calculations necessary to determine the estimated fair value of contingent consideration and the fair values of the assets acquired and liabilities assumed have not been finalized. Accordingly, the preliminary allocation of the acquisition fair value reflected in the unaudited pro forma condensed combined financial information represents preliminary estimates and assumptions that Tarsus believes are reasonable as of the date of this filing and is subject to adjustment as additional information becomes available and additional analyses are performed.
The final allocation is expected to be completed when Tarsus files its report on Form 10-Q for the quarter ended September 30, 2026 and could differ materially from the preliminary allocation used in the transaction accounting adjustments. The unaudited pro forma condensed combined financial information is presented for illustrative purposes only and does not reflect the costs of any integration activities or cost savings or synergies that may be achieved as a result of the Merger.
Given Tarsus’ history of net losses and valuation allowance, management has estimated a pro forma annual effective income tax rate of 0%. Accordingly, the adjustments reflected in the unaudited pro forma condensed combined statements of operations do not include any additional income tax adjustment.
Note 2. Tarsus and Alkeus Reclassification Adjustments
During the preparation of the unaudited pro forma condensed combined financial information, Tarsus performed a preliminary analysis of Alkeus’ financial information to identify differences in accounting policies and financial statement presentation as compared to those of Tarsus. At this time, Tarsus is not aware of any material differences between the accounting policies of Tarsus and Alkeus. However, certain reclassification adjustments have been made to conform Alkeus’ historical financial statements to the presentation used by Tarsus in the preparation of the unaudited pro forma condensed combined financial information.
The following reclassification adjustments were made to conform the presentation of Alkeus' historical unaudited condensed consolidated balance sheet as of June 30, 2026, to Tarsus' presentation:
(a) Represents a reclassification of $2.3 million of accrued expenses to accrued payroll and benefits.
(b) Represents a reclassification of $3.8 million of accrued expenses to other accrued liabilities.
(c) Represents a reclassification of $0.6 million operating lease liability, current portion to other accrued liabilities.
(d) Represents a reclassification of $1.2 million other liabilities to other long-term liabilities.
(e) Represents a reclassification of $0.2 million operating lease liability, net of current portion to other long-term liabilities.
(f) Represents a reclassification of $0.4 million other assets to Restricted cash, non-current.
The following reclassification adjustments were made to conform the presentation of Alkeus’ historical results of operations to Tarsus' presentation for purposes of the unaudited pro forma condensed combined statements of operations for the year ended December 31, 2025 and the six months ended June 30, 2026, respectively:
(g) Represents a reclassification of general and administrative to selling, general and administrative for the six month period ended June 30, 2026.
(h) Represents a reclassification of general and administrative to selling, general and administrative for the year ended December 31, 2025.
Note 3. Merger Transaction Accounting Adjustments
As described in Note 1, the Merger represents the initial consolidation of a VIE that does not constitute a business. Under ASC 810, the assets acquired and liabilities assumed are recognized at fair value in accordance with ASC 805-20, except goodwill. Any differences between the consideration transferred and the net amount recognized for the assets acquired and liabilities assumed is recognized as a gain or loss upon initial consolidation.
Merger Transaction Accounting Adjustments related to the unaudited pro forma condensed combined balance sheet as of June 30, 2026, are as follows:
a) Represents the preliminary fair value of consideration in connection with the Merger of $585.9 million, consisting of (i) $244.6 million of cash paid at closing, comprising $238.2 million paid to selling shareholders, $1.4 million of seller transaction costs paid by Tarsus, and the $5.0 million adjustment escrow funded with a third-party agent, (ii) $14.9 million of deferred consideration for option holder settlements recorded as an other accrued liability, (iii) contingent consideration liabilities of $95.9 million, and (iv) the issuance of 2,769,696 shares of Tarsus common stock for $230.5 million as share consideration.
The following table summarizes the preliminary fair value of consideration transferred (in thousands, except share and per share amounts):
Shares of Tarsus common stock issued as share consideration | 2,769,696 | |||||||
Price per share of Tarsus Common Stock (1) | $ | 83.21 | ||||||
Fair value of share consideration (2) | $ | 230,466 | ||||||
Cash consideration paid to selling shareholders (2) | 238,202 | |||||||
Seller transaction costs paid by buyer | 1,438 | |||||||
Deferred consideration - cash paid at closing for adjustment escrow (3) | 5,000 | |||||||
Deferred consideration - option holder settlements (4) | 14,853 | |||||||
Contingent consideration - Regulatory Milestone | 45,500 | |||||||
Contingent consideration - First Commercial Sale | 18,200 | |||||||
Contingent consideration - Sales Royalty Earnout | 32,198 | |||||||
Preliminary fair value of consideration transferred | $ | 585,857 | ||||||
(1) Represents the closing price per share of Tarsus Common Stock as of September 3, 2026.
(2) The share consideration and cash consideration amounts are presented net of approximately $11.6 million and $9.1 million, respectively, attributable to options accelerated in connection with the Merger Agreement that will be recognized as compensation expense immediately following the Closing Date.
(3) Represents a $5 million adjustment escrow funded at closing with a third-party escrow agent at the Closing Date to secure potential post-closing adjustments to the merger consideration.
(4) Represents amounts due to former option holders of Alkeus and settled subsequent to the Closing Date.
The following table summarizes the preliminary allocation of the preliminary fair value of consideration transferred based on the fair value of net assets acquired:
Assets | As of June 30, 2026 | |||||||
Cash and cash equivalents | $ | 48,745 | ||||||
Prepaid expenses | 927 | |||||||
Property and equipment, net | 258 | |||||||
Operating lease right of-use-assets | 696 | |||||||
Restricted cash, non-current | 381 | |||||||
Acquired IPR&D (1) | 564,800 | |||||||
Acquired inventory | 3,045 | |||||||
Total assets | 618,852 | |||||||
Liabilities | ||||||||
Accounts payable | 1,383 | |||||||
Accrued payroll and benefits | 2,326 | |||||||
Other accrued liabilities | 4,371 | |||||||
Other long-term liabilities | 1,345 | |||||||
Total liabilities | 9,425 | |||||||
Net assets acquired | 609,427 | |||||||
Gain on initial consolidation of VIE | $ | (23,570) | ||||||
(1) Reflects the preliminary fair value of the acquired IPR&D asset, estimated using an income approach based on risk-adjusted discounted future cash flows attributable to the asset. The acquired IPR&D asset represents Alkeus' research and development asset that was in-process and not yet completed as of the Closing Date. As the acquired IPR&D asset has no alternative future use, its fair value is charged to acquired in-process research and development expense.
b) Represents an adjustment of approximately $11.1 million to recognize buyer transaction costs incurred in connection with the Merger of approximately $1.2 million paid on the Closing Date and $9.9 million as an other accrued liability.
c) Represents an accrual of $9.1 million for cash payments to settle partially vested stock options accelerated in connection with the Merger Agreement as an increase to accrued payroll and benefits. Accelerated stock options were also settled in $11.6 million of stock-based compensation expense as discussed in Note 3(d).
d) The following table summarizes the Merger Transaction Accounting Adjustments impacting the redeemable convertible preferred stock and stockholders' equity balances of Alkeus, as well as new equity issued as consideration for the Merger (in thousands):
Elimination of Alkeus historical equity | Consideration Transferred (1) | Gain on acquisition (2) | Buyer transaction expenses (3) | Acquired Inventory and IPR&D (4) | Stock Option Accelerations (5) | Merger Transaction Accounting Adjustments | ||||||||||||||||||||||||||||||||||||||
Adjustments to preferred stock | $ | (129,236) | $ | — | $ | — | $ | — | $ | — | $ | — | $ | (129,236) | ||||||||||||||||||||||||||||||
Adjustments to additional paid-in capital | (21,943) | 230,466 | — | — | — | 11,566 | 220,089 | |||||||||||||||||||||||||||||||||||||
Adjustments to accumulated deficit | 109,597 | — | 23,570 | (11,146) | (567,845) | (20,669) | (466,493) | |||||||||||||||||||||||||||||||||||||
Net adjustment to redeemable preferred stock and stockholders' equity | $ | (41,582) | $ | 230,466 | $ | 23,570 | $ | (11,146) | $ | (567,845) | $ | (9,103) | $ | (375,640) | ||||||||||||||||||||||||||||||
(1) Refer to Note 3(a) which reflects the fair value of share consideration transferred.
(2) Refer to Note 3(a) which reflects the preliminary gain on initial consolidation of VIE.
(3) Refer to Note 3(b) which reflects recognition of incremental Tarsus transaction costs.
(4) Refer to Note 3(g) which reflects the immediate expensing of acquired IPR&D and inventory.
(5) Refer to Note 3(c) which reflects post-combination compensation expense for accelerated Alkeus option awards settled in cash and shares.
Merger Transaction Accounting Adjustments include the following adjustments related to the unaudited pro forma condensed combined statement of operations for the six months ended June 30, 2026 and year ended December 31, 2025, as follows:
e) Represents an adjustment of $1.8 million to record retention bonus compensation expense for cash bonuses awarded to certain employees for continuous service through Merger close and for a period thereafter, as an increase of $1.5 million research and development expense and $0.3 million to selling, general and administrative expense.
f) Reflects the allocation of compensation costs associated with the acceleration and settlement of Alkeus option awards in connection with the Merger, consisting of $10.3 million in research and development expense and $10.4 million in selling, general and administrative expense based on the respective option holders' functional classifications.
g) Reflects the expense recognition of acquired IPR&D of $564.8 million and acquired inventory of $3.0 million as acquired in-process research and development expense. The IPR&D and acquired inventory were determined to have no alternative future use and was expensed in accordance with ASC 730 for assets to be used in research and development.
h) Represents an adjustment of approximately $11.1 million to recognize buyer transaction costs incurred in connection with the Merger.
i) Represents the elimination of the changes in fair value as a result of preferred stock tranche right liabilities that were settled prior to the Merger Closing Date.
j) The unaudited pro forma condensed combined basic and diluted earnings per share calculations are based on the weighted average basic and diluted shares of Tarsus. The following table summarizes the computation of the unaudited pro forma basic and diluted loss per share (in thousands, except share and per share data):
For the Six Months Ended June 30, 2026 | For the Year Ended December 31, 2025 | |||||||||||||
Pro forma net loss attributable to stockholders | $ | (49,038) | $ | (696,069) | ||||||||||
Pro-forma weighted average shares outstanding - basic and diluted | 48,317,350 | 46,924,850 | ||||||||||||
Pro forma net loss per share - basic and diluted | $ | (1.01) | $ | (14.83) | ||||||||||
Pro forma weighted-average shares - basic and diluted | ||||||||||||||
Historical Tarsus weighted-average shares outstanding | 43,176,514 | 41,784,014 | ||||||||||||
Shares of Tarsus common stock issued to Alkeus stockholders pursuant to the Merger Agreement (1) | 2,769,696 | 2,769,696 | ||||||||||||
Shares of Tarsus common stock issued in connection with accelerated option awards (1) | 138,996 | 138,996 | ||||||||||||
Shares of Tarsus common stock issued for the Financing (1) | 2,098,519 | 2,098,519 | ||||||||||||
Shares underlying pre-funded warrants issued in connection with the Financing (1) | 133,625 | 133,625 | ||||||||||||
Pro forma weighted-average shares outstanding - basic and diluted | 48,317,350 | 46,924,850 | ||||||||||||
(1) As the Transactions are being reflected as if they had been consummated at the beginning of the periods presented, the calculation of weighted average basic and diluted shares outstanding assumes the shares issuable in connection with the Transactions have been outstanding for the entirety of the periods presented.